BVB CAPITAL PRIVATE LIMITED

AMFI-registered Mutual Fund Distributor

ARN: 348338

Blog

  • റിട്ടയർമെന്റിലേക്ക് ഇനി 18 മാസം മാത്രം? ഈ 4 കാര്യങ്ങൾ ആദ്യം നോക്കൂ

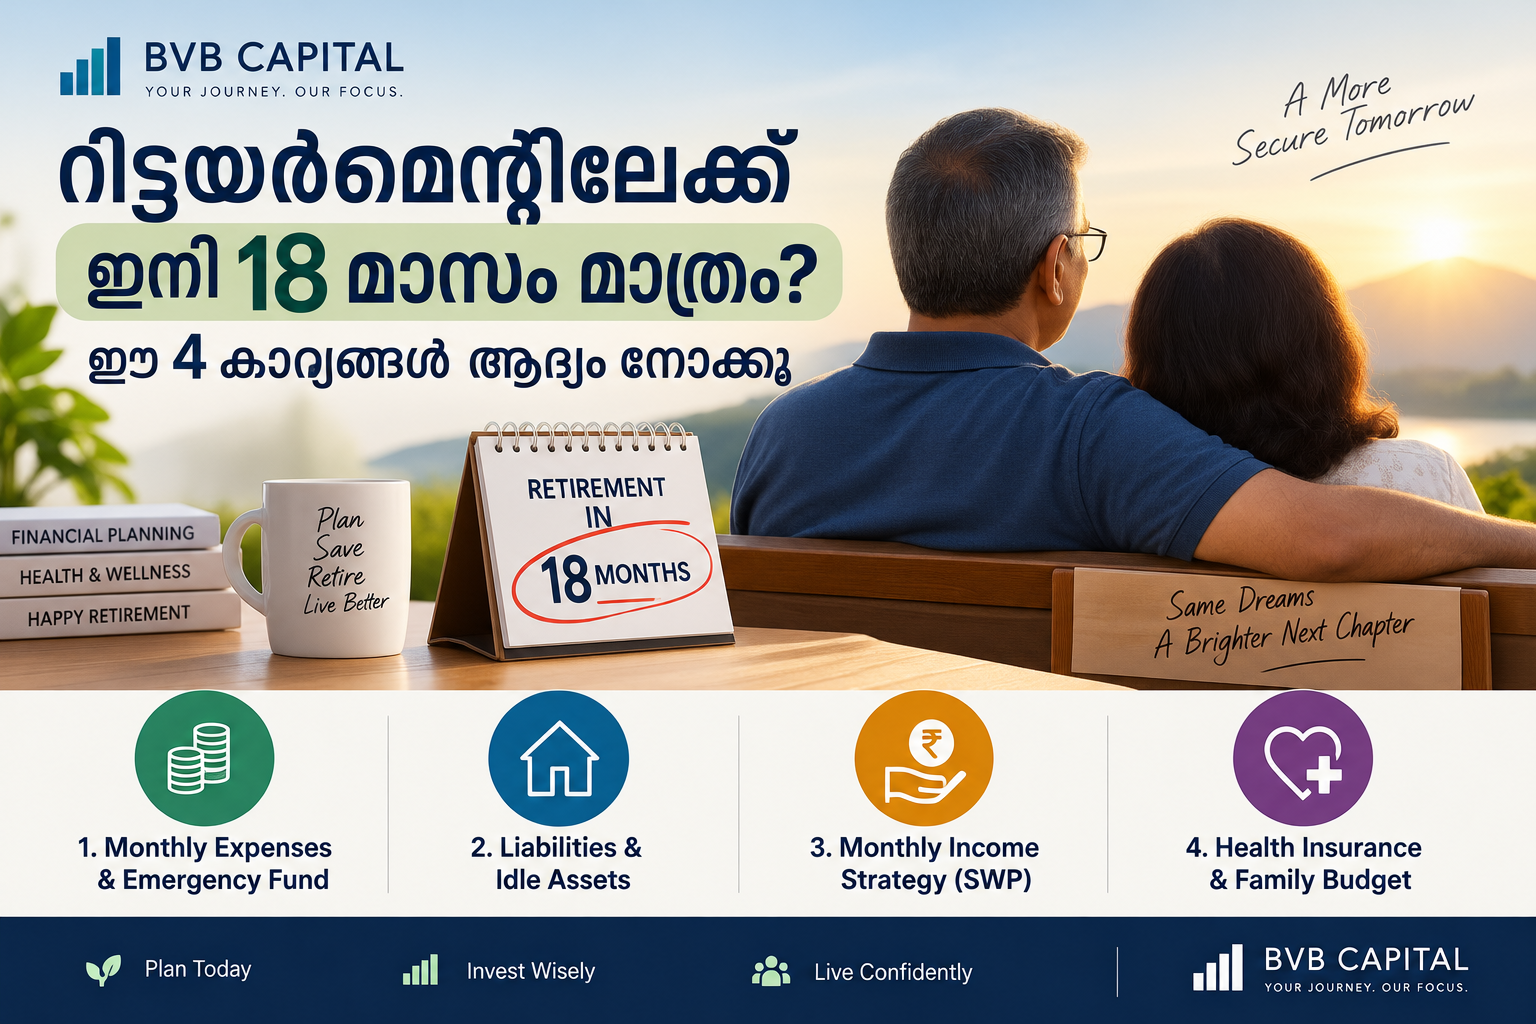
    റിട്ടയർമെന്റിലേക്ക് ഇനി 18 മാസം മാത്രം? ഈ 4 കാര്യങ്ങൾ ആദ്യം നോക്കൂ

    റിട്ടയർമെന്റിലേക്ക് ഇനി 18 മാസം മാത്രം ബാക്കിയുണ്ടെന്ന് കരുതുക.

    അപ്പോൾ പലരുടെയും മനസ്സിൽ ഒരേ ചോദ്യം വരും:

    “ഇത്ര കുറച്ച് സമയം മാത്രമുള്ളപ്പോൾ ഇനി എന്താണ് ചെയ്യാൻ കഴിയുക?”

    ഉത്തരം: ഇപ്പോൾ ചെയ്യേണ്ടത് വലിയ return തേടുന്നതല്ല. നിങ്ങളുടെ cash flow, ബാധ്യതകൾ, കൈവശമുള്ള ആസ്തികൾ, retirement-ന് ശേഷം വേണ്ട monthly income എന്നിവ ഒരുമിച്ച് നോക്കി ഒരു വ്യക്തമായ പ്ലാൻ ഉണ്ടാക്കുകയാണ്.

    റിട്ടയർമെന്റിന് മുമ്പുള്ള ഈ അവസാന ഘട്ടത്തിൽ ശ്രദ്ധിക്കേണ്ട നാല് കാര്യങ്ങൾ നമുക്ക് ലളിതമായി നോക്കാം.

    🎥 ഈ വിഷയം വീഡിയോയായി കാണാം

    റിട്ടയർമെന്റിനോട് അടുത്തിരിക്കുമ്പോൾ financial planning എങ്ങനെ ക്രമീകരിക്കാം എന്നതിനെക്കുറിച്ചുള്ള BVB Capital വീഡിയോ ഇവിടെ embed ചെയ്യാം.


    1. ആദ്യം നിങ്ങളുടെ മാസച്ചെലവും Emergency Fund-ഉം വ്യക്തമായി മനസ്സിലാക്കുക

    റിട്ടയർമെന്റിന് ശേഷം ഏറ്റവും പ്രധാനപ്പെട്ട ചോദ്യം:

    “എനിക്ക് ഓരോ മാസവും എത്ര രൂപ വേണം?”

    ഇന്നത്തെ വീട്ടുചെലവ്, മരുന്ന്, insurance, യാത്ര, കുടുംബച്ചെലവ് തുടങ്ങിയവ വേർതിരിച്ച് നോക്കുക.

    ഒരു rough monthly budget ഉണ്ടാക്കുന്നതിലൂടെ retirement-ന് ശേഷം നിങ്ങൾക്ക് എത്ര cash flow ആവശ്യമാണ് എന്ന് മനസ്സിലാക്കാം.

    അതോടൊപ്പം Emergency Fund-നും പ്രാധാന്യം നൽകണം.

    അപ്രതീക്ഷിതമായ medical expense പോലുള്ള കാര്യങ്ങൾ വന്നാൽ retirement corpus-ൽ നിന്ന് ഉടൻ പണം പിൻവലിക്കേണ്ട സാഹചര്യം കുറയ്ക്കാൻ ഒരു separate emergency reserve സഹായിക്കും.

    എത്ര തുക മാറ്റിവെക്കണം എന്നത് എല്ലാവർക്കും ഒരുപോലെയല്ല. നിങ്ങളുടെ monthly expenses, health needs, insurance coverage, മറ്റ് വരുമാന മാർഗങ്ങൾ എന്നിവ നോക്കിയാണ് അത് തീരുമാനിക്കേണ്ടത്.

    പ്രധാനപ്പെട്ട കാര്യം: Emergency money-യുടെ ലക്ഷ്യം return പരമാവധി നേടുക എന്നതല്ല; ആവശ്യസമയത്ത് ലഭ്യമാകുക എന്നതാണ്.


    2. Retirement-ന് മുമ്പ് ബാധ്യതകളും ഉപയോഗമില്ലാത്ത ആസ്തികളും പരിശോധിക്കുക

    Salary നിൽക്കുമ്പോൾ ഒരു EMI കൈകാര്യം ചെയ്യുന്നത് എളുപ്പമായിരിക്കാം.

    പക്ഷേ retirement കഴിഞ്ഞാൽ സ്ഥിരമായ salary ഇല്ലാത്ത സാഹചര്യത്തിൽ അതേ EMI ഒരു വലിയ monthly burden ആകാം.

    അതുകൊണ്ട്:

    • നിലവിലുള്ള home loan, personal loan തുടങ്ങിയ ബാധ്യതകൾ പരിശോധിക്കുക.
    • ഏത് കടം ആദ്യം കുറയ്ക്കണം എന്ന് നോക്കുക.
    • retirement benefits ഉപയോഗിച്ച് loan അടയ്ക്കുന്നതാണോ ശരി എന്ന് നിങ്ങളുടെ മുഴുവൻ financial picture നോക്കി തീരുമാനിക്കുക.
    • ഉപയോഗിക്കാതെ കിടക്കുന്ന assets ഉണ്ടെങ്കിൽ അവയുടെ യഥാർത്ഥ പ്രയോജനം പരിശോധിക്കുക.

    ഇവിടെ ഒരു കാര്യം ശ്രദ്ധിക്കണം.

    “Asset ഉണ്ട്” എന്നത് മാത്രം retirement income ഉണ്ടെന്നർത്ഥമല്ല.

    ഒരു plot അല്ലെങ്കിൽ മറ്റൊരു property കൈവശമുണ്ടാകാം. പക്ഷേ അത് regular cash flow നൽകുന്നില്ലെങ്കിൽ, retirement-ന് ശേഷം മാസച്ചെലവ് എങ്ങനെ നടക്കും എന്ന ചോദ്യം വേറെയാണ്.

    അതുകൊണ്ട് retirement planning-ൽ asset value മാത്രമല്ല, liquidityയും cash flow-ഉം നോക്കണം.


    3. Retirement corpus-ൽ നിന്ന് monthly income എങ്ങനെ എടുക്കണം എന്ന് മുൻകൂട്ടി ആലോചിക്കുക

    Retirement-ന് മുമ്പ് corpus ഉണ്ടാക്കുന്നത് ഒരു ഭാഗം മാത്രമാണ്.

    ആ പണം retirement കഴിഞ്ഞ് എങ്ങനെ ഉപയോഗിക്കും? എന്നതാണ് അടുത്ത ചോദ്യം.

    ഇവിടെയാണ് SWP — Systematic Withdrawal Plan പോലുള്ള ആശയം വരുന്നത്.

    SWP എന്നത് mutual fund investment-ൽ നിന്ന് നിശ്ചിത ഇടവേളകളിൽ, ഉദാഹരണത്തിന് മാസംതോറും, ഒരു നിശ്ചിത തുക പിൻവലിക്കുന്ന രീതിയാണ്.

    പക്ഷേ SWP-യെ “ശമ്പളം പോലെ ഉറപ്പായ വരുമാനം” എന്ന് കാണരുത്.

    Mutual Fund investments market-linked ആണ്. അതിനാൽ investment value ഉയരാനും താഴാനും കഴിയും. Withdrawal amount, withdrawal rate, market performance, corpus size, asset allocation എന്നിവയെല്ലാം retirement cash flow-നെ ബാധിക്കാം.

    അതുകൊണ്ട് retirement income planning ചെയ്യുമ്പോൾ ഒരു single product നോക്കുന്നതിന് പകരം:

    • എത്ര corpus ഉണ്ട്?
    • ഓരോ മാസവും എത്ര വേണം?
    • മറ്റ് pension/income ഉണ്ടോ?
    • എത്രകാലത്തേക്ക് ഈ corpus ഉപയോഗിക്കണം?
    • Market risk എത്രത്തോളം സ്വീകരിക്കാനാകും?
    • Asset Allocation എങ്ങനെ വേണം?

    എന്നിവ കൂടി നോക്കണം.

    Asset Allocation എന്നത് പണം മുഴുവൻ ഒരേ തരത്തിലുള്ള investment-ൽ ഇടാതെ, നിങ്ങളുടെ goal, time horizon, risk എന്നിവ അനുസരിച്ച് വിവിധ asset classes-ലായി ക്രമീകരിക്കുന്ന രീതിയാണ്.


    4. Health Insurance-ഉം കുടുംബത്തിന്റെ monthly budget-ഉം മറക്കരുത്

    Retirement planning എന്ന് പറയുമ്പോൾ പലരും corpus-നെക്കുറിച്ച് മാത്രം ചിന്തിക്കും.

    പക്ഷേ retirement ജീവിതത്തിൽ health-related expenses വളരെ പ്രധാനപ്പെട്ട ഒരു planning area ആണ്.

    ജോലി ചെയ്തിരുന്ന സമയത്ത് employer നൽകിയ group health insurance ഉണ്ടെങ്കിൽ, retirement കഴിഞ്ഞാൽ അതിന്റെ സ്ഥിതി എന്തായിരിക്കും എന്ന് മുൻകൂട്ടി പരിശോധിക്കുക.

    സ്വന്തമായി health insurance ആവശ്യമായിരിക്കുമോ?

    Medical expenses-നായി separate corpus വേണമോ?

    ഇവ retirement-ന് മുമ്പ് തന്നെ പരിശോധിക്കേണ്ട കാര്യങ്ങളാണ്.

    അതോടൊപ്പം കുടുംബാംഗങ്ങളുമായി monthly budget തുറന്ന് സംസാരിക്കുന്നതും പ്രധാനമാണ്.

    Retirement കഴിഞ്ഞുള്ള ജീവിതത്തിൽ:

    • എന്തൊക്കെ ചെലവുകൾ തുടരും?
    • എന്തൊക്കെ ചെലവുകൾ കുറയ്ക്കാം?
    • വലിയ one-time expenses ഉണ്ടോ?
    • കുടുംബത്തിൽ മറ്റാരുടെയെങ്കിലും financial responsibility തുടരുമോ?

    എന്നിവ വ്യക്തമായി മനസ്സിലാക്കുക.


    18 മാസം മാത്രം ബാക്കിയുള്ളപ്പോൾ എന്താണ് ആദ്യം ചെയ്യേണ്ടത്?

    എല്ലാം ഒരുമിച്ച് മാറ്റാൻ ശ്രമിക്കേണ്ടതില്ല.

    ഈ ക്രമത്തിൽ തുടങ്ങാം:

    1. നിങ്ങളുടെ monthly retirement expense എഴുതിവയ്ക്കുക

    ഇന്നത്തെ ചെലവും retirement-ന് ശേഷം പ്രതീക്ഷിക്കുന്ന ചെലവും വേർതിരിക്കുക.

    2. Emergency reserve പരിശോധിക്കുക

    അപ്രതീക്ഷിത ചെലവുകൾക്കായി എത്ര liquid money വേണമെന്ന് മനസ്സിലാക്കുക.

    3. എല്ലാ liabilities-ഉം list ചെയ്യുക

    Loan, EMI, മറ്റ് ബാധ്യതകൾ എന്നിവയുടെ നിലവിലെ സ്ഥിതി പരിശോധിക്കുക.

    4. Existing assets-ന്റെ യഥാർത്ഥ ഉപയോഗം പരിശോധിക്കുക

    “എത്ര രൂപയുടെ asset ഉണ്ട്?” എന്നതോടൊപ്പം “ഇത് retirement cash flow-ന് എങ്ങനെ സഹായിക്കും?” എന്നും ചോദിക്കുക.

    5. Retirement income strategy ആലോചിക്കുക

    Pension, other income, corpus, SWP പോലുള്ള withdrawal approaches എന്നിവ ഒരുമിച്ച് പരിഗണിക്കുക.

    6. Health-related financial risk പരിശോധിക്കുക

    Insurance coverage-ഉം medical reserve-ഉം review ചെയ്യുക.


    ഒരു പ്രധാന കാര്യം: 18 മാസം എന്നത് ഒരു “investment deadline” അല്ല

    റിട്ടയർമെന്റിന് ഇനി 18 മാസം മാത്രം ബാക്കിയുണ്ട് എന്നതുകൊണ്ട് കൂടുതൽ return കിട്ടാൻ വേണ്ടി കൂടുതൽ risk എടുക്കണം എന്നില്ല.

    മറിച്ച്, retirement date അടുത്തുവരുമ്പോൾ നിങ്ങളുടെ പണത്തിന്റെ ലക്ഷ്യം, liquidity, risk, withdrawal need എന്നിവ കൂടുതൽ വ്യക്തമായി നോക്കേണ്ട സമയമാണ്.

    അതുകൊണ്ട് ചോദ്യം:

    “ഇനി 18 മാസത്തിൽ എങ്ങനെ കൂടുതൽ return ഉണ്ടാക്കാം?”

    എന്നതിലുപരി,

    “എന്റെ retirement-ന് ശേഷം പണം എങ്ങനെ ക്രമമായി ഉപയോഗിക്കാം?”

    എന്നതായിരിക്കണം.


    റിട്ടയർമെന്റിന് മുമ്പ് ഒഴിവാക്കേണ്ട 3 സാധാരണ പിഴവുകൾ

    1. ഇന്നത്തെ ചെലവ് മാത്രം നോക്കുന്നത്

    Retirement കഴിഞ്ഞും ചില ചെലവുകൾ തുടരും. അതിനാൽ ഇന്നത്തെ budget മാത്രം നോക്കി retirement income തീരുമാനിക്കരുത്.

    2. എല്ലാ പണവും ഒരേ രീതിയിൽ വയ്ക്കുന്നത്

    Liquidity, growth, income, risk — ഇവയുടെ ആവശ്യങ്ങൾ ഒരുപോലെയല്ല.

    3. Corpus ഉണ്ടാക്കിയാൽ planning കഴിഞ്ഞു എന്ന് കരുതുന്നത്

    Corpus ഉണ്ടാക്കുന്നത് accumulation stage ആണ്.

    Retirement കഴിഞ്ഞ് ആ corpus എങ്ങനെ ഉപയോഗിക്കണം എന്നത് വേറൊരു planning stage ആണ്.


    Retirement planning-ന്റെ ലളിതമായ framework

    ഇത് നാല് ചോദ്യങ്ങളായി ഓർക്കാം:

    എനിക്ക് എത്ര ചെലവ് വേണം?
    ↓
    എനിക്ക് ഇപ്പോൾ എന്തൊക്കെ assets ഉണ്ട്?
    ↓
    എന്തൊക്കെ liabilities ഉണ്ട്?
    ↓
    Retirement കഴിഞ്ഞ് monthly cash flow എങ്ങനെ manage ചെയ്യും?

    ഈ നാല് കാര്യങ്ങൾ വ്യക്തമായാൽ മാത്രമേ നിങ്ങളുടെ retirement plan-ന്റെ ചിത്രം കൂടുതൽ വ്യക്തമാകൂ.


    Frequently Asked Questions

    Retirement-ന് 18 മാസം മാത്രം ബാക്കിയുണ്ടെങ്കിൽ ഇപ്പോഴും planning ചെയ്യാമോ?

    തീർച്ചയായും planning ചെയ്യുന്നത് പ്രയോജനകരമാണ്. പക്ഷേ കുറഞ്ഞ സമയത്ത് എടുത്ത തീരുമാനങ്ങൾ നിങ്ങളുടെ മുഴുവൻ financial situation നോക്കിയാണ് എടുക്കേണ്ടത്. വലിയ risk എടുത്ത് സമയം കുറവ് “പൂരിപ്പിക്കാൻ” ശ്രമിക്കുന്നത് ശരിയായ സമീപനമല്ല.

    SWP retirement monthly income-ന് ഉപയോഗിക്കാമോ?

    SWP ഒരു mutual fund investment-ൽ നിന്ന് നിശ്ചിത ഇടവേളകളിൽ പണം പിൻവലിക്കുന്ന രീതിയാണ്. Retirement cash flow planning-ൽ ഇത് പരിഗണിക്കാവുന്ന ഒരു approach ആയേക്കാം. എന്നാൽ market risk ഉള്ളതിനാൽ SWP-യെ guaranteed monthly income ആയി കാണരുത്.

    Retirement-ന് മുമ്പ് loan തീർക്കണോ?

    എല്ലാവർക്കും ഒരേ ഉത്തരം ഇല്ല. Loan interest, outstanding amount, retirement income, available assets, liquidity തുടങ്ങിയ കാര്യങ്ങൾ നോക്കിയാണ് തീരുമാനം എടുക്കേണ്ടത്.

    Emergency Fund retirement planning-ൽ എന്തുകൊണ്ട് പ്രധാനമാണ്?

    അപ്രതീക്ഷിത ചെലവുകൾ വന്നപ്പോൾ retirement investments ഉടൻ liquidate ചെയ്യേണ്ട സാഹചര്യം കുറയ്ക്കാൻ ഒരു separate emergency reserve സഹായിക്കും.

    Retirement planning-ൽ Health Insurance എന്തുകൊണ്ട് പ്രധാനമാണ്?

    Medical expenses retirement cash flow-നെ ബാധിക്കാം. അതുകൊണ്ട് നിലവിലുള്ള health insurance coverage retirement കഴിഞ്ഞും എങ്ങനെ തുടരും എന്ന് മുൻകൂട്ടി പരിശോധിക്കുന്നത് പ്രധാനമാണ്.


    ഇനി വായിക്കാം

    Retirement planning ഒരു single investment തിരഞ്ഞെടുക്കുന്നതിന്റെ കാര്യമല്ല. Goal, time horizon, risk, portfolio, cash flow എന്നിവ തമ്മിൽ ബന്ധിപ്പിച്ചാണ് നോക്കേണ്ടത്.

    BVB Capital-ന്റെ verified website resources-ൽ നിന്ന് തുടർന്നു വായിക്കാം:

    • BVB Capital Blog — Mutual Fund, SIP, investment planning തുടങ്ങിയ വിഷയങ്ങളിലെ കൂടുതൽ ലേഖനങ്ങൾ.
    • Investor Awareness & Behaviour articles — investor behaviour, common mistakes, portfolio-related awareness topics.

    Retirement Calculator, SWP guide, Emergency Fund guide എന്നിവയുടെ exact URLs ഈ draft-ിൽ നൽകിയ placeholders വഴി മാത്രം സൂചിപ്പിച്ചിരിക്കുന്നതിനാൽ, sitemap-ൽ നിന്ന് URL verify ചെയ്ത ശേഷം മാത്രമേ അവ ചേർക്കാവൂ. URL ഊഹിച്ച് ചേർക്കരുത്.


    നിങ്ങളുടെ Retirement Plan എവിടെയാണ് നിൽക്കുന്നത്?

    “എനിക്ക് എത്ര corpus വേണം?” എന്നതിൽ മാത്രം retirement planning അവസാനിക്കുന്നില്ല.

    നിങ്ങളുടെ:

    • monthly expenses
    • existing assets
    • liabilities
    • pension/other income
    • health-related needs
    • retirement timeline
    • investment risk

    എന്നിവ ഒരുമിച്ച് നോക്കണം.

    നിങ്ങളുടെ retirement planning എവിടെയാണ് നിൽക്കുന്നത് എന്ന് കൂടുതൽ വ്യക്തമായി മനസ്സിലാക്കാൻ സഹായം വേണമെങ്കിൽ BVB Capital-നോട് ഒരു discussion നടത്താം.

    BVB Capital Private Limited
    AMFI Registered Mutual Fund Distributor
    ARN 348338
    WhatsApp: +91 96339 40008
    BVB Capital Website
    Contact BVB Capital

    ഇത് ഒരു പ്രത്യേക mutual fund scheme-ന്റെ recommendation അല്ല. നിങ്ങളുടെ സ്വന്തം financial situation, goals, time horizon, risk profile എന്നിവ പരിഗണിച്ചാണ് ഏതൊരു investment decision-ഉം എടുക്കേണ്ടത്.

    Mutual Fund investments are subject to market risks, read all scheme related documents carefully before investing.
  • റിട്ടയർമെന്റ് പ്ലാനിംഗ്: എഫ്.ഡി മാത്രം മതിയോ?

    റിട്ടയർമെന്റ് പ്ലാനിംഗ്: എഫ്.ഡി മാത്രം മതിയോ?

    വിരമിച്ച ശേഷം ജീവിതച്ചെലവുകൾക്കായി നിങ്ങൾക്ക് ₹50 ലക്ഷം, ₹1 കോടി, അതിലധികം രൂപ ആവശ്യമാകുമെന്ന് കരുതാം. ആ തുക മുഴുവൻ ബാങ്ക് എഫ്.ഡിയിൽ വച്ചാൽ മതിയോ?

    ഒറ്റവാക്കിൽ പറഞ്ഞാൽ: എഫ്.ഡി ഒരു നിക്ഷേപ മാർഗമാണ്. പക്ഷേ, ഒരു വലിയ റിട്ടയർമെന്റ് ലക്ഷ്യത്തിന് മുഴുവൻ പണവും ഒരേ നിക്ഷേപത്തിൽ മാത്രം വയ്ക്കുന്നതിന് മുമ്പ് പണപ്പെരുപ്പം, നിങ്ങളുടെ ലക്ഷ്യം, സമയപരിധി, വരുമാന ആവശ്യം എന്നിവ കൂടി നോക്കണം.

    ഇവിടെയാണ് റിട്ടയർമെന്റ് പ്ലാനിംഗ് പ്രധാനമാകുന്നത്.

    റിട്ടയർമെന്റിനായി നിക്ഷേപം ക്രമീകരിക്കുമ്പോൾ ലക്ഷ്യം “എവിടെ പണം വയ്ക്കണം?” എന്നത് മാത്രമല്ല. ഇന്നത്തെ പണത്തിന്റെ മൂല്യം ഭാവിയിൽ എത്രയായിരിക്കും, വിരമിച്ച ശേഷം മാസം എത്ര പണം ആവശ്യമായി വരും, ആ ആവശ്യത്തിന് നിക്ഷേപങ്ങൾ എങ്ങനെ ക്രമീകരിക്കണം എന്നതും നോക്കണം.

    🎥 ഈ വിഷയം വീഡിയോയായി കാണാം

    BVB Capital YouTube വീഡിയോ:


    എഫ്.ഡി മാത്രം ആശ്രയിച്ചുള്ള റിട്ടയർമെന്റ് പ്ലാനിംഗിൽ എന്താണ് ശ്രദ്ധിക്കേണ്ടത്?

    കേരളത്തിലെ പല നിക്ഷേപകർക്കും ബാങ്ക് എഫ്.ഡി പരിചിതമായ ഒരു നിക്ഷേപ മാർഗമാണ്. പണം ഒരു നിശ്ചിത കാലത്തേക്ക് നിക്ഷേപിച്ച് പലിശ ലഭിക്കുന്ന രീതി എന്ന നിലയിൽ അത് മനസ്സിലാക്കാനും എളുപ്പമാണ്.

    പക്ഷേ റിട്ടയർമെന്റ് പ്ലാനിംഗ് കുറച്ച് വ്യത്യസ്തമായ കാര്യമാണ്.

    നിങ്ങളുടെ പണം ഇന്ന് ₹50 ലക്ഷം ആണെന്ന് കരുതുക. 10–20 വർഷങ്ങൾക്ക് ശേഷം അതേ ₹50 ലക്ഷം കൊണ്ട് ഇന്നത്തെ പോലെ തന്നെ സാധനങ്ങളും സേവനങ്ങളും വാങ്ങാൻ കഴിയുമോ?

    ഇവിടെയാണ് പണപ്പെരുപ്പം — Inflation — ശ്രദ്ധിക്കേണ്ടത്.

    പണപ്പെരുപ്പം എന്താണ്?

    സമയം കഴിയുമ്പോൾ സാധനങ്ങളുടെയും സേവനങ്ങളുടെയും വില ഉയരുന്നതാണ് പണപ്പെരുപ്പം.

    ഉദാഹരണത്തിന്, ഇന്ന് ഒരു കുടുംബത്തിന് മാസം ₹50,000 ചെലവാകുന്നുണ്ടെന്ന് കരുതാം. വർഷങ്ങൾ കഴിഞ്ഞ് അതേ ജീവിതശൈലി നിലനിർത്താൻ കൂടുതൽ തുക ആവശ്യമായി വരാം.

    അതുകൊണ്ട് റിട്ടയർമെന്റിന് വേണ്ട corpus കണക്കാക്കുമ്പോൾ ഇന്നത്തെ ചെലവ് മാത്രം നോക്കുന്നത് മതിയാകില്ല.

    റിട്ടയർമെന്റ് പ്ലാനിംഗിൽ ഇന്നത്തെ ആവശ്യവും ഭാവിയിലെ ചെലവും തമ്മിലുള്ള വ്യത്യാസം മനസ്സിലാക്കുകയാണ് പ്രധാനപ്പെട്ട ഒരു ഘട്ടം.


    എഫ്.ഡി മോശമാണോ?

    അല്ല.

    ഇവിടെ പറയുന്നത് എഫ്.ഡി വേണ്ട എന്നല്ല.

    പ്രധാന ചോദ്യം ഇതാണ്:

    “എന്റെ റിട്ടയർമെന്റ് പണത്തിന്റെ മുഴുവൻ ഭാഗവും ഒരേ നിക്ഷേപ മാർഗത്തിൽ മാത്രം വയ്ക്കുന്നത് എന്റെ ലക്ഷ്യത്തിന് അനുയോജ്യമാണോ?”

    എഫ്.ഡിക്ക് പല നിക്ഷേപകരും പ്രാധാന്യം നൽകുന്നത് മനസ്സിലാക്കാവുന്നതാണ്. എന്നാൽ ദീർഘകാല റിട്ടയർമെന്റ് ലക്ഷ്യത്തിൽ inflation-നെ മറികടക്കാനുള്ള വളർച്ചയും, വിരമിച്ച ശേഷം ആവശ്യമായ cash flow-യും പരിഗണിക്കേണ്ടതുണ്ട്.

    അതുകൊണ്ടാണ് Asset Allocation പ്രധാനമാകുന്നത്.


    നിക്ഷേപങ്ങൾ എന്തിന് Split ചെയ്യണം?

    Asset Allocation എന്നത് നിങ്ങളുടെ പണം മുഴുവൻ ഒരേ തരത്തിലുള്ള നിക്ഷേപത്തിൽ ഇടാതെ, നിങ്ങളുടെ ലക്ഷ്യം, സമയപരിധി, risk എന്നിവ കണക്കിലെടുത്ത് വിവിധ asset classes-ലായി ക്രമീകരിക്കുന്ന രീതിയാണ്.

    ഒരു retirement portfolio-യിൽ, സാഹചര്യത്തിനനുസരിച്ച് വ്യത്യസ്ത തരത്തിലുള്ള നിക്ഷേപങ്ങൾ പരിഗണിക്കാം.

    ഉദാഹരണത്തിന്:

    • അടിയന്തര ആവശ്യങ്ങൾക്ക് എളുപ്പത്തിൽ ലഭ്യമാകുന്ന പണം വേർതിരിച്ച് വയ്ക്കാം.
    • ദീർഘകാല വളർച്ച ലക്ഷ്യമിടുന്ന ഭാഗത്ത് Mutual Fund പോലുള്ള market-linked investments പരിഗണിക്കാം.
    • സ്ഥിരത ആവശ്യമായ ഭാഗത്ത് അനുയോജ്യമായ fixed-income options പരിഗണിക്കാം.

    ഇതിന്റെ ഉദ്ദേശ്യം “കൂടുതൽ return ഉറപ്പാക്കുക” എന്നതല്ല.

    നിങ്ങളുടെ പണത്തിന് വ്യത്യസ്ത ജോലികൾ നൽകുക എന്നതാണ്.

    റിട്ടയർമെന്റിന് ഇനിയും ഏറെ വർഷങ്ങൾ ബാക്കിയുള്ള ഒരാളുടെയും വിരമിക്കാനിരിക്കുന്ന ഒരാളുടെയും portfolio ഒരുപോലെയാകണമെന്നില്ല.

    അതുകൊണ്ട് “എത്ര പണം എവിടെ?” എന്ന ചോദ്യത്തിന് എല്ലാവർക്കും ഒരേ answer ഉണ്ടാകില്ല.


    റിട്ടയർമെന്റിനായി Mutual Fund പരിഗണിക്കാമോ?

    ദീർഘകാല ലക്ഷ്യങ്ങൾക്ക് ചില നിക്ഷേപകർ Mutual Fund പരിഗണിക്കാറുണ്ട്. എന്നാൽ Mutual Fund-ുകളിൽ market risk ഉണ്ടെന്ന കാര്യം മറക്കരുത്.

    Market movements കാരണം നിക്ഷേപത്തിന്റെ value ഉയരാനും താഴാനും കഴിയും.

    അതുകൊണ്ട് Retirement planning ചെയ്യുമ്പോൾ:

    • നിങ്ങളുടെ retirement age
    • ഇപ്പോഴത്തെ ചെലവ്
    • ഭാവിയിലെ പ്രതീക്ഷിക്കുന്ന ചെലവ്
    • എത്ര വർഷം നിക്ഷേപിക്കാനുണ്ട്
    • risk എത്രത്തോളം സ്വീകരിക്കാം
    • ഇതിനകം ഉള്ള investments
    • retirement കഴിഞ്ഞുള്ള വരുമാന ആവശ്യം

    എന്നിവ ഒരുമിച്ച് നോക്കുന്നതാണ് കൂടുതൽ പ്രായോഗികം.

    Mutual Fund ഒരു retirement plan അല്ല. നിങ്ങളുടെ retirement goal-നോട് ബന്ധിപ്പിച്ച് ഉപയോഗിക്കുന്ന ഒരു investment tool ആയി മാത്രമാണ് അതിനെ കാണേണ്ടത്.


    Retirement കഴിഞ്ഞാൽ മാസവരുമാനം എങ്ങനെ ക്രമീകരിക്കാം?

    ഇവിടെയാണ് SWP — Systematic Withdrawal Plan എന്ന ആശയം പ്രസക്തമാകുന്നത്.

    SWP എന്നത് Mutual Fund investment-ൽ നിന്ന് ഒരു നിശ്ചിത ഇടവേളയിൽ, ഉദാഹരണത്തിന് മാസത്തിൽ ഒരിക്കൽ, ഒരു നിശ്ചിത തുക പിൻവലിക്കുന്ന രീതിയാണ്.

    ഉദാഹരണത്തിന്, retirement corpus ഉണ്ടാക്കിയ ശേഷം മാസം ₹40,000 പിൻവലിക്കണമെന്നാണ് നിങ്ങളുടെ plan എന്ന് കരുതാം.

    SWP ഉപയോഗിക്കുമ്പോൾ, ആവശ്യമായ തുക നിശ്ചിത ഇടവേളകളിൽ പിൻവലിക്കാനുള്ള സംവിധാനം ക്രമീകരിക്കാം.

    പക്ഷേ ഇവിടെ ഒരു പ്രധാന കാര്യം ശ്രദ്ധിക്കണം:

    SWP എന്നത് guaranteed monthly income അല്ല.

    Market performance, withdrawal amount, withdrawal period തുടങ്ങിയ കാര്യങ്ങൾ corpus-നെ ബാധിക്കാം. സ്ഥിരമായി പിൻവലിക്കുമ്പോൾ investment units redeem ചെയ്യപ്പെടുന്നതിനാൽ corpus-ലും മാറ്റമുണ്ടാകാം.

    അതുകൊണ്ട് SWP തീരുമാനിക്കുമ്പോൾ “മാസം എത്ര പിൻവലിക്കാം?” എന്നത് മാത്രം നോക്കാതെ എത്ര corpus ഉണ്ട്, എത്ര കാലത്തേക്ക് income വേണം, market risk എങ്ങനെ കൈകാര്യം ചെയ്യണം എന്നതും നോക്കണം.


    ഒരു ലളിതമായ Retirement Planning ഉദാഹരണം

    നിങ്ങൾ 45 വയസ്സിലാണ് എന്നും 60 വയസ്സിൽ വിരമിക്കാനാണ് ഉദ്ദേശിക്കുന്നതെന്നും കരുതാം.

    ഇപ്പോൾ നിങ്ങളുടെ കുടുംബത്തിന്റെ മാസച്ചെലവ് ₹60,000 ആണെങ്കിൽ, 15 വർഷത്തിന് ശേഷം അതേ ജീവിതശൈലിക്ക് ആവശ്യമായ ചെലവ് ഇതേ ₹60,000 ആയിരിക്കണമെന്നില്ല.

    ഇവിടെയാണ് inflation കണക്കിലെടുക്കേണ്ടത്.

    അതിന് ശേഷം അടുത്ത ചോദ്യങ്ങൾ വരും:

    60-ാം വയസ്സിൽ എത്ര corpus വേണം?

    ആ corpus എങ്ങനെ നിർമ്മിക്കണം?

    Retirement കഴിഞ്ഞാൽ മാസം എത്ര തുക ആവശ്യമായി വരും?

    ആ വരുമാനം എങ്ങനെ ക്രമീകരിക്കാം?

    ഇവയ്ക്ക് ഒരു പൊതുവായ തുക പറഞ്ഞ് എല്ലാവർക്കും ഒരേ retirement plan നൽകാൻ കഴിയില്ല.

    നിങ്ങളുടെ നിലവിലെ savings, investments, income, expenses, retirement age, goals എന്നിവ കൂടി നോക്കിയാണ് planning നടത്തേണ്ടത്.


    Retirement Planning-ൽ പലരും ശ്രദ്ധിക്കാതെ പോകുന്ന ഒരു കാര്യം

    പലരും retirement planning തുടങ്ങുമ്പോൾ ആദ്യം ചോദിക്കുന്നത്:

    “എത്ര return കിട്ടും?”

    പക്ഷേ അതിന് മുമ്പ് ചോദിക്കേണ്ട ചില ചോദ്യങ്ങളുണ്ട്:

    1. എനിക്ക് എപ്പോൾ വിരമിക്കണം?
    2. വിരമിച്ച ശേഷം മാസം എത്ര ചെലവ് വരും?
    3. ഇന്നത്തെ ചെലവ് ഭാവിയിൽ എങ്ങനെ മാറാം?
    4. ഇപ്പോൾ എനിക്ക് എന്തെല്ലാം investments ഉണ്ട്?
    5. Retirement വരെ എത്ര വർഷം ബാക്കിയുണ്ട്?
    6. Retirement കഴിഞ്ഞാൽ income എവിടെ നിന്ന് വരും?

    ഇവയ്ക്ക് clarity വന്നതിന് ശേഷമാണ് investment allocation ചർച്ച ചെയ്യുന്നത് കൂടുതൽ അർത്ഥവത്താകുന്നത്.


    “എല്ലാം FD-യിൽ” അല്ലെങ്കിൽ “എല്ലാം Mutual Fund-ൽ” — രണ്ടും ആവശ്യമില്ല

    Retirement planning-ന്റെ ലക്ഷ്യം ഒരു investment product തിരഞ്ഞെടുക്കുക എന്നതല്ല.

    ലക്ഷ്യത്തിന് അനുയോജ്യമായ ഒരു structure ഉണ്ടാക്കുക എന്നതാണ്.

    ഒരു ഭാഗം liquidity-ക്ക് ആവശ്യമായേക്കാം.

    ഒരു ഭാഗം സ്ഥിരതയ്ക്കായി ആവശ്യമാകാം.

    ഒരു ഭാഗം ദീർഘകാല വളർച്ച ലക്ഷ്യമിടുന്ന investments-ൽ ആയിരിക്കാം.

    എത്ര ശതമാനം എവിടെ വേണം എന്നത് വ്യക്തിയുടെ സാഹചര്യം അനുസരിച്ച് മാറും.

    അതുകൊണ്ട് “എഫ്.ഡി നല്ലതാണോ, Mutual Fund നല്ലതാണോ?” എന്നതിനെക്കാൾ പ്രായോഗികമായ ചോദ്യം:

    “എന്റെ retirement goal-ന് ഈ investments എങ്ങനെ ക്രമീകരിക്കണം?”

    എന്നതാണ്.


    Retirement Planning വൈകിക്കാതെ തുടങ്ങുന്നത് എന്തുകൊണ്ട് പ്രധാനമാണ്?

    Retirement ഒരു ഒറ്റ ദിവസത്തെ financial decision അല്ല.

    Accumulation phase-ൽ നിക്ഷേപം നിർമ്മിക്കുക, പിന്നീട് retirement-ൽ ആ corpus എങ്ങനെ ഉപയോഗിക്കണം എന്ന് ആലോചിക്കുക — രണ്ടും വേർതിരിച്ച് കാണണം.

    Retirement അടുത്തെത്തുമ്പോൾ മാത്രം planning തുടങ്ങുന്നത് options കുറയ്ക്കാം.

    അതുകൊണ്ട് retirement ഇനിയും വർഷങ്ങൾ അകലെയാണെങ്കിലും, ഇപ്പോഴത്തെ investments നിങ്ങളുടെ retirement goal-നോട് എങ്ങനെ ബന്ധപ്പെട്ടിരിക്കുന്നു എന്ന് ഇടയ്ക്കിടെ പരിശോധിക്കുന്നത് പ്രയോജനകരമാണ്.


    റിട്ടയർമെന്റ് പ്ലാനിംഗിൽ ഓർക്കേണ്ട 5 കാര്യങ്ങൾ

    1. എഫ്.ഡി മാത്രം മതിയെന്ന് മുൻകൂട്ടി തീരുമാനിക്കേണ്ടതില്ല.
    നിങ്ങളുടെ ലക്ഷ്യം, സമയപരിധി, inflation എന്നിവയും നോക്കുക.

    2. പണപ്പെരുപ്പം കണക്കിലെടുക്കുക.
    ഇന്നത്തെ ₹50,000 ചെലവ് ഭാവിയിലും ₹50,000 ആയിരിക്കണമെന്നില്ല.

    3. Investments-ന് വ്യത്യസ്ത roles നൽകുക.
    Liquidity, stability, long-term growth എന്നിവ പ്രത്യേകം പരിഗണിക്കാം.

    4. SWP-യെ guaranteed income ആയി കാണരുത്.
    ഇത് ഒരു systematic withdrawal mechanism ആണ്; corpus-ലും market value-ലും മാറ്റം സംഭവിക്കാം.

    5. Retirement planning return മാത്രം നോക്കുന്ന കാര്യമല്ല.
    Corpus, expenses, time horizon, risk, withdrawal needs എന്നിവ ഒരുമിച്ച് നോക്കണം.


    Retirement Planning തുടങ്ങാൻ ഒരു ലളിതമായ വഴി

    നിങ്ങൾക്ക് ഇപ്പോൾ വലിയ കണക്കുകളൊന്നും ചെയ്യാൻ കഴിയുന്നില്ലെങ്കിൽ, ആദ്യം ഈ നാല് കാര്യങ്ങൾ കുറിച്ചുവയ്ക്കാം:

    നിലവിലെ പ്രായം → വിരമിക്കാൻ ഉദ്ദേശിക്കുന്ന പ്രായം → ഇപ്പോഴത്തെ മാസച്ചെലവ് → നിലവിലുള്ള investments

    ഇവയിൽ നിന്ന് retirement goal-നെക്കുറിച്ച് കൂടുതൽ വ്യക്തമായി ചിന്തിക്കാൻ തുടങ്ങാം.

    ഒരു നല്ല retirement plan എന്നത് ഒരിക്കൽ തയ്യാറാക്കി മറക്കുന്ന ഒന്നല്ല. ജീവിതസാഹചര്യങ്ങളും income-ഉം expenses-ഉം മാറുമ്പോൾ അത് review ചെയ്യേണ്ടി വരാം.


    Frequently Asked Questions

    എഫ്.ഡി മാത്രം ഉപയോഗിച്ച് retirement planning ചെയ്യാമോ?

    ചെയ്യാം എന്നോ ചെയ്യരുത് എന്നോ എല്ലാവർക്കും ഒരേ ഉത്തരമില്ല. നിങ്ങളുടെ retirement goal, inflation, time horizon, income needs, risk tolerance എന്നിവ പരിഗണിച്ചാണ് തീരുമാനിക്കേണ്ടത്. വലിയ retirement corpus മുഴുവൻ ഒരേ investment type-ൽ വയ്ക്കുന്നതിന് മുമ്പ് diversification കൂടി പരിശോധിക്കുന്നത് പ്രധാനമാണ്.

    Retirement planning-ൽ inflation എന്തുകൊണ്ട് പ്രധാനമാണ്?

    കാലക്രമത്തിൽ സാധനങ്ങളുടെയും സേവനങ്ങളുടെയും വില മാറുന്നതിനാൽ, ഭാവിയിലെ retirement expenses ഇന്നത്തേതിനേക്കാൾ കൂടുതലാകാം. അതിനാൽ corpus കണക്കാക്കുമ്പോൾ inflation പരിഗണിക്കണം.

    SWP എന്താണ്?

    SWP അഥവാ Systematic Withdrawal Plan എന്നത് Mutual Fund investment-ൽ നിന്ന് നിശ്ചിത ഇടവേളകളിൽ ഒരു നിശ്ചിത തുക പിൻവലിക്കുന്ന രീതിയാണ്. ഇത് guaranteed income അല്ല.

    SWP വഴി മാസംതോറും income എടുക്കാമോ?

    ഒരു നിശ്ചിത withdrawal amount ക്രമീകരിക്കാൻ SWP ഉപയോഗിക്കാം. എന്നാൽ അത് guaranteed income അല്ല. Market performance, withdrawal amount, investment corpus എന്നിവ withdrawal plan-ന്റെ sustainability-യെ ബാധിക്കും.

    Retirement-ന് എത്ര corpus വേണം?

    എല്ലാവർക്കും ഒരേ corpus ആവശ്യമില്ല. ഇപ്പോഴത്തെ ചെലവ്, retirement age, retirement കഴിഞ്ഞുള്ള ജീവിതശൈലി, inflation, മറ്റ് income sources, existing investments തുടങ്ങിയവ പരിഗണിച്ചാണ് ഇത് കണക്കാക്കേണ്ടത്.

    Retirement planning എപ്പോൾ തുടങ്ങണം?

    Retirement അടുത്തെത്തിയ ശേഷം മാത്രം തുടങ്ങേണ്ട കാര്യമല്ല. Retirement വരെ കൂടുതൽ സമയം ഉണ്ടെങ്കിൽ goal, savings, investments എന്നിവ നേരത്തെ ക്രമീകരിച്ച് ഇടയ്ക്കിടെ review ചെയ്യാം.


    ഇനി വായിക്കാം

    Retirement planning മനസ്സിലാക്കുമ്പോൾ അടുത്തതായി നിങ്ങളുടെ investment basics കൂടി വ്യക്തമായിരിക്കണം.


    അവസാനമായി

    റിട്ടയർമെന്റിനെക്കുറിച്ച് ചിന്തിക്കുമ്പോൾ പേടിക്കേണ്ടതില്ല. അതുപോലെ “എഫ്.ഡി മാത്രം മതി” അല്ലെങ്കിൽ “Mutual Fund-ൽ എല്ലാം നിക്ഷേപിക്കണം” എന്ന രീതിയിൽ ഒരു പൊതുവായ ഉത്തരവും തേടേണ്ടതില്ല.

    ആദ്യം നിങ്ങളുടെ retirement goal മനസ്സിലാക്കുക.

    പിന്നെ ഭാവിയിലെ ചെലവ്, inflation, നിലവിലുള്ള investments, risk, retirement കഴിഞ്ഞുള്ള income ആവശ്യം എന്നിവ നോക്കുക.

    അതിനുശേഷമാണ് investments എങ്ങനെ ക്രമീകരിക്കണമെന്ന് ചിന്തിക്കേണ്ടത്.

    നിങ്ങളുടെ retirement goal-ന് എത്ര corpus ആവശ്യമാകാം, ഇപ്പോഴുള്ള investments അതിനോട് എങ്ങനെ match ചെയ്യുന്നു, retirement കഴിഞ്ഞുള്ള cash flow എങ്ങനെ ആസൂത്രണം ചെയ്യാം തുടങ്ങിയ കാര്യങ്ങളിൽ കൂടുതൽ clarity വേണമെങ്കിൽ BVB Capital-നോട് സംസാരിക്കാം.

    BVB Capital Private Limited
    AMFI Registered Mutual Fund Distributor
    ARN 348338
    WhatsApp: +91 96339 40008
    Website: https://bvbcap.com

    Mutual Fund investments are subject to market risks, read all scheme related documents carefully before investing.
  • മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപം പേടിയാണോ? ₹500 SIP മുതൽ എങ്ങനെ തുടങ്ങാം?

    മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപം പേടിയാണോ? ₹500 SIP മുതൽ എങ്ങനെ തുടങ്ങാം?

    “Market ഇടിഞ്ഞാൽ എന്റെ പണം നഷ്ടപ്പെടുമോ?”

    “Mutual Fund കമ്പനി എന്തെങ്കിലും പ്രശ്നത്തിൽപ്പെട്ടാൽ എന്റെ പണത്തിന് എന്ത് സംഭവിക്കും?”

    “വലിയ തുക ഇല്ലെങ്കിൽ നിക്ഷേപം തുടങ്ങുന്നതിൽ കാര്യമുണ്ടോ?”

    Mutual Fund-ൽ ആദ്യമായി നിക്ഷേപിക്കാൻ ആലോചിക്കുന്ന പലരുടെയും സംശയങ്ങളാണിവ.

    ഇവിടെ പ്രധാനപ്പെട്ട കാര്യം പേടി പൂർണ്ണമായി ഇല്ലാതാക്കുക എന്നതല്ല. പകരം, Mutual Fund എങ്ങനെ പ്രവർത്തിക്കുന്നു, market risk എന്താണ്, പണം എങ്ങനെ നിക്ഷേപിക്കപ്പെടുന്നു, എത്ര തുകയിൽ തുടങ്ങാം എന്നിവ മനസ്സിലാക്കി വിവരമുള്ള ഒരു തുടക്കം എടുക്കുക എന്നതാണ്.

    അതിനായി വലിയ തുക കാത്തിരിക്കേണ്ടതില്ല. നിങ്ങളുടെ സാമ്പത്തിക സാഹചര്യത്തിന് അനുയോജ്യമായ ചെറിയ തുകയിലൂടെ SIP ആരംഭിച്ച്, പിന്നീട് വരുമാനത്തിനനുസരിച്ച് നിക്ഷേപം കൂട്ടുന്ന രീതിയാണ് പരിഗണിക്കാവുന്നത്.

    🎥 ഈ വിഷയം വീഡിയോയായി കാണാം

    വീഡിയോയിൽ പറയുന്ന പ്രധാന ആശയങ്ങൾക്കൊപ്പം, ഈ ലേഖനത്തിൽ SIP എങ്ങനെ തുടങ്ങാം, Step-Up SIP എന്താണ്, payment സുരക്ഷിതമായി എങ്ങനെ നടത്താം തുടങ്ങിയ കാര്യങ്ങൾ കുറച്ചുകൂടി വിശദമായി നോക്കാം.


    ₹500 കൊണ്ട് SIP തുടങ്ങാമോ?

    തുടങ്ങാൻ സാധിക്കുന്ന തുക നിങ്ങളുടെ തിരഞ്ഞെടുക്കുന്ന scheme-ന്റെ applicable minimum investment അനുസരിച്ചായിരിക്കും. ₹500 SIP ലഭ്യമായ schemes ഉണ്ടെങ്കിലും, ₹500 എല്ലാവരുടെയും financial goal-ന് മതിയാകും എന്ന് പറയാനാവില്ല.

    ഇവിടെയാണ് ഒരു ചെറിയ വ്യത്യാസം മനസ്സിലാക്കേണ്ടത്.

    “എത്ര കുറഞ്ഞ തുകയിൽ തുടങ്ങാം?” എന്നത് ഒരു ചോദ്യം.

    “എന്റെ ലക്ഷ്യത്തിന് എത്ര നിക്ഷേപിക്കണം?” എന്നത് മറ്റൊരു ചോദ്യം.

    ആദ്യത്തേതിന് ₹500 പോലുള്ള ചെറിയ SIP ഒരു തുടക്കമാകാം. രണ്ടാമത്തേതിന് നിങ്ങളുടെ goal, time horizon, income, expenses, risk profile എന്നിവ കൂടി നോക്കണം.

    അതുകൊണ്ട് “വലിയ തുക കിട്ടിയാൽ തുടങ്ങാം” എന്ന് കാത്തിരിക്കേണ്ടതില്ല. കഴിയുന്ന തുകയിൽ തുടക്കം കുറിച്ച് പിന്നീട് സ്ഥിതി മെച്ചപ്പെടുമ്പോൾ SIP കൂട്ടുന്നത് ഒരു practical approach ആയേക്കാം.

    BVB Capital-ന്റെ നിലവിലുള്ള investor education content-ലും ₹500 SIP ഒരു തുടക്കമായി പരിഗണിക്കാമെന്ന് വ്യക്തമാക്കുന്നുണ്ട്. എന്നാൽ amount മാത്രം നോക്കാതെ goal-നനുസരിച്ചുള്ള planning ആണ് പ്രധാനപ്പെട്ടത്.


    ചെറിയ തുകയിൽ തുടങ്ങുന്നത് പേടി കുറയ്ക്കാൻ എങ്ങനെ സഹായിക്കും?

    ആദ്യമായി ₹5,000 അല്ലെങ്കിൽ ₹10,000 പോലുള്ള വലിയ തുക നിക്ഷേപിക്കുമ്പോൾ market movement ഓരോ ദിവസവും ശ്രദ്ധിക്കാൻ തുടങ്ങാം.

    Market താഴ്ന്നാൽ:

    “എന്റെ പണം കുറയുകയാണല്ലോ?”

    എന്ന ചിന്ത വരാം.

    പകരം, നിങ്ങളുടെ സാമ്പത്തിക സാഹചര്യത്തിന് യോജിച്ച ചെറിയ തുകയിലൂടെ തുടങ്ങുമ്പോൾ market-ന്റെ സ്വഭാവം മനസ്സിലാക്കാൻ സമയം ലഭിക്കും.

    ഒരു കാര്യം മാത്രം ഓർക്കുക:

    SIP market risk ഇല്ലാതാക്കുന്നില്ല.

    Mutual Fund-ുകളുടെ value market conditions അനുസരിച്ച് ഉയരാനും താഴാനും കഴിയും. അതിനാൽ SIP എന്നത് risk-free investment അല്ല.

    പക്ഷേ, സ്ഥിരമായി നിക്ഷേപിക്കുന്ന രീതി investor-നെ discipline പാലിക്കാൻ സഹായിക്കാം. നിങ്ങളുടെ goal-നും time horizon-നും അനുയോജ്യമായ investment approach തിരഞ്ഞെടുക്കുന്നതാണ് ഇവിടെ പ്രധാനപ്പെട്ടത്.


    SIP എങ്ങനെ തുടങ്ങാം?

    SIP എന്നത് Systematic Investment Plan ആണ്. ഒരു നിശ്ചിത തുക നിശ്ചിത ഇടവേളകളിൽ, സാധാരണയായി മാസത്തിൽ ഒരിക്കൽ, Mutual Fund scheme-ൽ നിക്ഷേപിക്കുന്ന രീതിയാണിത്.

    തുടങ്ങുന്നതിന് മുമ്പ് ഈ കാര്യങ്ങൾ നോക്കാം:

    1. നിങ്ങളുടെ financial goal എന്താണ്?

    Retirement ആണോ?

    കുട്ടികളുടെ വിദ്യാഭ്യാസമാണോ?

    വീട് വാങ്ങാനുള്ള ലക്ഷ്യമാണോ?

    അല്ലെങ്കിൽ ദീർഘകാല wealth creation ആണോ?

    Goal വ്യക്തമാകുമ്പോൾ investment planning കൂടുതൽ structured ആക്കാൻ കഴിയും.

    2. എപ്പോൾ പണം ആവശ്യമാകും?

    ഇതാണ് Time Horizon.

    5 വർഷത്തിനുള്ളിൽ ആവശ്യമുള്ള പണവും 20 വർഷത്തിന് ശേഷം ആവശ്യമുള്ള പണവും ഒരേ രീതിയിൽ plan ചെയ്യേണ്ടതില്ല.

    3. Emergency Fund ഉണ്ടോ?

    അപ്രതീക്ഷിത ചെലവുകൾക്കായി ആവശ്യമായ emergency savings ഇല്ലാതെ മുഴുവൻ available money-യും market-linked investments-ലേക്ക് മാറ്റുന്നത് ഒഴിവാക്കുന്നതാണ് നല്ലത്.

    4. Risk എത്രത്തോളം സ്വീകരിക്കാം?

    Market ഇടിയുമ്പോൾ investment value കുറയുന്നത് കണ്ടാൽ നിങ്ങൾക്ക് എങ്ങനെ പ്രതികരിക്കുമെന്നതും പ്രധാനമാണ്.

    അതുകൊണ്ട് fund തിരഞ്ഞെടുക്കുന്നതിന് മുമ്പ് Goal + Time Horizon + Risk Profile നോക്കുക.


    Step-Up SIP എന്താണ്?

    നിങ്ങളുടെ income കാലക്രമേണ കൂടുന്നുണ്ടെങ്കിൽ, SIP തുകയും അതിനനുസരിച്ച് കൂട്ടുന്ന രീതിയാണ് Step-Up SIP.

    ഇത് Top-Up SIP എന്നും അറിയപ്പെടുന്നു.

    ഒരു ഉദാഹരണം നോക്കാം.

    നിങ്ങൾ മാസം ₹5,000 SIP ആരംഭിക്കുന്നു എന്ന് കരുതുക.

    ഓരോ വർഷവും SIP 10% കൂട്ടാൻ തീരുമാനിച്ചാൽ:

    • ആദ്യ വർഷം — ₹5,000
    • അടുത്ത വർഷം — ₹5,500
    • അതിന് ശേഷം — ₹6,050

    ഇങ്ങനെ നിങ്ങളുടെ income കൂടുന്നതിനനുസരിച്ച് SIP amount ക്രമേണ ഉയർത്താം.

    ഇത് ഒരു illustrative example മാത്രമാണ്. Step-Up SIP വഴി ഭാവിയിൽ എത്ര corpus ലഭിക്കും എന്ന് ഉറപ്പായി പറയാനാവില്ല. Actual investment value market performance, scheme, investment period തുടങ്ങിയ കാര്യങ്ങളെ ആശ്രയിച്ചിരിക്കും.

    പക്ഷേ ആശയം ലളിതമാണ്:

    Income കൂടുമ്പോൾ investment contribution-വും ക്രമേണ കൂട്ടുക.


    Step-Up SIP എന്തുകൊണ്ട് പരിഗണിക്കാം?

    തുടക്കത്തിൽ വലിയ SIP എടുക്കാൻ ബുദ്ധിമുട്ടുള്ള ഒരാൾക്ക് ചെറിയ തുകയിൽ തുടങ്ങാം.

    പിന്നീട്:

    Income ↑ → SIP ↑

    എന്ന രീതിയിൽ investment amount ക്രമേണ കൂട്ടാം.

    ഇത് “ഇപ്പോൾ തന്നെ വലിയ തുക invest ചെയ്യണം” എന്ന pressure കുറയ്ക്കാൻ സഹായിക്കുന്ന ഒരു രീതിയായി കാണാം.

    പക്ഷേ Step-Up SIP എല്ലാവർക്കും ഒരേ ശതമാനത്തിൽ വേണമെന്നില്ല. നിങ്ങളുടെ income, expenses, goals, മറ്റ് financial commitments എന്നിവ നോക്കിയാണ് തുക തീരുമാനിക്കേണ്ടത്.


    Mutual Fund സുരക്ഷിതമാണോ?

    ഇവിടെ “safe” എന്ന വാക്കിന് രണ്ട് വ്യത്യസ്ത അർത്ഥങ്ങളുണ്ട്.

    Market risk ഉണ്ടോ?

    ഉണ്ട്.

    Mutual Fund investments market-linked ആണ്. Scheme-ന്റെ underlying investments-ന്റെ value മാറുന്നതിനനുസരിച്ച് നിങ്ങളുടെ investment value-യും മാറാം.

    പണം ആരുടെ കൈയിലാണ് എന്ന ആശങ്കയാണോ?

    ഇവിടെ process മനസ്സിലാക്കുന്നത് പ്രധാനമാണ്.

    Mutual Fund-ൽ നിക്ഷേപിക്കുമ്പോൾ AMC-യുടെ official channels, registered intermediaries, approved payment mechanisms എന്നിവ വഴിയാണ് transaction നടത്തുന്നത്. AMFIയുടെ investor guidance പ്രകാരം investors-ക്ക് AMC വഴി നേരിട്ടോ, AMFI-registered Mutual Fund Distributor വഴിയോ invest ചെയ്യാം.

    അതുകൊണ്ട് ഒരു distributor-ന്റെ personal bank account-ലേക്ക് investment amount അയയ്ക്കുന്നത് ഒഴിവാക്കുക.

    Payment ചെയ്യുമ്പോൾ official AMC/platform/payment process തന്നെയാണോ ഉപയോഗിക്കുന്നത് എന്ന് ഉറപ്പാക്കുക.

    SIP-കൾക്ക് bank mandate, direct debit/NACH തുടങ്ങിയ payment mechanisms ഉപയോഗിക്കാവുന്നതാണ്; applicable payment process scheme/AMC അനുസരിച്ച് പരിശോധിക്കണം.


    Mutual Fund Distributor എന്താണ് ചെയ്യുന്നത്?

    ഒരു Mutual Fund Distributor-ന്റെ role investment amount കൈവശം വയ്ക്കുക എന്നതല്ല.

    അവർ investor-നെ സഹായിക്കുന്നത്:

    • Mutual Fund concepts മനസ്സിലാക്കാൻ
    • investment process പൂർത്തിയാക്കാൻ
    • SIP/Lump Sum സംബന്ധിച്ച് guidance ലഭിക്കാൻ
    • goals അനുസരിച്ചുള്ള investment discussion നടത്താൻ
    • portfolio സംബന്ധിച്ച service/support ലഭിക്കാൻ

    എന്നിവയിലാണ്.

    BVB Capital-ന്റെ brand positioning-ലും education, transparency, goal-based investing, disciplined long-term approach എന്നിവയ്ക്കാണ് പ്രാധാന്യം നൽകുന്നത്.


    നിക്ഷേപം തുടങ്ങുന്നതിന് മുമ്പ് ശ്രദ്ധിക്കേണ്ട 4 കാര്യങ്ങൾ

    1. Goal

    “എന്തിനാണ് ഈ പണം നിക്ഷേപിക്കുന്നത്?”

    ഈ ചോദ്യത്തിന് ആദ്യം ഉത്തരം കണ്ടെത്തുക.

    2. Time Horizon

    “എപ്പോൾ ഈ പണം ആവശ്യമാകും?”

    Long-term goal ആണോ short-term need ആണോ എന്നത് investment approach-നെ സ്വാധീനിക്കും.

    3. Emergency Fund

    അപ്രതീക്ഷിത ചെലവുകൾ വന്നാൽ Mutual Fund investment ഉടൻ പിൻവലിക്കേണ്ട സാഹചര്യം ഉണ്ടാകാതിരിക്കാനായി emergency savings പ്രധാനമാണ്.

    4. Asset Allocation

    Asset Allocation എന്നത് നിങ്ങളുടെ പണം മുഴുവൻ ഒരേ തരത്തിലുള്ള investment-ൽ ഇടാതെ, goal-നും risk-നും അനുസരിച്ച് വിവിധ asset classes-ലായി ക്രമീകരിക്കുന്ന രീതിയാണ്.

    എല്ലാ പണവും ഒരേ fund-ലോ ഒരേ market segment-ലോ ഇടുന്നതും, മറുവശത്ത് ആവശ്യമില്ലാതെ പല funds വാങ്ങുന്നതും ഒഴിവാക്കണം.


    Mutual Fund നിക്ഷേപത്തിൽ പലരും ചെയ്യുന്ന തെറ്റുകൾ

    “Market ശരിയാകുമ്പോൾ തുടങ്ങാം” എന്ന് കാത്തിരിക്കുക

    Market-ന് perfect entry point കണ്ടെത്തുക എളുപ്പമല്ല.

    അതുകൊണ്ട് market timing-നെ മാത്രം ആശ്രയിച്ച് investment തുടക്കം അനന്തമായി മാറ്റിവയ്ക്കുന്നത് പ്രായോഗികമല്ല.

    മറ്റൊരാൾ നിക്ഷേപിച്ച fund അതേപടി തിരഞ്ഞെടുക്കുക

    നിങ്ങളുടെ friend-ന്റെ goal, income, time horizon, risk profile എന്നിവ നിങ്ങളുടേതിന് തുല്യമാകണമെന്നില്ല.

    അതുകൊണ്ട് “അവൻ എടുത്ത fund” എന്നത് മാത്രം ഒരു investment reason ആകരുത്.

    ഒരേ category-യിലെ ഒരുപാട് funds വാങ്ങുക

    Funds എണ്ണം കൂടിയാൽ മാത്രം diversification മെച്ചപ്പെടണമെന്നില്ല.

    Similar holdings ഉള്ള പല funds ഒരുമിച്ച് കൈവശം വച്ചാൽ portfolio overlap ഉണ്ടാകാം.

    ഇതിനെക്കുറിച്ച് കൂടുതൽ വായിക്കാൻ [Portfolio overlap സംബന്ധിച്ച BVB Capital article – URL verification required].

    Return മാത്രം നോക്കി investment തീരുമാനിക്കുക

    “ഈ fund ഇത്ര return നൽകി” എന്നത് മാത്രം നോക്കാതെ goal, risk, time horizon, portfolio fit എന്നിവയും പരിഗണിക്കണം.


    ₹500 SIP എല്ലാവർക്കും മതിയാകുമോ?

    അല്ല.

    ₹500 SIP ഒരു ചെറിയ തുടക്കമായി കാണാം. പക്ഷേ നിങ്ങളുടെ financial goal-ന് ആവശ്യമായ SIP amount വേറെയായിരിക്കാം.

    ഉദാഹരണത്തിന്, retirement ലക്ഷ്യവും 5 വർഷത്തിനുള്ളിൽ ഒരു വലിയ ചെലവിനുള്ള ലക്ഷ്യവും ഒരേ SIP amount കൊണ്ട് plan ചെയ്യണമെന്നില്ല.

    അതിനാൽ ശരിയായ ചോദ്യം:

    “എത്ര രൂപയിൽ തുടങ്ങാം?” എന്നതിനെക്കാൾ “എന്റെ ലക്ഷ്യത്തിന് എത്ര നിക്ഷേപം വേണം?”

    എന്നതാണ്.


    Step-Up SIP എപ്പോൾ പരിഗണിക്കാം?

    നിങ്ങളുടെ salary അല്ലെങ്കിൽ business income കാലക്രമേണ ഉയരുന്നുണ്ടെങ്കിൽ, investment amount-ും ക്രമേണ കൂട്ടുന്നത് പരിഗണിക്കാം.

    ഉദാഹരണം:

    ₹5,000 → ₹5,500 → ₹6,050 → …

    ഇങ്ങനെ ചെയ്യുന്നത് നിങ്ങളുടെ monthly cash flow-നെ പൂർണ്ണമായി മാറ്റിമറിക്കാതെ investment contribution ക്രമേണ വർധിപ്പിക്കാൻ സഹായിക്കാം.

    എന്നാൽ percentage അല്ലെങ്കിൽ frequency എല്ലാവർക്കും ഒരുപോലെ ആവശ്യമില്ല. നിങ്ങളുടെ സാഹചര്യത്തിന് അനുസരിച്ചാണ് തീരുമാനിക്കേണ്ടത്.


    പ്രധാന കാര്യങ്ങൾ ചുരുക്കത്തിൽ

    • Mutual Fund-ൽ നിക്ഷേപിക്കാൻ വലിയ തുക കാത്തിരിക്കേണ്ടതില്ല; നിങ്ങളുടെ സാഹചര്യത്തിന് അനുയോജ്യമായ ചെറിയ തുകയിൽ തുടങ്ങാം.
    • ₹500 SIP ഒരു starting point ആയേക്കാം; പക്ഷേ അത് എല്ലാവരുടെയും financial goal-ന് മതിയാകണമെന്നില്ല.
    • SIP market risk ഇല്ലാതാക്കുന്നില്ല.
    • Goal, Time Horizon, Risk Profile എന്നിവ നോക്കിയാണ് investment planning ചെയ്യേണ്ടത്.
    • Income കൂടുമ്പോൾ Step-Up SIP വഴി investment amount ക്രമേണ കൂട്ടുന്നത് പരിഗണിക്കാം.
    • Investment payment ചെയ്യുമ്പോൾ official AMC/approved payment channel ഉപയോഗിക്കുക.
    • ഒരു distributor-ന്റെ personal account-ലേക്ക് investment amount അയയ്ക്കുന്നത് ഒഴിവാക്കുക.
    • Funds തിരഞ്ഞെടുക്കുമ്പോൾ മറ്റുള്ളവരെ copy ചെയ്യുന്നതിന് പകരം നിങ്ങളുടെ സ്വന്തം financial goals നോക്കുക.

    Frequently Asked Questions

    Mutual Fund-ൽ ഏറ്റവും കുറഞ്ഞ തുക എത്രയാണ്?

    Minimum investment amount scheme അനുസരിച്ച് മാറാം. ₹500 SIP ലഭ്യമായ schemes ഉണ്ട്. എന്നാൽ minimum amount മാത്രം നോക്കി investment തീരുമാനിക്കാതെ നിങ്ങളുടെ goal-ന് ആവശ്യമായ amount കൂടി പരിഗണിക്കുക.

    ₹500 SIP കൊണ്ട് തുടങ്ങാമോ?

    നിങ്ങൾ തിരഞ്ഞെടുക്കുന്ന scheme-ൽ ₹500 SIP അനുവദിക്കുന്നുണ്ടെങ്കിൽ തുടങ്ങാം. തുടക്കം കുറിക്കാൻ ഇത് സഹായകരമായേക്കാം. എന്നാൽ long-term goal-ന് ആവശ്യമായ corpus അനുസരിച്ച് പിന്നീട് SIP amount കൂട്ടേണ്ടി വരാം.

    SIP market risk ഇല്ലാതാക്കുമോ?

    ഇല്ല. SIP ഒരു systematic investing method ആണ്; അത് market risk ഇല്ലാതാക്കുന്നില്ല. Underlying Mutual Fund investment-ന്റെ value market conditions അനുസരിച്ച് മാറാം.

    Step-Up SIP എന്താണ്?

    നിശ്ചിത ഇടവേളകളിൽ SIP amount കൂട്ടുന്ന രീതിയാണ് Step-Up SIP. ഉദാഹരണത്തിന്, ₹5,000 SIP ഓരോ വർഷവും 10% കൂട്ടുന്നത് ഒരു illustrative example ആണ്.

    Mutual Fund-ലേക്ക് പണം എവിടെയാണ് നൽകേണ്ടത്?

    AMC-യുടെ official process, registered intermediary, അല്ലെങ്കിൽ approved payment mechanism ഉപയോഗിക്കുക. Distributor-ന്റെ personal bank account-ലേക്ക് investment amount അയയ്ക്കരുത്. AMFIയുടെ investor guidance പ്രകാരം AMC വഴി നേരിട്ടോ AMFI-registered distributor വഴിയോ invest ചെയ്യാം.

    Market ഇടിഞ്ഞാൽ SIP നിർത്തണോ?

    Market movement മാത്രം നോക്കി SIP stop ചെയ്യുന്നതിന് മുമ്പ് നിങ്ങളുടെ goal, time horizon, risk profile എന്നിവ വീണ്ടും പരിശോധിക്കുക. Market direction predict ചെയ്യുന്നതിനുപകരം investment plan-നോട് discipline പാലിക്കുകയാണ് പ്രധാനപ്പെട്ടത്.


    ഇനി വായിക്കാം

    Mutual Fund-ൽ തുടക്കം കുറിക്കുന്നവർക്ക് അടിസ്ഥാന കാര്യങ്ങൾ മനസ്സിലാക്കാൻ:

    SIP-ന്റെ അടിസ്ഥാനവും കൂടുതൽ മനസ്സിലാക്കാൻ BVB Capital-ന്റെ What Is SIP? എന്ന guide-ും വായിക്കാം.


    നിങ്ങളുടെ അടുത്ത പടി എന്താണ്?

    Mutual Fund-ൽ നിക്ഷേപിക്കാനുള്ള പേടി കുറയ്ക്കാനുള്ള ആദ്യപടി വലിയ തുക നിക്ഷേപിക്കുക എന്നതല്ല.

    ആദ്യം കാര്യങ്ങൾ മനസ്സിലാക്കുക.

    നിങ്ങളുടെ goal എന്താണ്?

    എപ്പോൾ പണം ആവശ്യമാകും?

    എത്ര risk എടുക്കാൻ കഴിയും?

    ഇപ്പോൾ എത്ര SIP comfortable ആണ്?

    Income കൂടുമ്പോൾ അത് എങ്ങനെ കൂട്ടാം?

    ഈ ചോദ്യങ്ങൾക്ക് വ്യക്തമായ ഉത്തരം കണ്ടെത്തിയാൽ investment planning കൂടുതൽ structured ആക്കാം.

    നിങ്ങളുടെ financial goals-ന് എത്ര SIP വേണം, നിലവിലെ investments goals-നോട് match ചെയ്യുന്നുണ്ടോ, അല്ലെങ്കിൽ എങ്ങനെ ഒരു disciplined investment plan ആരംഭിക്കാം എന്നതിനെക്കുറിച്ച് clarity വേണമെങ്കിൽ BVB Capital-നോട് സംസാരിക്കാം.

    BVB Capital Private Limited
    AMFI Registered Mutual Fund Distributor
    ARN 348338
    WhatsApp: +91 96339 40008
    Website: https://bvbcap.com/

    നിങ്ങളുടെ ചോദ്യവുമായി WhatsApp ചെയ്യാം. ആദ്യം കാര്യങ്ങൾ മനസ്സിലാക്കുക; അതിന് ശേഷം നിങ്ങളുടെ സാഹചര്യത്തിന് അനുയോജ്യമായ അടുത്ത ഘട്ടം തീരുമാനിക്കാം.

    Disclaimer

    Mutual Fund investments are subject to market risks, read all scheme related documents carefully before investing.
    ഈ ലേഖനത്തിലെ ഉദാഹരണങ്ങളും കണക്കുകളും ആശയം മനസ്സിലാക്കുന്നതിനുള്ള illustrative examples മാത്രമാണ്. Actual investment returns market conditions, scheme performance, investment period എന്നിവ അനുസരിച്ച് മാറാം. ഈ ലേഖനം പൊതുവായ educational information മാത്രമാണ്; വ്യക്തിഗത investment suitability നിങ്ങളുടെ financial goals, time horizon, risk profile, മറ്റ് സാഹചര്യങ്ങൾ എന്നിവ പരിഗണിച്ചാണ് വിലയിരുത്തേണ്ടത്.

  • ഗൾഫ് ജോലി നിർത്തി നാട്ടിലേക്ക് വരാൻ ₹50 ലക്ഷം മതിയോ? Retirement Planning എങ്ങനെ കണക്കാക്കാം?

    ഗൾഫ് ജോലി നിർത്തി നാട്ടിലേക്ക് വരാൻ ₹50 ലക്ഷം മതിയോ? Retirement Planning എങ്ങനെ കണക്കാക്കാം?

    22 വർഷം ഗൾഫിൽ ജോലി ചെയ്തു. ₹50 ലക്ഷം സമ്പാദ്യമായി. ഇനി ഗൾഫ് ജോലി നിർത്തി നാട്ടിലേക്ക് മടങ്ങിയാലോ?

    ഇവിടെ പലരും ആദ്യം ചോദിക്കുന്നത്:

    “₹50 ലക്ഷം ഉണ്ടല്ലോ. അതുകൊണ്ട് retirement എടുക്കാൻ പറ്റുമോ?”

    പക്ഷേ retirement planning-ൽ ചോദിക്കേണ്ട യഥാർത്ഥ ചോദ്യം ഇതല്ല.

    നാട്ടിലെ ജീവിതച്ചെലവിന് ഓരോ മാസവും എത്ര രൂപ വേണം? അതിൽ എത്ര രൂപയ്ക്ക് സ്ഥിരമായ വരുമാനമുണ്ട്? ബാക്കി തുക എത്രകാലം നിങ്ങളുടെ corpus-ൽ നിന്ന് കണ്ടെത്തണം?

    ഇതാണ് പ്രധാനപ്പെട്ട കണക്ക്.

    കാരണം ₹50 ലക്ഷം എന്നത് ഒരു corpus ആണ്. അത് മാത്രം നോക്കി retirement readiness തീരുമാനിക്കാൻ കഴിയില്ല.


    ₹50 ലക്ഷം ഉണ്ടെങ്കിൽ retirement എടുക്കാമോ?

    ചിലർക്കു സാധിച്ചേക്കാം. ചിലർക്കു സാധിക്കില്ല.

    അതിന്റെ ഉത്തരം ഒരേ തുകയ്ക്ക് എല്ലാവർക്കും ഒരുപോലെയല്ല.

    ഉദാഹരണത്തിന്:

    • സ്വന്തം വീട് ഉണ്ടോ?
    • Home Loan ഉണ്ടോ?
    • മാസം എത്ര ചെലവാകും?
    • Pension അല്ലെങ്കിൽ rental income ഉണ്ടോ?
    • മക്കളുടെ വിദ്യാഭ്യാസച്ചെലവ് ബാക്കിയുണ്ടോ?
    • Emergency Fund വേറെയുണ്ടോ?
    • Healthcare ചെലവുകൾ എങ്ങനെ കൈകാര്യം ചെയ്യും?
    • Retirement കഴിഞ്ഞാൽ മറ്റൊരു income ഉണ്ടാകുമോ?

    ഇവയെല്ലാം നോക്കിയ ശേഷമാണ് ₹50 ലക്ഷം മതിയോ എന്ന് പറയേണ്ടത്.

    അതായത്, ₹50 ലക്ഷം എന്ന തുകയേക്കാൾ പ്രധാനമാണ് ആ തുകയ്ക്ക് മുന്നിൽ നിൽക്കുന്ന നിങ്ങളുടെ future expenses.


    ഒരു ഉദാഹരണം നോക്കാം: 47 വയസ്സുള്ള ഷാജി

    ഷാജിക്ക് 47 വയസ്സാണ്. 22 വർഷമായി UAE-യിൽ ജോലി ചെയ്യുന്നു.

    അദ്ദേഹത്തിന്റെ കുടുംബത്തിൽ ഭാര്യയും 16, 12 വയസ്സുള്ള രണ്ട് കുട്ടികളുമുണ്ട്. നാട്ടിൽ സ്വന്തം വീടുണ്ട്, Home Loan ഇല്ല.

    ബാങ്ക് നിക്ഷേപങ്ങളും മറ്റ് സമ്പാദ്യങ്ങളും ചേർന്ന് ₹50 ലക്ഷം ഉണ്ട്.

    നാട്ടിലേക്ക് മടങ്ങിയാൽ കുടുംബത്തിന് മാസം ഏകദേശം ₹65,000 ചെലവാകുമെന്ന് ഷാജി കണക്കാക്കുന്നു.

    ഇപ്പോൾ നമുക്ക് ഈ കണക്ക് നോക്കാം.

    ഷാജിയുടെ അടിസ്ഥാന കണക്ക്

    കാര്യംതുക
    ആകെ സമ്പാദ്യം₹50 ലക്ഷം
    പ്രതിമാസ ചെലവ്₹65,000
    വാർഷിക ചെലവ്₹7.8 ലക്ഷം
    Initial Withdrawal Rate15.6%

    ₹65,000 × 12 = ₹7.8 ലക്ഷം

    ₹7.8 ലക്ഷം എന്നത് ₹50 ലക്ഷത്തിന്റെ 15.6% ആണ്.

    അതായത്, മറ്റൊരു വരുമാനവും ഇല്ലെന്ന് കരുതിയാൽ, ആദ്യ വർഷത്തെ ചെലവിനായി തന്നെ corpus-ന്റെ വലിയൊരു ഭാഗം ഉപയോഗിക്കേണ്ടി വരുന്നു.

    ഇത് 15.6% return ലഭിക്കും എന്നൊന്നുമല്ല. ഇത് ഒരു withdrawal calculation മാത്രമാണ്.

    Retirement എത്ര വർഷം നീളും, inflation എങ്ങനെ മാറും, investments-ന്റെ actual return എങ്ങനെയായിരിക്കും തുടങ്ങിയ കാര്യങ്ങൾ കൂടി പരിഗണിക്കണം.


    Withdrawal Rate എന്താണ്?

    നിങ്ങളുടെ retirement corpus-ൽ നിന്ന് ഒരു വർഷം ചെലവിനായി എത്ര ശതമാനം തുക എടുക്കേണ്ടിവരുന്നു എന്നതാണ് ലളിതമായി പറഞ്ഞാൽ Initial Withdrawal Rate.

    ഉദാഹരണത്തിന് ₹50 ലക്ഷം corpus ഉണ്ടെങ്കിൽ:

    മാസം ചെലവ്വാർഷിക ചെലവ്₹50 ലക്ഷത്തിലെ Initial Withdrawal Rate
    ₹25,000₹3 ലക്ഷം6%
    ₹40,000₹4.8 ലക്ഷം9.6%
    ₹50,000₹6 ലക്ഷം12%
    ₹65,000₹7.8 ലക്ഷം15.6%
    ₹75,000₹9 ലക്ഷം18%

    ഇത് സുസ്ഥിരമായ withdrawal rate എത്രയാണെന്ന് പറയുന്ന പട്ടികയല്ല.

    വിരമിക്കൽ കാലയളവ്, inflation, investment returns, മറ്റു വരുമാനങ്ങൾ, future goals എന്നിവ അനുസരിച്ച് യഥാർത്ഥ സ്ഥിതി മാറും.

    പക്ഷേ ഈ പട്ടിക ഒരു കാര്യം വളരെ വ്യക്തമായി കാണിക്കുന്നു:

    മാസച്ചെലവ് കൂടുമ്പോൾ അതേ ₹50 ലക്ഷം corpus-നുള്ള സമ്മർദ്ദവും കൂടും.


    ₹50 ലക്ഷം മുഴുവൻ retirement corpus ആണോ?

    ഇവിടെയാണ് പലരും ചെയ്യുന്ന മറ്റൊരു പ്രധാന തെറ്റ്.

    കയ്യിൽ ₹50 ലക്ഷം ഉണ്ടെന്ന് കരുതി മുഴുവൻ തുകയും retirement money ആയി കണക്കാക്കരുത്.

    നിങ്ങളുടെ പണത്തിന് ഒരേ സമയം പല ആവശ്യങ്ങൾ ഉണ്ടായേക്കാം.

    അതുകൊണ്ട് retirement planning-ൽ ഒരു 5-Bucket approach ആയി ചിന്തിക്കുന്നത് സഹായകരമാണ്. Approved video script-ലും ഈ അഞ്ച് ആവശ്യങ്ങളാണ് എടുത്തുപറയുന്നത്.

    1. Household Expenses

    നാട്ടിലെത്തിയ ശേഷം വീട്ടിലെ സാധാരണ ജീവിതച്ചെലവുകൾക്കുള്ള പണം.

    ഭക്ഷണം, utilities, യാത്ര, മറ്റ് സ്ഥിരം ചെലവുകൾ എന്നിവ ഇതിൽ വരാം.

    2. Children’s Education

    മക്കളുടെ higher education പോലുള്ള വലിയ future expenses.

    ഷാജിയുടെ ഉദാഹരണത്തിൽ മകളുടെ higher studies-ന് ₹20 ലക്ഷം വേണമെങ്കിൽ, ആ ₹20 ലക്ഷം retirement corpus ആയി കണക്കാക്കാൻ കഴിയില്ല.

    ₹50 ലക്ഷത്തിൽ നിന്ന് ₹20 ലക്ഷം അതിനായി മാറ്റിവെച്ചാൽ:

    Retirement-ന് ബാക്കിയാകുന്നത് ₹30 ലക്ഷം മാത്രം.

    ഇതാണ് corpus-നെ ശരിയായി കാണേണ്ടതിന്റെ പ്രാധാന്യം.

    3. Emergency Reserve

    പെട്ടെന്ന് ജോലി നഷ്ടപ്പെടുക, കുടുംബത്തിലെ വലിയ സാമ്പത്തിക ആവശ്യം, മറ്റ് അടിയന്തിര സാഹചര്യങ്ങൾ തുടങ്ങിയവയ്ക്കായി വേറൊരു reserve ആവശ്യമാണ്.

    4. Healthcare / Insurance

    പ്രായം കൂടുന്നതിനനുസരിച്ച് healthcare ചെലവുകൾ retirement planning-ൽ പ്രധാനമാണ്.

    Health Insurance ഉണ്ടെങ്കിലും അതിന് പുറമെ ആവശ്യമായ medical/emergency reserve എന്നത് വേറൊരു കാര്യമാണ്. Approved script-ലും ഇതേ distinction വ്യക്തമാക്കുന്നു.

    5. Pure Retirement Corpus

    മുകളിലുള്ള ആവശ്യങ്ങൾക്കായി മാറ്റിവെച്ചതിനു ശേഷം യഥാർത്ഥത്തിൽ retirement ജീവിതത്തിനായി ഉപയോഗിക്കാവുന്ന തുകയാണ് Pure Retirement Corpus.

    അതിനാൽ:

    “എന്റെ കയ്യിൽ ₹50 ലക്ഷം ഉണ്ട്” എന്നതിന് പകരം “എന്റെ retirement-ന് യഥാർത്ഥത്തിൽ എത്ര രൂപ ലഭ്യമാണ്?” എന്ന് ചോദിക്കണം.


    Gulf-ൽ നിന്ന് നാട്ടിലേക്ക് മടങ്ങുമ്പോൾ മറ്റൊരു കണക്ക് കൂടി നോക്കണം

    ഗൾഫിൽ ജോലി ചെയ്യുമ്പോൾ ലഭിച്ചിരുന്ന salary നിർത്തിയാൽ നിങ്ങളുടെ cash flow എങ്ങനെ മാറും?

    നാട്ടിലെത്തിയ ശേഷം:

    • Pension ഉണ്ടോ?
    • Rental income ഉണ്ടോ?
    • Part-time income ഉണ്ടോ?
    • Business income ഉണ്ടോ?
    • മറ്റേതെങ്കിലും സ്ഥിരമായ വരുമാനമുണ്ടോ?

    ഇവയൊക്കെ monthly expense-ൽ നിന്ന് കുറച്ചശേഷം corpus-ൽ നിന്ന് കണ്ടെത്തേണ്ട തുക എത്രയെന്ന് നോക്കണം.

    ഉദാഹരണത്തിന്, മാസം ₹65,000 ചെലവാണെന്ന് കരുതുക.

    മറ്റൊരു സ്ഥിരമായ വരുമാനം മാസം ₹25,000 ഉണ്ടെങ്കിൽ, മുഴുവൻ ₹65,000-വും corpus-ൽ നിന്ന് എടുക്കേണ്ട സാഹചര്യമല്ല.

    അതുകൊണ്ട് retirement planning എന്നത്:

    Corpus മാത്രം നോക്കുന്നത് അല്ല — Cash Flow നോക്കുന്നതാണ്.


    Inflation മറക്കരുത്

    ഇന്ന് മാസം ₹65,000 ചെലവാകുന്നു എന്നതുകൊണ്ട് retirement കാലം മുഴുവൻ ₹65,000 മതിയാകും എന്ന് കരുതാൻ പാടില്ല.

    കാലം കഴിയുമ്പോൾ സാധനങ്ങളുടെയും സേവനങ്ങളുടെയും വില മാറാം.

    അതുകൊണ്ട് retirement planning ചെയ്യുമ്പോൾ ഇന്നത്തെ ചെലവ് മാത്രം നോക്കാതെ future expenses കൂടി കണക്കിലെടുക്കണം.

    പ്രത്യേകിച്ച് 40-കളിൽ retirement എടുക്കുന്ന ഒരാൾക്ക് retirement period ദീർഘമായിരിക്കാം.

    അതിനാൽ:

    ഇന്നത്തെ ₹50 ലക്ഷം → ഇന്നത്തെ ചെലവ്

    എന്ന കണക്കിൽ മാത്രം നിൽക്കാതെ,

    Future expenses → inflation → retirement period → corpus requirement

    എന്ന ക്രമത്തിൽ ചിന്തിക്കണം.


    “₹50 ലക്ഷം ഉണ്ടെങ്കിൽ ഇനി ജോലി വേണ്ട” എന്ന കണക്ക് എന്തുകൊണ്ട് അപകടകരമാണ്?

    ₹50 ലക്ഷം എന്ന round figure മനസ്സിൽ വെച്ച് retirement തീരുമാനിക്കുന്നത് എളുപ്പമാണ്.

    പക്ഷേ ഓരോ കുടുംബത്തിന്റെയും സ്ഥിതി വ്യത്യസ്തമാണ്.

    ഒരാൾക്ക്

    • സ്വന്തം വീട്
    • വലിയ കടമില്ല
    • മാസം ₹30,000 മാത്രം ചെലവ്
    • വേറൊരു income
    • emergency reserve

    ഇവ ഉണ്ടാകാം.

    മറ്റൊരാൾക്ക്

    • മാസം ₹75,000 ചെലവ്
    • കുട്ടികളുടെ education
    • medical expenses
    • മറ്റൊരു income ഇല്ല

    എന്നിവ ഉണ്ടായേക്കാം.

    രണ്ടുപേരുടെയും corpus ₹50 ലക്ഷം ആയാലും retirement readiness ഒരുപോലെയല്ല.


    Retirement planning തുടങ്ങേണ്ടത് എവിടെ നിന്നാണ്?

    Investment product തിരഞ്ഞെടുക്കുന്നതിന് മുമ്പ് ഈ അഞ്ച് ചോദ്യങ്ങൾക്ക് ഉത്തരം കണ്ടെത്തുക:

    1. Retirement കഴിഞ്ഞാൽ മാസം എത്ര ചെലവാകും?
    2. ആ ചെലവിൽ എത്ര ഭാഗം മറ്റൊരു വരുമാനത്തിൽ നിന്ന് ലഭിക്കും?
    3. മക്കളുടെ education പോലുള്ള future goals-ന് എത്ര തുക വേണം?
    4. Emergency & healthcare ആവശ്യങ്ങൾക്കായി എത്ര reserve വേണം?
    5. എല്ലാം മാറ്റിവെച്ച ശേഷം യഥാർത്ഥ retirement corpus എത്രയാണ്?

    അതിനുശേഷമാണ് investment structure, asset allocation, income strategy തുടങ്ങിയ കാര്യങ്ങൾ ചർച്ച ചെയ്യേണ്ടത്.


    ₹50 ലക്ഷം ഉള്ള ഒരു Gulf investor എന്താണ് ആദ്യം ചെയ്യേണ്ടത്?

    ഒറ്റയടിക്ക് മുഴുവൻ പണവും ഒരു investment-ലേക്ക് മാറ്റുക എന്നതല്ല ആദ്യപടി.

    ആദ്യം:

    1. Expenses കണ്ടെത്തുക →
    2. Future goals കണ്ടെത്തുക →
    3. Emergency & healthcare reserve വേർതിരിക്കുക →
    4. Retirement corpus കണ്ടെത്തുക →
    5. അതിന് അനുയോജ്യമായ investment strategy ആലോചിക്കുക →
    6. Periodically review ചെയ്യുക

    ഇതാണ് കൂടുതൽ വ്യക്തമായ സമീപനം.

    Retirement planning-ൽ product-നെക്കാൾ goal + cash flow + time horizon + risk ആണ് ആദ്യം.


    ഒറ്റവാക്കിൽ: ₹50 ലക്ഷം മതിയോ?

    ₹50 ലക്ഷം മാത്രം നോക്കി “മതി” എന്നും “മതിയാകില്ല” എന്നും പറയാൻ കഴിയില്ല.

    നിങ്ങളുടെ:

    • monthly expenses,
    • മറ്റ് വരുമാനങ്ങൾ,
    • കുട്ടികളുടെ future expenses,
    • emergency reserve,
    • healthcare needs,
    • inflation,
    • retirement duration

    എന്നിവയാണ് യഥാർത്ഥ answer തീരുമാനിക്കുന്നത്.

    അതുകൊണ്ട് Gulf ജോലി നിർത്തി നാട്ടിലേക്ക് മടങ്ങാനുള്ള തീരുമാനം “എന്റെ കയ്യിൽ എത്ര പണമുണ്ട്?” എന്ന ചോദ്യത്തിൽ നിന്ന് തുടങ്ങേണ്ടതില്ല.

    “എന്റെ ബാക്കി ജീവിതത്തിന് എത്ര പണം വേണം?” എന്ന ചോദ്യത്തിൽ നിന്നാണ് തുടങ്ങേണ്ടത്.


    Frequently Asked Questions

    ₹50 ലക്ഷം കൊണ്ട് 47-ാം വയസ്സിൽ retirement എടുക്കാമോ?

    ഒരു പൊതുവായ “അതെ” അല്ലെങ്കിൽ “ഇല്ല” ഉത്തരം നൽകാൻ കഴിയില്ല. 47-ാം വയസ്സിൽ retirement എടുത്താൽ retirement period ദീർഘമായിരിക്കാം. Monthly expenses, future goals, other income, inflation, healthcare needs എന്നിവ കണക്കിലെടുത്താണ് തീരുമാനം എടുക്കേണ്ടത്.

    ₹50 ലക്ഷം retirement corpus ആണെന്ന് എങ്ങനെ മനസ്സിലാക്കാം?

    നിങ്ങളുടെ മൊത്തം savings-ൽ നിന്ന് children’s education, emergency reserve, healthcare തുടങ്ങിയ ആവശ്യങ്ങൾക്കായി മാറ്റിവെക്കേണ്ട തുക ആദ്യം വേർതിരിക്കുക. ശേഷിക്കുന്ന തുകയാണ് retirement-ന് യഥാർത്ഥത്തിൽ ലഭ്യമായ corpus എന്ന് കാണുന്നത് കൂടുതൽ യുക്തിസഹമാണ്.

    Withdrawal Rate എന്താണ്?

    ഒരു വർഷം retirement corpus-ൽ നിന്ന് ചെലവിനായി എത്ര ശതമാനം തുക എടുക്കേണ്ടിവരുന്നു എന്നതാണ് Initial Withdrawal Rate. ഉദാഹരണത്തിന് ₹50 ലക്ഷം corpus-ൽ നിന്ന് ഒരു വർഷം ₹7.8 ലക്ഷം എടുക്കേണ്ടിവന്നാൽ അത് 15.6% ആണ്.

    Gulf-ൽ നിന്ന് നാട്ടിലേക്ക് മടങ്ങുമ്പോൾ എന്തൊക്കെ കണക്കാക്കണം?

    Monthly expenses, pension/other income, children’s education, emergency fund, healthcare, inflation, retirement period എന്നിവ പ്രധാനമാണ്.

    Retirement planning-ൽ SIP മാത്രം നോക്കിയാൽ മതിയോ?

    അല്ല. SIP തുക മാത്രം നോക്കാതെ goal, required corpus, time horizon, risk, future expenses എന്നിവയും നോക്കണം. Retirement planning എന്നത് ഒരു investment amount തീരുമാനിക്കുന്നതിൽ മാത്രം ഒതുങ്ങുന്നില്ല.


    ഇനി വായിക്കാം

    Retirement planning-നൊപ്പം goal-based investing എങ്ങനെ ചെയ്യാം എന്നതിനെക്കുറിച്ച് കൂടുതൽ മനസ്സിലാക്കാൻ BVB Capital-ന്റെ Investor Awareness & Behaviour വിഭാഗം വായിക്കാം.

    Mutual Fund അടിസ്ഥാന കാര്യങ്ങൾ ആദ്യം മനസ്സിലാക്കണമെങ്കിൽ Mutual Fund എന്താണ്? എന്ന guide ഉപകാരപ്പെടും. Mutual Fund എന്താണ്?

    BVB Capital-ന്റെ മറ്റ് financial education articles കാണാൻ Blog വിഭാഗം സന്ദർശിക്കാം. BVB Capital Blog


    ഈ വിഷയം വീഡിയോയായി കാണാം

    ഗൾഫ് ജോലി നിർത്തി നാട്ടിലേക്ക് വരാൻ ₹50 ലക്ഷം മതിയോ? സത്യം ഇതാണ്!

    ഈ ലേഖനത്തിന്റെ അടിസ്ഥാനമായ approved YouTube script-ൽ ₹50 ലക്ഷം corpus-നും monthly expense-നും ഇടയിലുള്ള വ്യത്യാസം, ഷാജിയുടെ ഉദാഹരണം, Withdrawal Rate, അഞ്ച് Buckets എന്നിവ visual examples ഉപയോഗിച്ച് വിശദീകരിക്കുന്നു.


    നിങ്ങളുടെ Gulf Retirement Plan എവിടെയാണ് നിൽക്കുന്നത്?

    ₹50 ലക്ഷം ഉണ്ടോ എന്നത് മാത്രം നോക്കേണ്ടതില്ല.

    നിങ്ങളുടെ monthly expense എത്രയാണ്?
    മക്കളുടെ future goals എത്രയാണ്?
    Emergency & healthcare reserve എത്ര വേണം?
    Retirement-ന് യഥാർത്ഥത്തിൽ എത്ര corpus ലഭ്യമാണ്?

    ഇവയ്ക്ക് വ്യക്തമായ ഉത്തരം കിട്ടിയാൽ മാത്രമേ Gulf ജോലി നിർത്തി നാട്ടിലേക്ക് മടങ്ങാനുള്ള തീരുമാനം കൂടുതൽ വ്യക്തമായി ആലോചിക്കാൻ കഴിയൂ.

    നിങ്ങളുടെ സ്വന്തം സാഹചര്യത്തിൽ retirement corpus എത്ര വേണം, monthly cash-flow എങ്ങനെ plan ചെയ്യാം എന്നതിനെക്കുറിച്ച് clarity വേണമെങ്കിൽ BVB Capital-നോട് സംസാരിക്കാം.

    BVB Capital Private Limited
    AMFI Registered Mutual Fund Distributor
    ARN 348338
    WhatsApp: +91 96339 40008
    BVB Capital-നെ ബന്ധപ്പെടാം

    പ്രധാന ശ്രദ്ധിക്കുക

    ഈ ലേഖനത്തിലെ ₹50 ലക്ഷം, ₹65,000 monthly expense, 15.6% withdrawal rate തുടങ്ങിയവ ഷാജി എന്ന hypothetical example അടിസ്ഥാനമാക്കിയുള്ള കണക്കുകളാണ്. ഇവ ഒരു വ്യക്തിയുടെ retirement readiness-ന്റെ ഉറപ്പ് അല്ല. Mutual Fund നിക്ഷേപങ്ങൾ market risk-ന് വിധേയമാണ്; actual returns മാറാം.

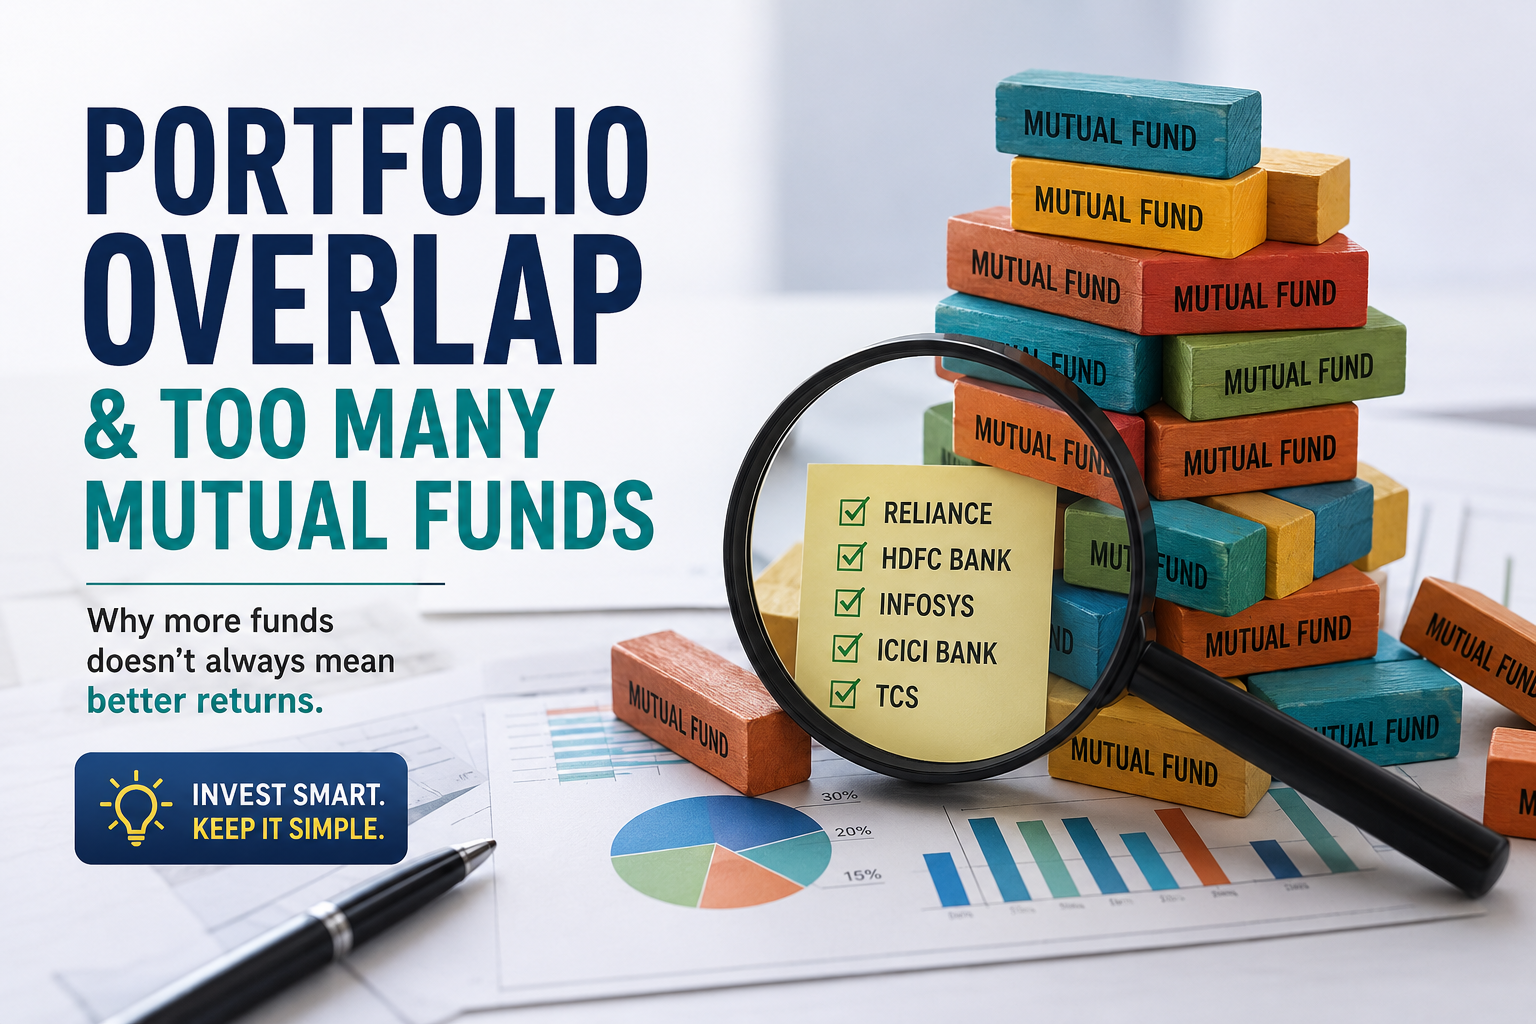
  • Portfolio Overlap & Too Many Mutual Funds: The Hidden Problem Many Investors Don’t Notice

    Portfolio Overlap & Too Many Mutual Funds: The Hidden Problem Many Investors Don’t Notice

    When people start investing in mutual funds, they often feel excited. One friend suggests a fund, YouTube recommends another, social media talks about “top-performing funds,” and before long, the investor ends up holding 8, 10, or even 15 mutual funds.

    At first, this feels like a smart strategy.

    But in reality, many investors unknowingly create a big problem called portfolio overlap.

    This is one of the most common mistakes seen among beginner and even experienced investors in India.

    Let us understand this in the simplest possible way.


    What is Portfolio Overlap?

    Imagine you own:

    • 3 cricket teams
    • But all three teams have almost the same players

    Do you really have different teams?

    Not really.

    The same thing happens in mutual funds.

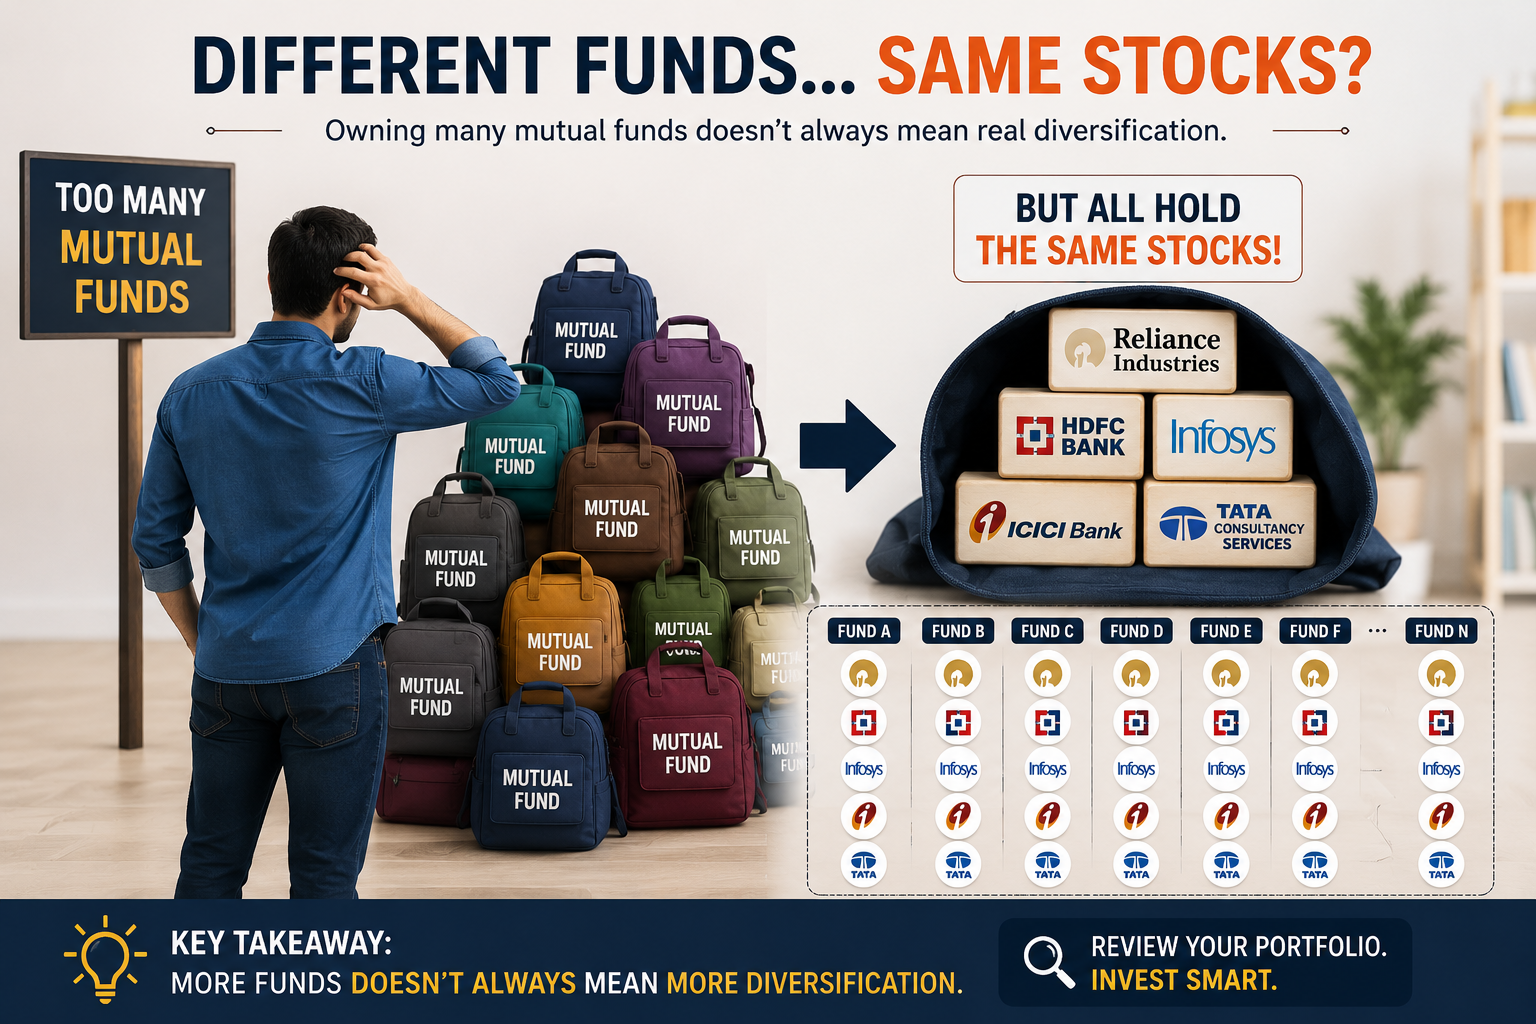
    Many mutual funds buy shares of the same companies like:

    • Reliance
    • HDFC Bank
    • Infosys
    • ICICI Bank
    • TCS

    So even if you own many mutual funds, you may actually be investing in the same stocks repeatedly.

    This is called portfolio overlap.


    A Simple Real-Life Example

    Suppose Ravi invests in:

    1. Large Cap Fund A
    2. Flexi Cap Fund B
    3. Index Fund C

    He feels diversified because he owns 3 funds.

    But when he checks the holdings, he discovers:

    • All three funds heavily own Reliance
    • All three own HDFC Bank
    • All three own Infosys

    Now Ravi’s money is repeatedly going into the same companies.

    This is like buying three different school bags but filling all of them with the same books.


    Why Too Many Mutual Funds Can Become a Problem

    Many people think:

    “More mutual funds means more safety.”

    But that is not always true.

    Sometimes, too many funds create confusion instead of growth.

    1. Difficult to Track

    When you own many funds:

    • Monitoring performance becomes difficult
    • You forget why you invested
    • SIP dates become confusing
    • Rebalancing becomes harder

    Investing should make life simpler, not stressful.


    2. Duplicate Investments

    Many funds may hold similar stocks.

    This means:

    • You are not truly diversified
    • Risk reduction becomes weaker
    • Returns may look almost identical

    You may think you own 10 investments, but actually you own the same 20–30 stocks repeatedly.


    3. Lower Overall Performance

    Some investors keep adding new funds every year.

    The result?

    • Winners and losers cancel each other
    • Portfolio becomes average
    • Strong-performing funds lose impact

    It becomes like having too many cooks in one kitchen.


    4. Emotional Investing Increases

    Too many funds often happen because of:

    • Fear of missing out (FOMO)
    • Social media hype
    • Random recommendations
    • Chasing recent returns

    This creates emotional investing instead of disciplined investing.


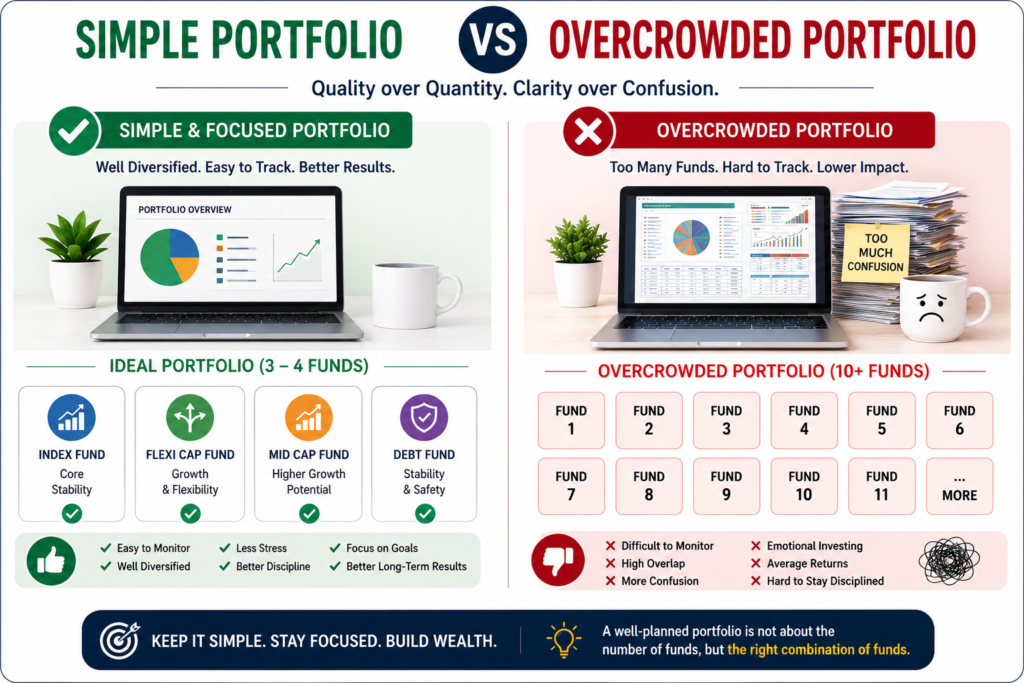
    ideal portfolio

    How Many Mutual Funds Are Actually Enough?

    For most retail investors, a simple portfolio is usually better.

    A basic structure may look like:

    • Equity Funds
    • Debt Fund (depending on goals)

    That itself is enough for many investors.

    You do not need 12 different mutual funds to build wealth.

    Remember:

    A healthy garden does not need 100 plants.
    It needs the right plants, properly maintained.


    What Happens When Funds Overlap Too Much?

    Let us understand with an analogy.

    Imagine you own:

    • 5 umbrellas
    • But all have holes in the same place

    Will owning more umbrellas help during rain?

    No.

    Similarly, owning many mutual funds with the same holdings may not protect your portfolio during market falls.

    True diversification means:

    • Different categories
    • Different strategies
    • Different types of companies

    Not simply more funds.


    Signs That You Have Too Many Mutual Funds

    You may have an overcrowded portfolio if:

    • You cannot remember all your fund names
    • Multiple funds give almost identical returns
    • You invested because someone suggested it
    • You keep adding funds but never reviewing them
    • You own many funds from the same category

    If this sounds familiar, it may be time for a portfolio review.


    How to Check Portfolio Overlap

    You can check overlap by:

    • Looking at top holdings of each fund
    • Comparing fund categories
    • Using online overlap tools
    • Consulting a qualified mutual fund distributor or advisor

    Even a quick review can reveal surprising duplication.


    Is Overlap Always Bad?

    No.

    Some overlap is normal.

    For example:

    • Most large-cap funds will own major Indian companies
    • Index funds naturally hold popular stocks

    The problem begins when overlap becomes excessive.

    Too much repetition reduces the benefit of diversification.


    The Power of Simplicity in Investing

    Some of the best investors in the world follow simple portfolios.

    Why?

    Because simplicity helps:

    • Better decision-making
    • Easier monitoring
    • Less stress
    • Better discipline
    • Long-term consistency

    A simple portfolio is easier to stay invested in during market ups and downs.

    And staying invested for a long time is one of the biggest secrets of wealth creation.


    Portfolio overlap

    Quality Matters More Than Quantity

    Many investors proudly say:

    “I have 15 mutual funds.”

    But the important question is:

    “Do those funds actually serve different purposes?”

    A smaller, well-planned portfolio is often much stronger than a large messy portfolio.

    In investing, more is not always better.

    Better is better.


    Final Thoughts

    Mutual funds are powerful tools for wealth creation.

    But owning too many funds without understanding overlap can silently reduce the effectiveness of your investments.

    Instead of collecting funds like cricket cards, focus on building a clear and meaningful portfolio.

    Think of your investments like a good football team:

    • Every player should have a role
    • Too many players in the same position creates imbalance

    The goal is not to own the maximum number of mutual funds.

    The goal is to build wealth peacefully, steadily, and intelligently.

    Need Help Checking Your Mutual Fund Portfolio?

    Many investors do not realise that their portfolio has become overcrowded with too many mutual funds holding similar stocks.

    If you are unsure whether your investments are properly diversified or unnecessarily complicated, you can contact BVB Capital Private Limited for a professional portfolio review.

    Our experts can help you:

    • Identify portfolio overlap
    • Simplify your mutual fund investments
    • Remove unnecessary duplication
    • Build a cleaner and goal-based portfolio
    • Make investing easier to track and understand

    Sometimes, simplifying your portfolio can improve clarity, confidence, and long-term discipline.

    Contact Details

    BVB CAPITAL PRIVATE LIMITED
    AMFI Registered Mutual Fund Distributor
    ARN: 348338
    Thrissur, Kerala – 680568

    📞 Phone: 080 696 40046
    📱 WhatsApp: 96339 40008

    Invest smart. Keep your portfolio simple, meaningful, and easy to manage.


    Frequently Asked Questions (FAQs)

    1. What is portfolio overlap in mutual funds?

    Portfolio overlap happens when multiple mutual funds own many of the same stocks.


    2. Is it bad to have too many mutual funds?

    Yes, too many mutual funds can create duplication, confusion, and weaker diversification.


    3. How many mutual funds should a beginner have?

    For many beginners, 2 to 4 carefully selected mutual funds are often enough.


    4. Can two mutual funds from different categories overlap?

    Yes. Even different categories may hold some of the same companies.


    5. How can I reduce portfolio overlap?

    Review your holdings regularly and avoid adding funds without a clear purpose.


    Mutual Fund investments are subject to market risks. Read all scheme related documents carefully before investing.
  • SIP Calculator – How Much Should You Invest Monthly to Reach Your Goal?

    SIP Calculator – How Much Should You Invest Monthly to Reach Your Goal?

    Most people start a SIP without knowing if ₹2,000 per month will actually get them where they want to go. They pick an amount that feels comfortable, choose a fund someone recommended, and hope for the best. Years later, they discover the number was never going to be enough.

    SIP CALCULATOR

    This guide — and the SIP calculator below — will tell you the exact monthly SIP amount for any goal, whether it is ₹25 lakh for your child’s college education, ₹1 crore for retirement, or a dream home down payment. You will also learn why the number changes dramatically based on when you start.

    At BVB Capital, we are an AMFI-registered mutual fund distributor (ARN 348338) based in Kerala. We help families across Kerala calculate and start SIPs every day. Everything in this article reflects real numbers and practical guidance we give our clients.

    SIP Goal Calculator

    ₹
    years
    %
    Gains
    Total Investment
    Total Invested
    ₹0
    Target Amount
    ₹50L
    Gains
    ₹0
    Monthly SIP Needed
    ₹0
    Wealth Multiplier: 0x
    *Mutual fund investments are subject to market risks. Past performance does not guarantee future returns. Returns shown are for illustration only.

    What Is a SIP and How Does the SIP Calculator Work?

    A Systematic Investment Plan (SIP) is a method of investing a fixed amount in a mutual fund at regular intervals — usually monthly. Instead of investing a large sum all at once, you invest smaller amounts over time. This approach is called rupee cost averaging: you buy more units when markets are low and fewer when markets are high, which reduces your average cost per unit over the long run.

    The SIP calculator uses the future value formula: FV = P × [((1+r)ⁿ – 1) / r] × (1+r), where P is your monthly SIP amount, r is the monthly return rate, and n is the total number of months. You do not need to understand the formula — the calculator handles all of this automatically.

    HOW TO ACHIVE SIP GOAL

    What you do need to understand is the assumption behind the number. The calculator uses an assumed annual return rate, typically 12% for equity mutual funds. Actual returns will vary depending on the fund you choose and market conditions. We always recommend using 11–12% for long-term equity SIP planning — conservative enough to be realistic, optimistic enough to reflect historical equity performance in India.

    Already know what SIP is? Jump straight to the goal calculator above. New to SIP? Read our complete guide: What Is SIP?

    How Much SIP Per Month for Your Goal? Real Calculations

    SIP CALCULATIONS

    The most common question we hear at BVB Capital is: ‘How much do I need to invest every month?’ The answer depends entirely on your goal, your time horizon, and when you start. Here are the real numbers for the most common financial goals among Kerala investors.

    SIP to Reach ₹50 Lakh

    Assuming a 12% annual return on a diversified equity mutual fund:

    • ₹50 lakh in 10 years → Monthly SIP needed: ~₹21,000
    • ₹50 lakh in 15 years → Monthly SIP needed: ~₹10,800
    • ₹50 lakh in 20 years → Monthly SIP needed: ~₹5,800

    Notice how waiting just 5 extra years cuts your required monthly SIP almost in half. This is the power of compounding — and it is the single most important reason to start today, not next month.

    SIP to Reach ₹1 Crore

    ₹1 crore is the most searched SIP goal in India. Here is what you actually need:

    • ₹1 crore in 10 years → Monthly SIP needed: ~₹43,000
    • ₹1 crore in 15 years → Monthly SIP needed: ~₹21,500
    • ₹1 crore in 20 years → Monthly SIP needed: ~₹11,600
    • ₹1 crore in 25 years → Monthly SIP needed: ~₹6,300

    If ₹43,000/month seems out of reach, starting earlier and giving yourself 20–25 years makes ₹1 crore very achievable — even on a modest income.

    SIP for Child’s Education (₹25 Lakh in 15 Years)

    If your child is under 3 years old today, you have roughly 15 years before college. ₹25 lakh covers a decent engineering or medical degree in Kerala today — though with education inflation, you may want to target ₹35–40 lakh.

    • ₹25 lakh in 15 years at 12% → Monthly SIP: ~₹5,400
    • ₹35 lakh in 15 years at 12% → Monthly SIP: ~₹7,500

    SIP for Retirement (₹2 Crore Corpus)

    If you are 35 years old and plan to retire at 60, you have 25 years. A ₹2 crore corpus — combined with SWP (Systematic Withdrawal Plan) — can give you roughly ₹80,000–90,000 per month in retirement income.

    • ₹2 crore in 25 years at 12% → Monthly SIP: ~₹14,000
    • ₹2 crore in 20 years at 12% → Monthly SIP: ~₹23,200

    Quick Reference: SIP amounts for common goals (at 12% annual return)

    GoalTarget AmountYearsReturnMonthly SIP
    Child’s education₹25 lakh15 years12%~₹5,400/month
    Car purchase₹15 lakh7 years12%~₹11,500/month
    Home down payment₹30 lakh10 years12%~₹13,400/month
    Retirement corpus₹2 crore25 years12%~₹14,000/month
    ₹50 lakh goal₹50 lakh20 years12%~₹5,800/month
    ₹1 crore goal₹1 crore20 years12%~₹11,600/month
    Know your number? Let’s find the right fund. WhatsApp ‘SIP Start’ to BVB Capital for a free consultation. We will match your goal, timeline, and risk appetite to the right mutual fund — at no cost to you.
    BVB Capital | ARN 348338 | SEBI Investor Awareness Certified | Kerala

    3 Factors That Change Your SIP Amount Dramatically

    Factor 1: When You Start (The Cost of Waiting)

    This is the biggest factor of all — and the one most people underestimate. Here is what it costs in monthly SIP amount to reach ₹1 crore by age 60, depending on when you begin:

    When You StartYears to 60ReturnMonthly SIP for ₹1 CrVerdict
    Start at 2535 years12%~₹3,500/monthMost affordable
    Start at 3030 years12%~₹6,000/monthManageable
    Start at 3525 years12%~₹10,500/monthGetting expensive
    Start at 4020 years12%~₹19,000/monthVery costly delay
    Start at 4515 years12%~₹35,000/monthExtremely difficult

    Starting at 25 instead of 35 saves you ₹7,000 per month — every single month — for 25 years. That is a ₹21 lakh difference in total investment, just because of a 10-year head start. Share this table with anyone who is ‘waiting for the right time’ to start investing.

    Factor 2: Expected Rate of Return

    The return rate you assume in the calculator dramatically changes the output. Here is how ₹5,000/month grows over 20 years at different return rates:

    • At 8% annual return: ₹29.4 lakh (debt funds, conservative)
    • At 10% annual return: ₹38.3 lakh (hybrid/balanced funds)
    • At 12% annual return: ₹49.9 lakh (diversified equity funds — most realistic for long-term SIPs)
    • At 14% annual return: ₹66.9 lakh (aggressive small/mid cap — higher risk)

    BVB Capital recommends using 11–12% for planning purposes. It reflects the long-term historical performance of well-managed Indian equity mutual funds without being overoptimistic. Always plan conservatively — if the actual returns are higher, you will simply reach your goal faster.

    Factor 3: Step-Up SIP

    A step-up SIP (also called a top-up SIP) automatically increases your monthly SIP by a fixed percentage each year — usually 10%. Since most people get annual salary hikes, this is a natural way to invest more without feeling the pinch. The impact on your final corpus is enormous:

    • Flat ₹5,000/month for 20 years at 12% → ₹49.9 lakh
    • ₹5,000/month with 10% annual step-up for 20 years at 12% → ₹1.18 crore

    The same starting amount — but a step-up SIP creates more than double the corpus. We cover this in detail in our guide on Step-Up SIP (link: /step-up-sip/).

    5 Common Mistakes People Make When Calculating Their SIP Goal

    Mistake 1: Not Accounting for Inflation

    ₹1 crore sounds like a lot today. But at 6% annual inflation, its purchasing power in 20 years is equivalent to roughly ₹31 lakh today. If you are planning retirement or education 15–20 years away, always set an inflation-adjusted target — not today’s price.

    Rule of thumb Multiply your today’s cost target by 1.8 for a 10-year horizon, 2.4 for 15 years, and 3.2 for 20 years (at 6% inflation). So a ₹20 lakh engineering degree today may cost ₹64 lakh in 20 years.

    Mistake 2: Using Too Optimistic a Return Rate

    Many online SIP calculators default to 15% or even 18%. This is misleading. While some funds have delivered these returns in specific periods, using 15%+ for planning leads to a shortfall. Stick to 11–12% for equity funds over a long horizon. Be pleasantly surprised, not shocked.

    Mistake 3: Not Increasing Your SIP When Your Income Increases

    Investors who set up a ₹3,000 SIP at age 25 and never review it are leaving enormous wealth on the table. Every time your income increases, your SIP should increase too. A 10% annual step-up does this automatically.

    Mistake 4: Stopping SIP During Market Falls

    This is the most costly mistake of all. When markets fall, many investors panic and stop their SIP. But a falling market is exactly when your SIP is buying more units at lower prices — that is rupee cost averaging working in your favour. Missing just the 10 best market days in a 10-year period can reduce your returns by more than 50%.

    Mistake 5: Fund Overlap

    Investing in five different SIPs sounds like diversification, but if all five funds hold the same large-cap stocks, you have no real diversification — only five sets of expense ratios. A proper portfolio review ensures your SIPs work together, not against each other. This is one of the key services BVB Capital provides.

    Frequently Asked Questions About the SIP Calculator

    Q: What is a good return rate to use in a SIP calculator?

    For long-term equity SIP planning (10 years or more), use 11–12% per annum. This is based on the historical CAGR of well-diversified equity mutual funds in India over the past 15–20 years. For debt funds or conservative hybrid funds, use 7–8%.

    Q: Is a SIP calculator 100% accurate?

    No. The SIP calculator assumes a constant return rate every year, but actual mutual fund returns fluctuate. Think of the output as a planning estimate — a target to aim for — not a guaranteed outcome. Actual corpus may be higher or lower depending on market conditions.

    Q: What is the minimum SIP amount I can start with?

    Some mutual funds allow SIPs as low as ₹100 per month. Most financial advisors, including BVB Capital, recommend starting with at least ₹500–₹1,000 to make meaningful progress toward a goal. The key is consistency, not the amount.

    Q: Can I do a SIP for just 1 year?

    Yes, technically you can. But equity SIPs are designed for a minimum 3-year horizon to benefit from market cycles and compounding. A 1-year equity SIP carries significant short-term market risk. For goals under 2 years, liquid funds or short-term debt funds are more appropriate.

    Q: What happens if I miss a SIP instalment?

    Missing one instalment is not a disaster. Most fund houses will simply skip that month and resume the next. However, consistently missing instalments defeats the purpose of disciplined investing and significantly impacts your final corpus.

    Q: How do I start a SIP in Kerala?

    The easiest way is to contact BVB Capital. We are based in Kerala and handle everything — KYC completion, fund selection, SIP setup, and annual portfolio review. Just WhatsApp ‘SIP Start’ to get started. There is no cost to you for our guidance.

    Start Your SIP Today — Your Goal Is Closer Than You Think

    Now you have the numbers. You know how much you need to invest, why starting early makes such an enormous difference, and what mistakes to avoid. The only thing left is to begin.

    Every month you wait is compounding you are not getting. If you are 30 and delay starting by just 2 years, you will need to invest ₹3,000 more per month for the rest of your investment horizon to reach the same corpus. That is the real cost of waiting.

    Start your SIP with BVB Capital — free consultation WhatsApp ‘SIP Start’ to begin. We will help you choose the right fund, set up your KYC, and build a SIP plan matched to your specific goal. BVB Capital | AMFI Registered Distributor | ARN 348338 | Kerala | SEBI Investor Awareness Certified

    Explore More Guides from BVB Capital

    Disclaimer

    Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance is not indicative of future results. The calculations and return rates in this article are for illustration purposes only and do not constitute investment advice. BVB Capital is an AMFI Registered Mutual Fund Distributor (ARN 348338) and is not a SEBI Registered Investment Advisor. Please consult a qualified financial advisor before making investment decisions.
  • എസ്‌.ഐ.പി (SIP) വെറും ‘പരീക്ഷണം’ അല്ല; അഞ്ചു വർഷം പാഴാക്കാതെ സമ്പന്നനാകാൻ ഇതാ ഒരു എളുപ്പവഴി!

    എസ്‌.ഐ.പി (SIP) വെറും ‘പരീക്ഷണം’ അല്ല; അഞ്ചു വർഷം പാഴാക്കാതെ സമ്പന്നനാകാൻ ഇതാ ഒരു എളുപ്പവഴി!

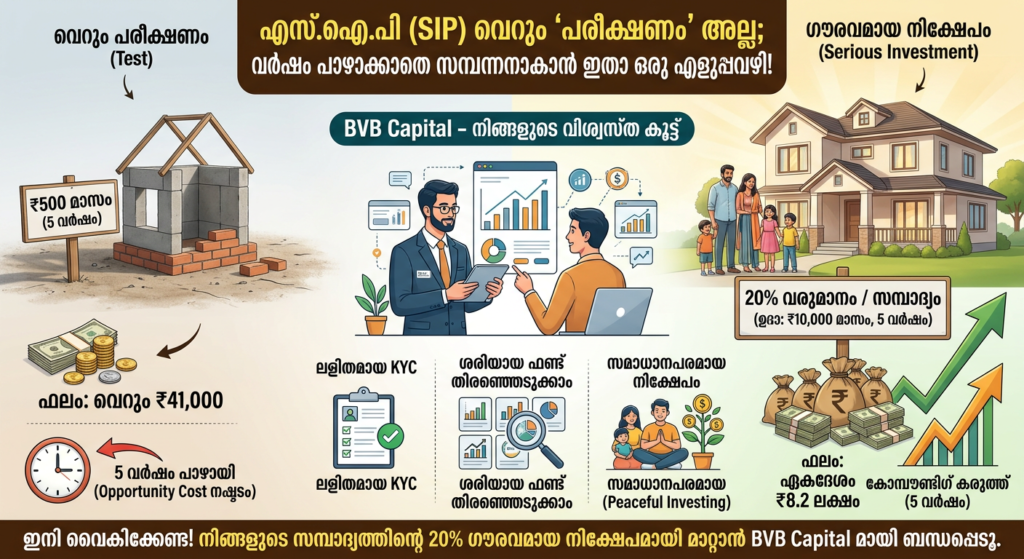
    എന്റെ പ്രിയപ്പെട്ടവരേ, ഒരു കാര്യം ചോദിച്ചോട്ടെ? നമ്മൾ ഒരു പുതിയ വീട് വെക്കാൻ തീരുമാനിച്ചാൽ ആദ്യം അതിന്റെ പ്ലാൻ വരയ്ക്കുകയും തറക്കല്ലിടുകയും ചെയ്യും. അല്ലാതെ, “നമുക്ക് ഈ മാസം ഒരു രണ്ട് കല്ല് വെച്ച് നോക്കാം, എങ്ങനെയുണ്ടാകുമെന്ന് കണ്ടിട്ട് ബാക്കി പണിയാം” എന്ന് ആരെങ്കിലും പറയുമോ? ഇല്ലല്ലോ. കാരണം അങ്ങനെ ചെയ്താൽ ആ വീട് ഒരിക്കലും പണി തീരില്ല എന്ന് നമുക്കറിയാം.

    എന്നാൽ നിക്ഷേപത്തിന്റെ കാര്യത്തിൽ മലയാളി പലപ്പോഴും ചെയ്യുന്നത് ഈ ‘രണ്ട് കല്ല് വെച്ച് നോക്കുന്ന’ പണിയാണ്. പലരും പറയും, “ചേട്ടാ, നമുക്ക് ഒരു 500 രൂപയുടെ എസ്‌.ഐ.പി (SIP) തുടങ്ങാം, ഒരു അഞ്ചു വർഷം ഒന്ന് ടെസ്റ്റ് ചെയ്ത് നോക്കട്ടെ. ലാഭമുണ്ടെങ്കിൽ തുക കൂട്ടാം.” സത്യം പറയട്ടെ, വലിയ തുക നിക്ഷേപിക്കാൻ ശേഷിയുണ്ടായിട്ടും വെറും 500 രൂപയിൽ ഈ അഞ്ചു വർഷം ഒതുങ്ങിനിൽക്കുന്നത് നിങ്ങളുടെ ജീവിതത്തിലെ ഏറ്റവും വിലപ്പെട്ട അഞ്ചു വർഷങ്ങൾ പാഴാക്കുന്നതിന് തുല്യമാണ്.

    ഇന്ന് നമ്മൾ സംസാരിക്കുന്നത് എങ്ങനെ ആത്മവിശ്വാസത്തോടെ നിക്ഷേപം തുടങ്ങാം എന്നും, ഈ യാത്രയിൽ BVB Capital എങ്ങനെ നിങ്ങളുടെ വിശ്വസ്ത പങ്കാളിയാകുന്നു എന്നതിനെ കുറിച്ചുമാണ്.

    500 രൂപയുടെ പരീക്ഷണം: നിങ്ങൾ അറിയാതെ പോകുന്ന നഷ്ടം

    മ്യൂച്വൽ ഫണ്ട് എങ്ങനെയാണ് പ്രവർത്തിക്കുന്നത് എന്ന് മനസ്സിലാക്കാൻ 500 രൂപയുടെ നിക്ഷേപം നല്ലതാണ്. പക്ഷേ, ഒരു കാർ വാങ്ങാനോ, മക്കളുടെ ഉന്നത പഠനത്തിനോ, സമാധാനപരമായ ഒരു റിട്ടയർമെന്റ് കാലത്തിനോ ആണ് നിങ്ങൾ ലക്ഷ്യമിടുന്നതെങ്കിൽ ഈ 500 രൂപയുടെ പരീക്ഷണം നിങ്ങളെ സഹായിക്കില്ല.

    നിക്ഷേപത്തിൽ ഏറ്റവും പ്രധാനം ‘സമയം’ ആണ്. ഒരിക്കൽ പോയാൽ തിരിച്ചു കിട്ടാത്ത ഒന്നാണത്. 500 രൂപ വെച്ച് 5 വർഷം പരീക്ഷണം നടത്തിക്കഴിയുമ്പോൾ നിങ്ങൾക്ക് കാര്യം മനസ്സിലാകും, പക്ഷേ അപ്പോഴേക്കും നിങ്ങളുടെ പ്രായം അഞ്ചു വർഷം കൂടിയിട്ടുണ്ടാകും. ആ അഞ്ചു വർഷം നിങ്ങൾ വലിയൊരു തുക നിക്ഷേപിച്ചിരുന്നെങ്കിൽ ഇന്ന് കിട്ടുന്ന ലാഭത്തിന്റെ പത്തിരട്ടി നിങ്ങൾക്ക് കിട്ടുമായിരുന്നു. ഇതിനെയാണ് സാമ്പത്തിക വിദഗ്ധർ ‘ഓപ്പർച്യുണിറ്റി കോസ്റ്റ്’ എന്ന് വിളിക്കുന്നത്.

    ഒരു കഥ കേൾക്കൂ: സുരേഷും രമേശും

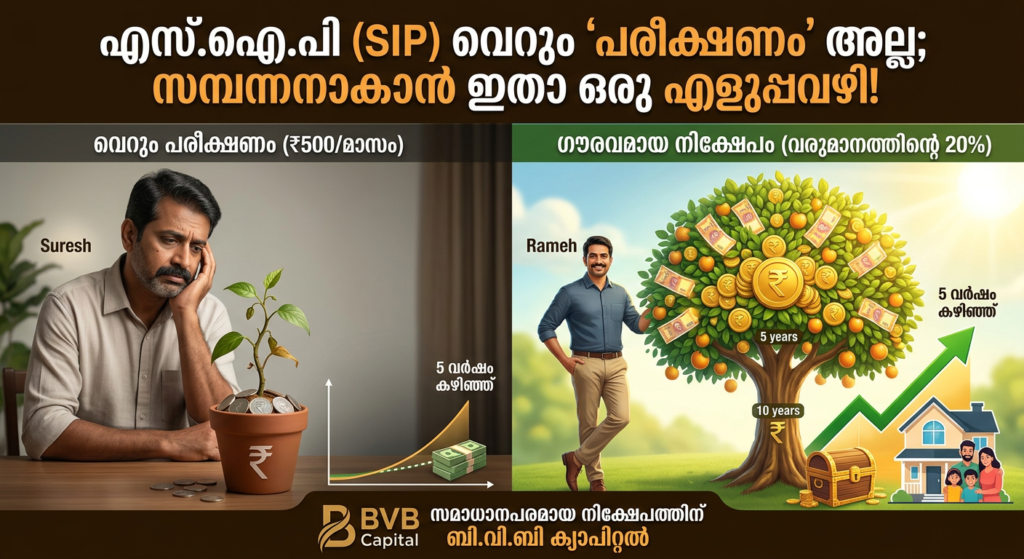
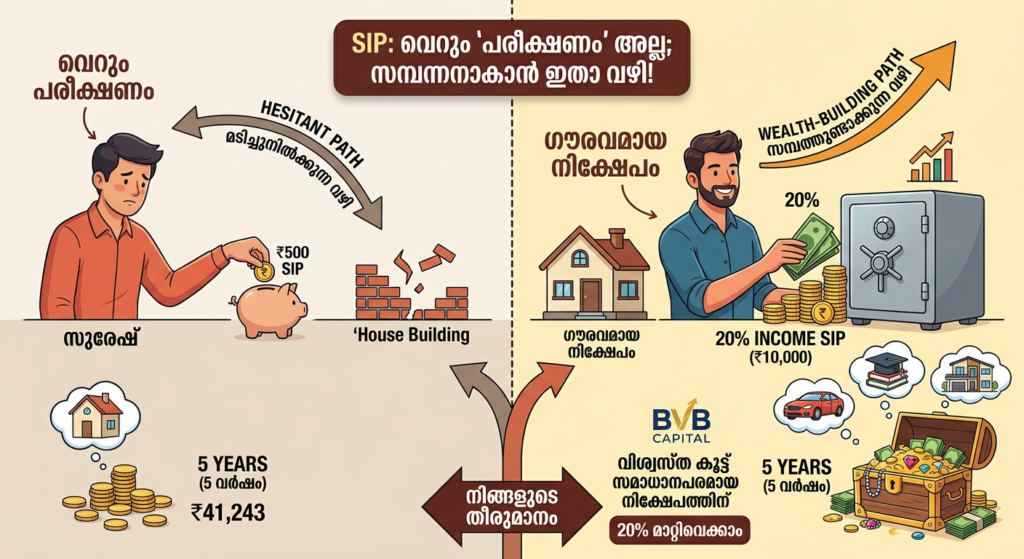
    നമുക്ക് എറണാകുളത്ത് ജോലി ചെയ്യുന്ന സുരേഷിന്റെ കാര്യമെടുക്കാം. സുരേഷിന് മാസം 50,000 രൂപ ശമ്പളമുണ്ട്. വീട്ടുചിലവുകൾ കഴിഞ്ഞ് 15,000 രൂപയോളം സുരേഷിന് ലാഭിക്കാം. പക്ഷേ, സുരേഷ് കരുതിയത് “നമുക്ക് പതുക്കെ തുടങ്ങാം, ആദ്യം ഒരു 500 രൂപയിട്ട് 5 വർഷം നോക്കാം” എന്നാണ്.

    അഞ്ചു വർഷം കഴിഞ്ഞു. സുരേഷിന്റെ കയ്യിൽ ലാഭം ഉൾപ്പെടെ ഏകദേശം 41,000 രൂപയുണ്ട്. എന്നാൽ സുരേഷിന്റെ സുഹൃത്ത് രമേശ് ചെയ്തത് മറ്റൊന്നാണ്. രമേശും അതേ ശമ്പളക്കാരനാണ്. പക്ഷേ അദ്ദേഹം തന്റെ വരുമാനത്തിന്റെ 20% (അതായത് 10,000 രൂപ) ഗൗരവമായ ഒരു നിക്ഷേപമായി മാറ്റി.

    അഞ്ചു വർഷം കഴിഞ്ഞപ്പോൾ രമേശിന്റെ കയ്യിലുള്ളത് ഏകദേശം 8.2 ലക്ഷം രൂപയാണ്! സുരേഷ് ഇപ്പോഴും ‘പരീക്ഷിച്ചു’ കൊണ്ടിരിക്കുന്നു, എന്നാൽ രമേശ് തന്റെ അടുത്ത ലക്ഷ്യത്തിലേക്ക് (ഒരു പുതിയ വീട്) എത്തിക്കഴിഞ്ഞു. സുരേഷിന് നഷ്ടപ്പെട്ടത് ആ 5 വർഷത്തെ ‘കോമ്പൗണ്ടിംഗ്’ കരുത്താണ്.


    20% of your income should be in SIP

    എന്തുകൊണ്ട് നിങ്ങളുടെ വരുമാനത്തിന്റെ 20% നിക്ഷേപിക്കണം?

    നിങ്ങൾ ഗൗരവമായി പണം സമ്പാദിക്കാൻ ആഗ്രഹിക്കുന്നുണ്ടെങ്കിൽ, നിങ്ങളുടെ ആകെ വരുമാനത്തിന്റെ അല്ലെങ്കിൽ സമ്പാദ്യത്തിന്റെ കുറഞ്ഞത് 20 ശതമാനമെങ്കിലും നിക്ഷേപത്തിലേക്ക് മാറ്റിവെക്കണം.

    നമുക്കൊന്ന് താരതമ്യം ചെയ്തു നോക്കാം (12% വാർഷിക വളർച്ച കണക്കാക്കിയാൽ):

    നിക്ഷേപ രീതിമാസ നിക്ഷേപം5 വർഷം കഴിഞ്ഞുള്ള തുക10 വർഷം കഴിഞ്ഞുള്ള തുക
    വെറും പരീക്ഷണം (Test)₹500₹41,243₹1,16,169
    ഗൗരവമായ നിക്ഷേപം (20%)₹5,000₹4,12,432₹11,61,695
    വലിയ നിക്ഷേപം₹10,000₹8,24,864₹23,23,391

    നോക്കൂ, 500 രൂപയുടെ പരീക്ഷണം കൊണ്ട് നിങ്ങൾക്ക് 10 വർഷം കഴിഞ്ഞാലും വലിയൊരു തുകയിലെത്താൻ കഴിയില്ല. എന്നാൽ 20% സമ്പാദ്യമെങ്കിലും നിക്ഷേപിക്കാൻ നിങ്ങൾ കാണിക്കുന്ന ധൈര്യം നിങ്ങളെ ഒരു കോടീശ്വരനാക്കി മാറ്റാൻ കെൽപ്പുള്ളതാണ്.

    DO NOT TEST SIP AND WASTE TIME

    എവിടെ തുടങ്ങണം? എങ്ങനെയുള്ള ആശയക്കുഴപ്പങ്ങൾ മാറ്റാം?

    പലരും നിക്ഷേപം തുടങ്ങാൻ മടിക്കുന്നത് പണം ഇല്ലാത്തതുകൊണ്ടല്ല, മറിച്ച് ഇതിന്റെ പുറകിലുള്ള നൂലാമാലകൾ പേടിച്ചാണ്.

    • “ഏത് ഫണ്ട് തിരഞ്ഞെടുക്കണം?”
    • “കെ.വൈ.സി (KYC) എങ്ങനെ ചെയ്യും?”
    • “വിപണി താഴേക്ക് പോയാൽ എന്ത് ചെയ്യും?” ഈ സംശയങ്ങൾ കാരണം പലരും നിക്ഷേപം മാറ്റിവെക്കുന്നു. ഇവിടെയാണ് BVB Capital നിങ്ങളുടെ സഹായത്തിനെത്തുന്നത്.

    BVB Capital: സമാധാനപരമായ നിക്ഷേപത്തിന് ഒരു വിശ്വസ്ത കൂട്ട്

    നിക്ഷേപം എന്നത് വെറും കണക്കുകൂട്ടലുകൾ മാത്രമല്ല, അതൊരു ദീർഘകാല ബന്ധമാണ്. BVB Capital ലൂടെ നിക്ഷേപം ആരംഭിക്കുമ്പോൾ നിങ്ങൾക്ക് ലഭിക്കുന്ന ഗുണങ്ങൾ ഇവയാണ്:

    1. സങ്കീർണ്ണമായ KYC നടപടികൾ ഞങ്ങൾ ഏറ്റെടുക്കുന്നു: പേപ്പർ വർക്കുകളെക്കുറിച്ചോ ഓൺലൈൻ അപ്‌ഡേഷനുകളെക്കുറിച്ചോ നിങ്ങൾ ആകുലപ്പെടേണ്ടതില്ല. നിങ്ങളുടെ കെ.വൈ.സി നടപടികൾ ലളിതമായി പൂർത്തിയാക്കാൻ ബി.വി.ബി ക്യാപിറ്റൽ നിങ്ങളെ സഹായിക്കുന്നു.
    2. ശരിയായ ഫണ്ട് തിരഞ്ഞെടുക്കാം: ആയിരക്കണക്കിന് മ്യൂച്വൽ ഫണ്ട് സ്കീമുകളിൽ നിന്ന് നിങ്ങളുടെ സാമ്പത്തിക ലക്ഷ്യങ്ങൾക്കും വരുമാനത്തിനും അനുയോജ്യമായവ തിരഞ്ഞെടുക്കാൻ ഞങ്ങളുടെ വിദഗ്ധ സംഘം നിങ്ങളെ സഹായിക്കുന്നു.
    3. ദീർഘകാല ബന്ധം: നിക്ഷേപം തുടങ്ങുന്നതിലല്ല, അത് കൃത്യമായി കൊണ്ടുപോകുന്നതിലാണ് കാര്യം. വിപണിയിലെ കയറ്റിറക്കങ്ങളിൽ പേടിക്കാതെ, സമാധാനത്തോടെ നിക്ഷേപം തുടരാൻ ഒരു കൈത്താങ്ങായി ബി.വി.ബി ക്യാപിറ്റൽ എപ്പോഴും കൂടെയുണ്ടാകും.
    4. സമാധാനപരമായ നിക്ഷേപം (Peaceful Investing): വിപണിയെക്കുറിച്ചോ ഇൻഡക്സിനെക്കുറിച്ചോ ഓരോ നിമിഷവും വ്യാകുലപ്പെടേണ്ടതില്ല. പ്രൊഫഷണലായ ഗൈഡൻസ് ഉള്ളപ്പോൾ നിങ്ങൾക്ക് നിങ്ങളുടെ ജോലിയിലും കുടുംബത്തിലും ശ്രദ്ധ കേന്ദ്രീകരിക്കാം, നിങ്ങളുടെ പണം ഞങ്ങൾക്കായി പണിയെടുക്കും.

    മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപകർ ശ്രദ്ധിക്കേണ്ട കാര്യങ്ങൾ (AMFI Guidelines)

    നിക്ഷേപം തുടങ്ങുന്നതിന് മുൻപ് ഈ കാര്യങ്ങൾ മറക്കരുത്:

    1. വിപണി അപകടസാധ്യതകൾ: മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപങ്ങൾ വിപണി അപകടസാധ്യതകൾക്ക് വിധേയമാണ്. വിപണിയിലെ മാറ്റങ്ങൾ നിങ്ങളുടെ നിക്ഷേപത്തെ ബാധിച്ചേക്കാം. സ്കീം സംബന്ധിച്ച എല്ലാ രേഖകളും ശ്രദ്ധാപൂർവം വായിക്കുക.
    2. ഗ്യാരണ്ടി ഇല്ല: മ്യൂച്വൽ ഫണ്ട് ഒരു ബാങ്ക് ഡെപ്പോസിറ്റ് അല്ല. മുൻകാല പ്രകടനം ഭാവിയിൽ ആവർത്തിക്കണമെന്നുമില്ല.
    3. വിദഗ്ധ ഉപദേശം: എപ്പോഴും ഒരു സെബി (SEBI) രജിസ്റ്റേർഡ് ഫിനാൻഷ്യൽ അഡ്വൈസറുടെ സഹായത്തോടെ മാത്രം നിക്ഷേപം നടത്തുക.

    ഇനി വൈകിക്കേണ്ട, ആ 20% മാറ്റിവെക്കാം

    നിങ്ങളുടെ സമ്പാദ്യത്തിന്റെ 20% ഗൗരവമായ ഒരു നിക്ഷേപമായി മാറ്റാൻ ഇതാണ് ഏറ്റവും നല്ല സമയം. 500 രൂപയുടെ ‘ടെസ്റ്റ് ഡ്രൈവ്’ നടത്തിക്കൊണ്ടിരുന്നാൽ നിങ്ങൾ ലക്ഷ്യസ്ഥാനത്ത് എത്തില്ല.

    BVB Capital മായി കൈകോർത്ത്, എല്ലാ സാങ്കേതിക ബുദ്ധിമുട്ടുകളും ഞങ്ങൾക്ക് വിട്ടുനൽകി, ആത്മവിശ്വാസത്തോടെ നിങ്ങളുടെ സാമ്പത്തിക ഭദ്രതയിലേക്കുള്ള യാത്ര തുടങ്ങൂ. സമാധാനപരമായ ഒരു നിക്ഷേപത്തിലൂടെ നിങ്ങളുടെ സ്വപ്നങ്ങൾ സാക്ഷാത്കരിക്കാൻ ഞങ്ങൾ കൂടെയുണ്ട്.

    സന്തോഷകരമായ നിക്ഷേപയാത്ര നേരുന്നു!


    Disclaimer: Mutual Fund നിക്ഷേപങ്ങൾ വിപണി അപകടസാധ്യതകൾക്ക് വിധേയമാണ്. സ്കീം സംബന്ധിച്ച എല്ലാ രേഖകളും ശ്രദ്ധാപൂർവം വായിക്കുക. മുകളിൽ നൽകിയിരിക്കുന്ന കണക്കുകൾ ഒരു ധാരണയ്ക്ക് വേണ്ടിയുള്ള ഉദാഹരണങ്ങൾ മാത്രമാണ്.

    നിങ്ങളുടെ സമ്പാദ്യത്തിന്റെ 20% എങ്ങനെ കൃത്യമായി നിക്ഷേപിക്കണം എന്ന് അറിയാൻ ബി.വി.ബി ക്യാപിറ്റലുമായി (BVB Capital) ബന്ധപ്പെടാൻ ആഗ്രഹിക്കുന്നുണ്ടോ? Contact us

  • Is ₹500 SIP for 5 Years Enough? Let’s Understand the Reality

    Is ₹500 SIP for 5 Years Enough? Let’s Understand the Reality

    Many new investors ask:

    👉 “If I invest ₹500 per month in SIP, what will I get after 5 years?”

    Let’s understand this with a simple example.
    If you are new to SIP, first understand how it works in detail.


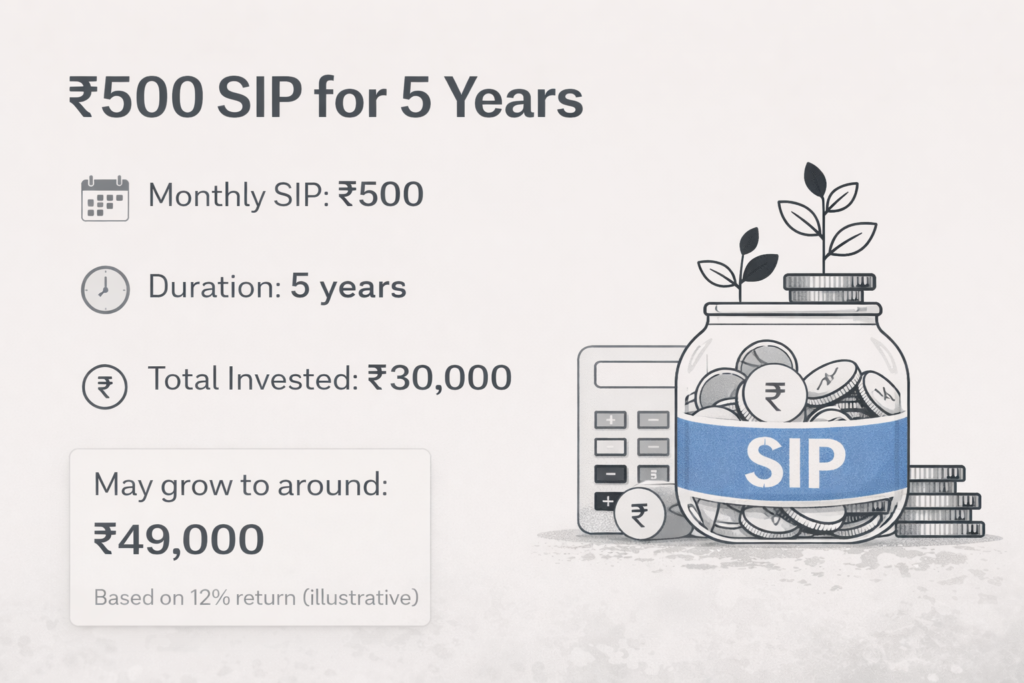
    📊 Example: ₹500 SIP for 5 Years

    • Monthly SIP: ₹500
    • Duration: 5 years
    • Total invested: ₹30,000

    👉 Based on an assumed return of 12% per annum,
    the value may grow to around ₹49,000

    👉 Gain: ~₹19,000


    ⚠️ Important Note

    This is only an illustration, not a guarantee.

    • Mutual fund returns are market-linked
    • Actual returns may be higher or lower
    • This example is used only to help understand how SIP works

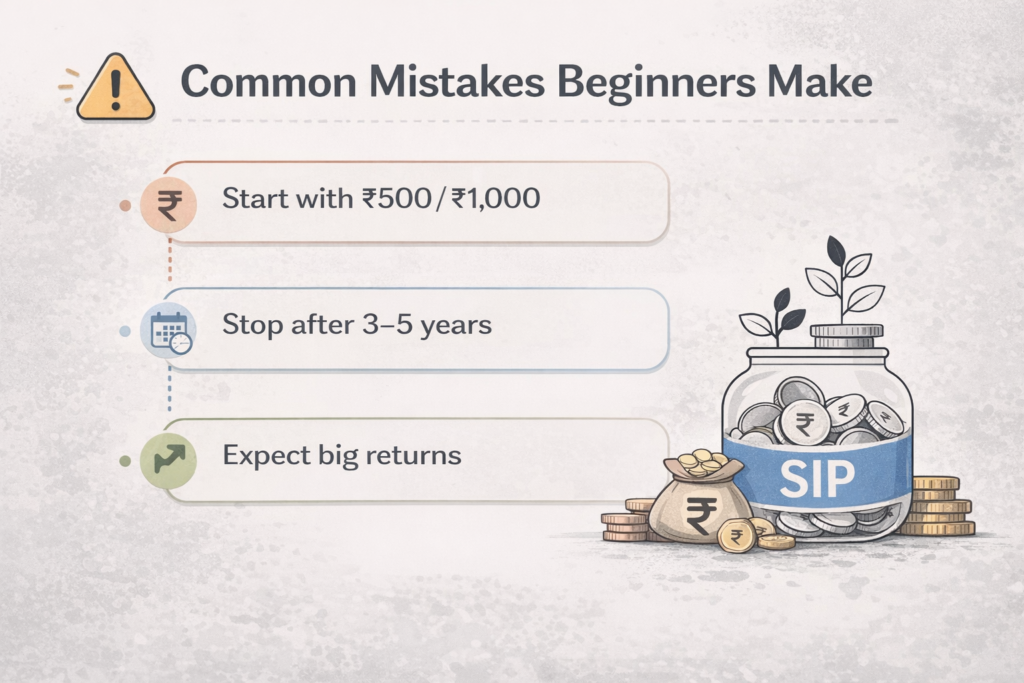
    Common SIP investment mistakes for beginners

    🤔 What Does This Mean?

    A ₹500 SIP helps you:
    ✔ Start investing
    ✔ Build financial discipline

    But:

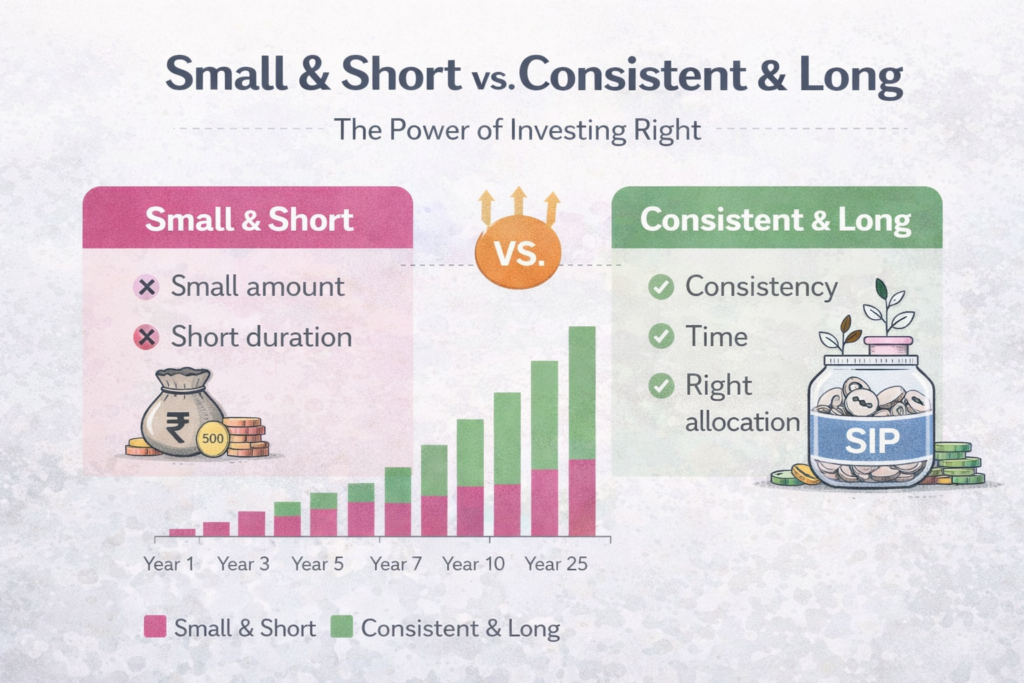
    👉 For meaningful wealth creation, both amount and time matter


    📈 The Role of Time in Investing

    Let’s see what happens when you stay invested longer:

    SIPDurationValue (Illustrative @12%)
    ₹5005 years~₹49,000
    ₹50020 years~₹9.9 Lakhs
    ₹50030 years~₹44 Lakhs

    👉 Same SIP… but longer duration shows the impact of compounding.


    Investing strategies: short-term vs long-term

    🚀 Increasing SIP Over Time (Step-Up SIP)

    In real life, income increases over time.
    So investors can consider increasing SIP annually.

    👉 In the projections shown here,
    we have assumed a 10% annual increase (top-up) in SIP amount

    This approach is called:

    👉 Step-Up SIP

    It can significantly improve long-term outcomes.


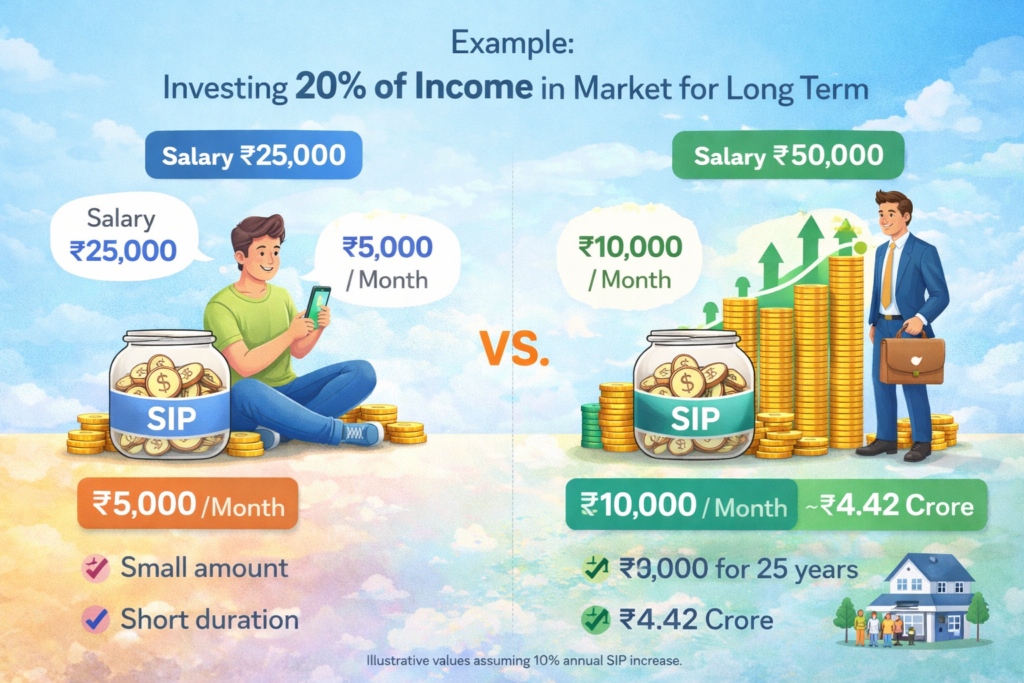
    📊 Example: ₹5,000 SIP with 10% Yearly Increase

    • ₹5,000 for 15 years → ~₹43 Lakhs
    • ₹5,000 for 25 years → ~₹2.14 Crore
    • ₹5,000 for 30 years → ~₹4.42 Crore

    (All values are illustrative, assuming 12% annual return and 10% SIP increase per year)


    💡 Key Takeaways

    ✔ Starting small is good
    ✔ Staying invested is more important
    ✔ Increasing SIP over time can improve results
    ✔ Long-term investing helps benefit from compounding


    Stock market investment illustration for growth

    🎯 How Much Should You Invest?

    A common thumb rule:

    👉 Try to invest a portion of your income regularly
    (For many investors, this may range around 10–20%, depending on their situation)

    Always invest based on:

    • Income
    • Expenses
    • Financial goals
    • Risk capacity

    ⚠️ Avoid These Common Mistakes

    ❌ Investing only based on small trial amounts
    ❌ Stopping SIPs during market fluctuations
    ❌ Selecting funds based only on past returns


    🧠 Why Proper Guidance Matters

    Mutual fund investing is not just about starting an SIP.

    It involves:

    • Understanding your risk profile
    • Selecting suitable asset allocation
    • Choosing appropriate schemes
    • Staying consistent during market ups and downs

    🤝 How BVB Capital Can Help

    At BVB Capital, we focus on:

    ✔ Risk profiling before investment
    ✔ Goal-based portfolio construction
    ✔ Suitable scheme selection (not random picking)
    ✔ Long-term investment discipline

    👉 The aim is to help investors make informed and structured decisions


    🔚 Final Thought

    SIP is a powerful tool when used correctly.

    👉 Start early
    👉 Stay consistent
    👉 Increase gradually
    👉 Think long term


    📞 Get Started

    If you want to plan your SIP based on your goals and risk profile:

    👉 Connect with BVB Capital for a structured approach to investing


    ⚖️ Mandatory Disclaimer (AMFI-Compliant)

    Mutual Fund investments are subject to market risks.
    Read all scheme related documents carefully before investing.
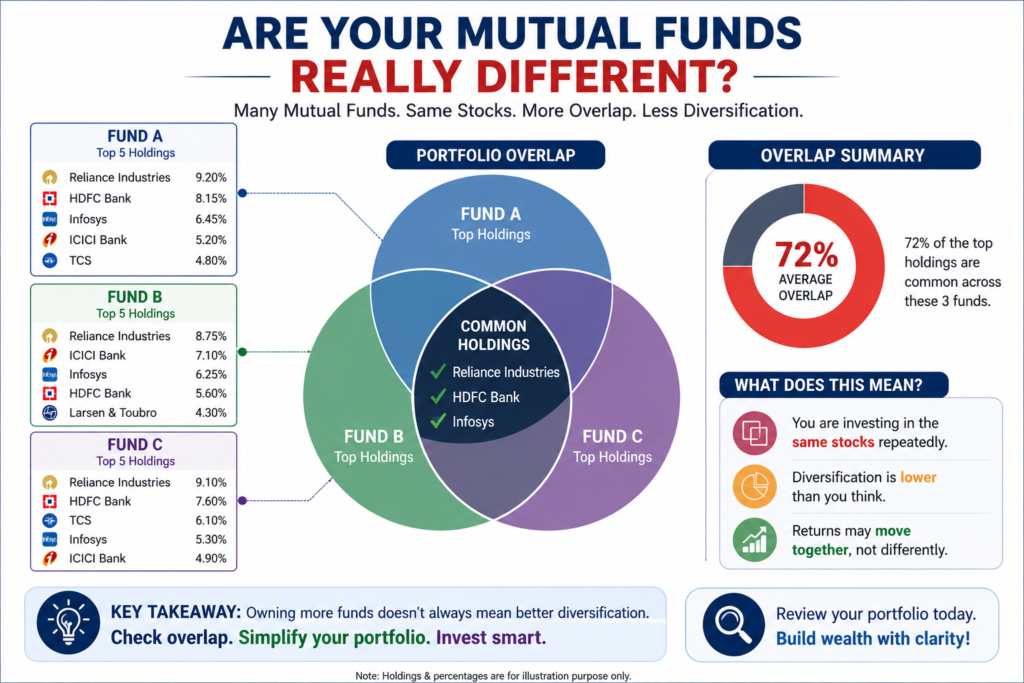
    The returns shown above are illustrative and are based on assumed rates of return.
    They are not guaranteed and do not indicate future performance.

  • മ്യൂച്വൽ ഫണ്ടിൽ എത്ര കാലം നിക്ഷേപിക്കണം?

    മ്യൂച്വൽ ഫണ്ടിൽ എത്ര കാലം നിക്ഷേപിക്കണം?

    നമ്മളിൽ പലരും ചോദിക്കാറുള്ള ഒരു പ്രധാന ചോദ്യമാണ്, “ഈ മ്യൂച്വൽ ഫണ്ടിൽ എത്ര കാലം പണം ഇട്ടു വെക്കണം?” എന്നത്. ഒരു പ്ലാവു നട്ടാൽ ഉടനെ ചക്ക കിട്ടില്ലല്ലോ, അതുപോലെ തന്നെയാണ് നിക്ഷേപവും. ഇന്ന് നമുക്ക് വളരെ ലളിതമായി, നമ്മുടെ വീട്ടിലെ കാര്യങ്ങൾ പറയുന്നതുപോലെ ഈ നിക്ഷേപ കാലാവധിയെക്കുറിച്ച് ഒന്ന് സംസാരിക്കാം.

    മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപത്തെക്കുറിച്ച് കേൾക്കുമ്പോൾ തന്നെ പലർക്കും പേടിയാണ്. എന്നാൽ ശരിയായ സമയവും കൃത്യമായ പ്ലാനിംഗും ഉണ്ടെങ്കിൽ ഇതൊരു വലിയ നിധിശേഖരം തന്നെയാണ്. നിക്ഷേപ കാലാവധി അഥവാ ‘ഇൻവെസ്റ്റ്‌മെന്റ് ഹൊറൈസൺ’ എങ്ങനെ തിരഞ്ഞെടുക്കാം എന്ന് നമുക്ക് നോക്കാം.
    മ്യൂച്വൽ ഫണ്ട് എന്നാൽ എന്താണെന്ന്” കൂടുതൽ അറിയാൻ ഈ ലിങ്ക് നോക്കാം.

    A multi-generational Kerala family gathers around a laptop in their traditional home to discuss and visualize their mutual fund investment goals, represented by thought bubbles illustrating education, travel, a car, and retirement planning

    എന്താണ് ഈ ഇൻവെസ്റ്റ്‌മെന്റ് ഹൊറൈസൺ (Investment Horizon)?

    ലളിതമായി പറഞ്ഞാൽ, നിങ്ങൾ എത്ര കാലത്തേക്ക് നിങ്ങളുടെ പണം നിക്ഷേപിക്കാൻ ഉദ്ദേശിക്കുന്നു എന്നതിനെയാണ് ഇൻവെസ്റ്റ്‌മെന്റ് ഹൊറൈസൺ എന്ന് വിളിക്കുന്നത്. നമ്മൾ ഒരു വീട് പണിയാൻ പണം മാറ്റിവെക്കുന്നത് പോലെയല്ല ഒരു മൊബൈൽ ഫോൺ വാങ്ങാൻ പണം കരുതുന്നത്. ഓരോ ആവശ്യത്തിനും ഓരോ സമയമുണ്ട്.

    നിങ്ങളുടെ ലക്ഷ്യം എന്താണെന്ന് ആദ്യം തീരുമാനിക്കുക. ഉദാഹരണത്തിന്, അടുത്ത വർഷം നടത്തേണ്ട ഒരു വിനോദയാത്രയാണോ അതോ പത്തു വർഷം കഴിഞ്ഞ് നടക്കേണ്ട മകളുടെ വിവാഹമാണോ? ഈ സമയത്തിനനുസരിച്ചാണ് നമ്മൾ ഏത് ഫണ്ട് വേണമെന്ന് തീരുമാനിക്കുന്നത്.

    A split-screen illustration contrasting short-term (1-3 years) and long-term (5+ years) mutual fund investment paths. The short-term side features a calm road with a father driving a car representing stable debt funds, while the long-term side shows a mother driving a jeep on a steep, winding mountain road representing volatile but high-growth equity funds, with labels in both Malayalam and English.

    ഹ്രസ്വകാലം vs ദീർഘകാലം: എവിടെ എപ്പോൾ നിക്ഷേപിക്കണം?

    നിക്ഷേപ കാലാവധിയെ നമുക്ക് പ്രധാനമായും മൂന്നായി തിരിക്കാം. ഇതിലൂടെ നിങ്ങൾക്ക് അനുയോജ്യമായത് ഏതാണെന്ന് എളുപ്പത്തിൽ മനസ്സിലാക്കാം.

    1. കുറഞ്ഞ കാലയളവ് (Short-term: 1 മുതൽ 3 വർഷം വരെ)

    നിങ്ങൾക്ക് പെട്ടെന്ന്, അതായത് ഒന്നോ രണ്ടോ വർഷത്തിനുള്ളിൽ പണം ആവശ്യമുണ്ടെങ്കിൽ ‘ഡെറ്റ് ഫണ്ടുകൾ’ (Debt Funds) അല്ലെങ്കിൽ ‘ലിക്വിഡ് ഫണ്ടുകൾ’ തിരഞ്ഞെടുക്കുന്നതാണ് ബുദ്ധി. ഓഹരി വിപണിയിലെ ചാഞ്ചാട്ടം ഇവയെ കാര്യമായി ബാധിക്കില്ല.

    • ഉദാഹരണം: വീട് പെയിന്റ് അടിക്കാനോ അല്ലെങ്കിൽ ഒരു ചെറിയ ടൂർ പോകാനോ ഉള്ള പണം.

    2. ഇടത്തരം കാലയളവ് (Medium-term: 3 മുതൽ 5 വർഷം വരെ)

    മൂന്ന് വർഷത്തിന് മുകളിൽ അഞ്ച് വർഷം വരെയുള്ള ആവശ്യങ്ങൾക്കാണെങ്കിൽ ‘ഹൈബ്രിഡ് ഫണ്ടുകൾ’ (Hybrid Funds) നോക്കാവുന്നതാണ്. ഇതിൽ പണം ഓഹരികളിലും കടപ്പത്രങ്ങളിലും ഒരുപോലെ നിക്ഷേപിക്കുന്നു.

    • ഉദാഹരണം: കാർ വാങ്ങാനുള്ള ഡൗൺ പേയ്‌മെന്റ് കണ്ടെത്താൻ.

    3. ദീർഘകാലം (Long-term: 5 വർഷത്തിന് മുകളിൽ)

    അഞ്ച് വർഷത്തിന് മുകളിലാണ് നിങ്ങളുടെ പ്ലാനെങ്കിൽ കണ്ണും പൂട്ടി ‘ഇക്വിറ്റി ഫണ്ടുകൾ’ (Equity Funds) തിരഞ്ഞെടുക്കാം. ഇവിടെയാണ് യഥാർത്ഥ മാജിക് നടക്കുന്നത്!

    • ഉദാഹരണം: മക്കളുടെ ഉന്നത പഠനം, നിങ്ങളുടെ റിട്ടയർമെന്റ് ജീവിതം.
    നിക്ഷേപ കാലാവധിഫണ്ട് തരംറിസ്ക് നിലവാരം
    1 വർഷത്തിൽ താഴെലിക്വിഡ് ഫണ്ടുകൾവളരെ കുറവ്
    1 – 3 വർഷംഡെറ്റ് ഫണ്ടുകൾകുറവ്
    3 – 5 വർഷംഹൈബ്രിഡ് / ബാലൻസ്ഡ് ഫണ്ടുകൾമിതത്വം
    5 വർഷത്തിന് മുകളിൽഇക്വിറ്റി ഫണ്ടുകൾകൂടുതൽ (പക്ഷേ ലാഭവും കൂടുതൽ)
    A sequential, four-panel illustration showing a Kerala family and a jackfruit tree growing over 30+ years, visually demonstrating the power of compounding as a small initial seedling and investment multiply into a monumental tree dripping with coins and wealth by year 30, with time stages labeled in Malayalam.

    ഡെറ്റ് ഫണ്ടുകളും ഇക്വിറ്റി ഫണ്ടുകളും തമ്മിലുള്ള വ്യത്യാസം

    പലരും തെറ്റായ ഫണ്ടുകളിൽ പണം നിക്ഷേപിച്ച് പിന്നീട് നഷ്ടം വന്നു എന്ന് പരാതിപ്പെടാറുണ്ട്. നിങ്ങൾ ഹ്രസ്വകാലത്തേക്ക് ഇക്വിറ്റി ഫണ്ടിൽ പണം ഇട്ടാൽ, വിപണി താഴേക്ക് പോകുമ്പോൾ നിങ്ങളുടെ പണം കുറയാൻ സാധ്യതയുണ്ട്.

    • ഡെറ്റ് ഫണ്ടുകൾ: പണം സുരക്ഷിതമായിരിക്കാൻ ആഗ്രഹിക്കുന്നവർക്ക്. ബാങ്ക് എഫ്.ഡി യേക്കാൾ അല്പം കൂടി മികച്ച ലാഭം പ്രതീക്ഷിക്കാം.
    • ഇക്വിറ്റി ഫണ്ടുകൾ: വിപണിയിലെ ലാഭവിഹിതം വേണം എന്നുള്ളവർക്ക്. ദീർഘകാലം കാത്തിരുന്നാൽ വലിയൊരു തുക സമ്പാദിക്കാൻ ഇത് സഹായിക്കും.

    കൂട്ടുപലിശയുടെ മാന്ത്രികത (Power of Compounding)

    നിങ്ങൾ എത്ര കൂടുതൽ കാലം നിക്ഷേപം തുടരുന്നുവോ, അത്രയും വലിയ ലാഭം നിങ്ങൾക്ക് ലഭിക്കും. ഇതിനെയാണ് ഐൻസ്റ്റീൻ ലോകത്തിലെ എട്ടാമത്തെ അത്ഭുതം എന്ന് വിളിച്ചത്. നിങ്ങൾ ഇന്ന് നിക്ഷേപിക്കുന്ന 1000 രൂപ പത്തു വർഷം കഴിയുമ്പോൾ ലഭിക്കുന്നതിനേക്കാൾ വലിയ തുകയായി ഇരുപതു വർഷം കഴിയുമ്പോൾ മാറും. ഇതിനെക്കുറിച്ച് കൂടുതൽ അറിയാൻ ഇതുമായി ബന്ധപ്പെട്ട് ഈ ലേഖനം വായിക്കാം.

    ശ്രദ്ധിക്കേണ്ട 3 കാര്യങ്ങൾ:

    1. ക്ഷമ വേണം: വിപണി താഴേക്ക് പോകുമ്പോൾ പേടിച്ച് പണം പിൻവലിക്കരുത്.
    2. SIP തുടങ്ങുക: എല്ലാ മാസവും ചെറിയ തുക നിക്ഷേപിക്കുന്ന ശീലം വളർത്തുക.
    3. ലക്ഷ്യം മറക്കരുത്: എന്തിനുവേണ്ടിയാണ് നിക്ഷേപിക്കുന്നത് എന്ന കൃത്യമായ ബോധ്യം വേണം.
      എന്താണ് SIP എന്നും അത് എങ്ങനെ തുടങ്ങാം എന്നും” ഇവിടെ വായിക്കാം.
    A square social media infographic featuring bold Malayalam text asking "Mutual Fund: How long for your goal?". The central focus is a treasure chest with a watch face displaying different investment durations (1, 5, and 10+ years) in Malayalam, surrounded by money and goal icons, with a call to action to start investing below.

    സമാപനം

    ചുരുക്കത്തിൽ പറഞ്ഞാൽ, മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപം എന്നത് ഒരു ഓട്ടമത്സരമല്ല, മറിച്ച് ഒരു ദീർഘദൂര യാത്രയാണ്. നിങ്ങളുടെ സാമ്പത്തിക ലക്ഷ്യങ്ങൾക്കനുസരിച്ച് ശരിയായ ഫണ്ട് തിരഞ്ഞെടുക്കുക. ഇന്ന് തന്നെ ചെറിയ രീതിയിൽ തുടങ്ങൂ, നാളെ അത് വലിയൊരു തണലായി മാറും.

    നിങ്ങൾക്ക് ഇതിനെക്കുറിച്ച് എന്തെങ്കിലും സംശയമുണ്ടോ? താഴെ കമന്റ് ചെയ്യൂ, നമുക്ക് സംസാരിക്കാം!


    ഇടയ്ക്കിടെ ചോദിക്കപ്പെടുന്ന ചോദ്യങ്ങൾ (FAQ)

    1. മ്യൂച്വൽ ഫണ്ടിൽ നിന്ന് എപ്പോൾ വേണമെങ്കിലും പണം പിൻവലിക്കാമോ?

    അതെ, മിക്കവാറും എല്ലാ ഓപ്പൺ എൻഡഡ് ഫണ്ടുകളിൽ നിന്നും നിങ്ങൾക്ക് എപ്പോൾ വേണമെങ്കിലും പണം പിൻവലിക്കാം. എന്നാൽ ചില ഫണ്ടുകളിൽ ഒരു വർഷത്തിനുള്ളിൽ പിൻവലിച്ചാൽ ചെറിയൊരു തുക (Exit Load) ഈടാക്കാറുണ്ട്.

    2. എത്ര രൂപ മുതൽ നിക്ഷേപം തുടങ്ങാം?

    വെറും 500 രൂപ മുതൽ നിങ്ങൾക്ക് SIP വഴി നിക്ഷേപം തുടങ്ങാവുന്നതാണ്. വലിയ തുക വേണമെന്ന് നിർബന്ധമില്ല.

    3. ഓഹരി വിപണി തകർന്നാൽ എന്റെ പണം നഷ്ടപ്പെടുമോ?

    വിപണി താഴേക്ക് പോകുമ്പോൾ താല്ക്കാലികമായി മൂല്യം കുറയാം. എന്നാൽ ദീർഘകാലം (5-10 വർഷം) നിക്ഷേപിക്കുന്നവർക്ക് വിപണി തിരിച്ചു വരുമ്പോൾ മികച്ച ലാഭം ലഭിക്കാറുണ്ട്.

    4. ടാക്സ് സേവിംഗ് ഫണ്ടുകൾ (ELSS) എത്ര കാലം വെക്കണം?

    ELSS ഫണ്ടുകൾക്ക് 3 വർഷത്തെ ലോക്ക്-ഇൻ പിരീഡ് ഉണ്ട്. അതായത് 3 വർഷം തികയാതെ നിങ്ങൾക്ക് പണം പിൻവലിക്കാൻ കഴിയില്ല.
    ആദായനികുതി ഇളവുകളെക്കുറിച്ചുള്ള നിയമങ്ങൾ” ഇവിടെ പരിശോധിക്കാം.

    5. ഏത് ഫണ്ടാണ് എനിക്ക് നല്ലതെന്ന് എങ്ങനെ അറിയാം?

    നിങ്ങളുടെ പ്രായം, സാമ്പത്തിക ലക്ഷ്യം, എത്ര കാലം കാത്തിരിക്കാൻ കഴിയും എന്നിവ നോക്കി വേണം ഫണ്ട് തിരഞ്ഞെടുക്കാൻ. ഒരു സാമ്പത്തിക ഉപദേഷ്ടാവിന്റെ സഹായം തേടുന്നത് എപ്പോഴും നല്ലതാണ്.

    നിക്ഷേപകരുടെ അറിവിലേക്കായി “AMFI നൽകുന്ന മാർഗ്ഗനിർദ്ദേശങ്ങൾ” ശ്രദ്ധിക്കുക.

  • 📞 “Sir, when will I get my money back?” – The Most Common Question We Hear

    📞 “Sir, when will I get my money back?” – The Most Common Question We Hear

    Almost every day at BVB Capital Private Limited, we receive calls like this:

    “I want to invest in mutual funds… but how long should I invest?”
    “If I put money today, when can I take it back?”
    “Is it like a fixed deposit?”

    If you’ve ever had these questions, you’re not alone.

    In fact, this is exactly how most new investors begin their journey—with curiosity, confusion, and a little bit of fear.
    At BVB Capital Private Limited, we regularly guide new investors who are just starting their journey.


    🤔 The Real Problem: Investing Without Understanding

    Many people come to mutual funds expecting:

    • Quick returns
    • Fixed timelines
    • Guaranteed profits

    But mutual funds don’t work like that.

    Mutual fund investing is not about:

    • “Putting money today and taking it out next month”

    It is about:

    • Growing your wealth over time
    Mutual fund distributor explaining basics like SIP, risk and returns, and market fluctuations to a new investor

    ⏳ So, How Long Should You Invest?

    Here’s the simple truth:

    👉 Your investment duration depends on your goal, not the product.

    Let’s make it easy:

    • 🏠 Buying a house → 5 to 10 years
    • 🎓 Children’s education → 10 to 15 years
    • 💰 Wealth creation → 10+ years
    • 📆 Short-term needs → Less than 3 years (different strategy)

    Mutual funds reward patience, not urgency.
    If you are completely new, you can start by understanding the basics of mutual funds here : mutual fund basics


    Comparison of mutual fund investment methods including SIP, lump sum, and hybrid options explained to a beginner investor

    💡 Why Do People Ask “When Will I Get My Money?”

    Because nobody explained this clearly before.

    Most investors:

    • Start investing because someone told them to
    • Don’t understand risk and returns
    • Don’t know how SIP works
    • Don’t know when to enter or exit

    This leads to panic:

    • Market falls → they want to withdraw
    • Market rises → they want to invest more blindly

    Mutual fund selection process showing comparison of different funds with guidance from a financial advisor

    👨‍💼 That’s Where We Come In

    At BVB Capital Private Limited, we don’t just “sell mutual funds.”

    We guide you step by step:

    ✔️ We Help You Understand

    • What mutual funds actually are
    • How markets behave
    • Why patience is important

    ✔️ We Help You Decide

    • How much to invest
    • Which type of fund suits you
    • SIP or lump sum

    ✔️ We Help You Stay Disciplined

    • Avoid emotional decisions
    • Stay invested during market ups and downs
    • Track progress toward your goals

    💰 “How Much Should I Invest?”

    Another common question we hear.

    The answer is not:

    • “Invest ₹5,000 or ₹10,000”

    The real answer is:

    👉 Invest based on your income, expenses, and goals.

    At BVB Capital, we help you:

    • Analyze your financial situation
    • Identify your goals
    • Suggest a comfortable investment amount

    Even starting with ₹500 SIP is perfectly fine.

    What matters is:
    👉 Consistency, not amount
    Choosing the right SIP amount is crucial for long-term success SIP planning guide


    📊 Mutual Funds Are Simple—If Guided Properly

    Without guidance:

    • Confusion increases
    • Wrong choices happen
    • People exit early and lose potential gains

    With proper guidance:

    • Investing becomes easy
    • You stay confident
    • Wealth grows steadily

    🚀 Your First Step Matters

    If you are still asking:

    • “How long should I invest?”
    • “When will I get my money?”

    Then it’s the right time to learn before you invest.

    And you don’t have to figure it out alone.


    🤝 Let’s Start Your Investment Journey the Right Way

    At BVB Capital Private Limited, we believe:

    “Right guidance at the beginning can change your financial future.”

    Whether you are:

    • A beginner
    • A salaried professional
    • A business owner
    • Or someone who has never invested before

    We are here to guide you.
    Know more about how we help investors at BVB Capital Private Limited.


    📲 Take the First Step Today

    Send us a message on WhatsApp or call us.

    No complicated terms. No pressure. Just simple guidance.

    👉 Start small.
    👉 Stay consistent.
    👉 Grow your wealth.
    Start your investment journey with expert guidance today.