BVB CAPITAL PRIVATE LIMITED

AMFI-registered Mutual Fund Distributor

ARN: 348338

Tag: SIP

  • SIP Calculator – How Much Should You Invest Monthly to Reach Your Goal?

    SIP Calculator – How Much Should You Invest Monthly to Reach Your Goal?

    Most people start a SIP without knowing if ₹2,000 per month will actually get them where they want to go. They pick an amount that feels comfortable, choose a fund someone recommended, and hope for the best. Years later, they discover the number was never going to be enough.
    SIP CALCULATOR

    This guide — and the SIP calculator below — will tell you the exact monthly SIP amount for any goal, whether it is ₹25 lakh for your child’s college education, ₹1 crore for retirement, or a dream home down payment. You will also learn why the number changes dramatically based on when you start.

    At BVB Capital, we are an AMFI-registered mutual fund distributor (ARN 348338) based in Kerala. We help families across Kerala calculate and start SIPs every day. Everything in this article reflects real numbers and practical guidance we give our clients.

    SIP Goal Calculator

    ₹
    years
    %
    Gains
    Total Investment
    Total Invested
    ₹0
    Target Amount
    ₹50L
    Gains
    ₹0
    Monthly SIP Needed
    ₹0
    Wealth Multiplier: 0x
    *Mutual fund investments are subject to market risks. Past performance does not guarantee future returns. Returns shown are for illustration only.

    What Is a SIP and How Does the SIP Calculator Work?

    A Systematic Investment Plan (SIP) is a method of investing a fixed amount in a mutual fund at regular intervals — usually monthly. Instead of investing a large sum all at once, you invest smaller amounts over time. This approach is called rupee cost averaging: you buy more units when markets are low and fewer when markets are high, which reduces your average cost per unit over the long run.

    The SIP calculator uses the future value formula: FV = P × [((1+r)ⁿ – 1) / r] × (1+r), where P is your monthly SIP amount, r is the monthly return rate, and n is the total number of months. You do not need to understand the formula — the calculator handles all of this automatically.
    HOW TO ACHIVE SIP GOAL

    What you do need to understand is the assumption behind the number. The calculator uses an assumed annual return rate, typically 12% for equity mutual funds. Actual returns will vary depending on the fund you choose and market conditions. We always recommend using 11–12% for long-term equity SIP planning — conservative enough to be realistic, optimistic enough to reflect historical equity performance in India.

    Already know what SIP is? Jump straight to the goal calculator above. New to SIP? Read our complete guide: What Is SIP?

    How Much SIP Per Month for Your Goal? Real Calculations
    SIP CALCULATIONS

    The most common question we hear at BVB Capital is: ‘How much do I need to invest every month?’ The answer depends entirely on your goal, your time horizon, and when you start. Here are the real numbers for the most common financial goals among Kerala investors.

    SIP to Reach ₹50 Lakh

    Assuming a 12% annual return on a diversified equity mutual fund:

    • ₹50 lakh in 10 years → Monthly SIP needed: ~₹21,000
    • ₹50 lakh in 15 years → Monthly SIP needed: ~₹10,800
    • ₹50 lakh in 20 years → Monthly SIP needed: ~₹5,800

    Notice how waiting just 5 extra years cuts your required monthly SIP almost in half. This is the power of compounding — and it is the single most important reason to start today, not next month.

    SIP to Reach ₹1 Crore

    ₹1 crore is the most searched SIP goal in India. Here is what you actually need:

    • ₹1 crore in 10 years → Monthly SIP needed: ~₹43,000
    • ₹1 crore in 15 years → Monthly SIP needed: ~₹21,500
    • ₹1 crore in 20 years → Monthly SIP needed: ~₹11,600
    • ₹1 crore in 25 years → Monthly SIP needed: ~₹6,300

    If ₹43,000/month seems out of reach, starting earlier and giving yourself 20–25 years makes ₹1 crore very achievable — even on a modest income.

    SIP for Child’s Education (₹25 Lakh in 15 Years)

    If your child is under 3 years old today, you have roughly 15 years before college. ₹25 lakh covers a decent engineering or medical degree in Kerala today — though with education inflation, you may want to target ₹35–40 lakh.

    • ₹25 lakh in 15 years at 12% → Monthly SIP: ~₹5,400
    • ₹35 lakh in 15 years at 12% → Monthly SIP: ~₹7,500

    SIP for Retirement (₹2 Crore Corpus)

    If you are 35 years old and plan to retire at 60, you have 25 years. A ₹2 crore corpus — combined with SWP (Systematic Withdrawal Plan) — can give you roughly ₹80,000–90,000 per month in retirement income.

    • ₹2 crore in 25 years at 12% → Monthly SIP: ~₹14,000
    • ₹2 crore in 20 years at 12% → Monthly SIP: ~₹23,200

    Quick Reference: SIP amounts for common goals (at 12% annual return)

    GoalTarget AmountYearsReturnMonthly SIP
    Child’s education₹25 lakh15 years12%~₹5,400/month
    Car purchase₹15 lakh7 years12%~₹11,500/month
    Home down payment₹30 lakh10 years12%~₹13,400/month
    Retirement corpus₹2 crore25 years12%~₹14,000/month
    ₹50 lakh goal₹50 lakh20 years12%~₹5,800/month
    ₹1 crore goal₹1 crore20 years12%~₹11,600/month
    Know your number? Let’s find the right fund. WhatsApp ‘SIP Start’ to BVB Capital for a free consultation. We will match your goal, timeline, and risk appetite to the right mutual fund — at no cost to you.
    BVB Capital | ARN 348338 | SEBI Investor Awareness Certified | Kerala

    3 Factors That Change Your SIP Amount Dramatically

    Factor 1: When You Start (The Cost of Waiting)

    This is the biggest factor of all — and the one most people underestimate. Here is what it costs in monthly SIP amount to reach ₹1 crore by age 60, depending on when you begin:

    When You StartYears to 60ReturnMonthly SIP for ₹1 CrVerdict
    Start at 2535 years12%~₹3,500/monthMost affordable
    Start at 3030 years12%~₹6,000/monthManageable
    Start at 3525 years12%~₹10,500/monthGetting expensive
    Start at 4020 years12%~₹19,000/monthVery costly delay
    Start at 4515 years12%~₹35,000/monthExtremely difficult

    Starting at 25 instead of 35 saves you ₹7,000 per month — every single month — for 25 years. That is a ₹21 lakh difference in total investment, just because of a 10-year head start. Share this table with anyone who is ‘waiting for the right time’ to start investing.

    Factor 2: Expected Rate of Return

    The return rate you assume in the calculator dramatically changes the output. Here is how ₹5,000/month grows over 20 years at different return rates:

    • At 8% annual return: ₹29.4 lakh (debt funds, conservative)
    • At 10% annual return: ₹38.3 lakh (hybrid/balanced funds)
    • At 12% annual return: ₹49.9 lakh (diversified equity funds — most realistic for long-term SIPs)
    • At 14% annual return: ₹66.9 lakh (aggressive small/mid cap — higher risk)

    BVB Capital recommends using 11–12% for planning purposes. It reflects the long-term historical performance of well-managed Indian equity mutual funds without being overoptimistic. Always plan conservatively — if the actual returns are higher, you will simply reach your goal faster.

    Factor 3: Step-Up SIP

    A step-up SIP (also called a top-up SIP) automatically increases your monthly SIP by a fixed percentage each year — usually 10%. Since most people get annual salary hikes, this is a natural way to invest more without feeling the pinch. The impact on your final corpus is enormous:

    • Flat ₹5,000/month for 20 years at 12% → ₹49.9 lakh
    • ₹5,000/month with 10% annual step-up for 20 years at 12% → ₹1.18 crore

    The same starting amount — but a step-up SIP creates more than double the corpus. We cover this in detail in our guide on Step-Up SIP (link: /step-up-sip/).

    5 Common Mistakes People Make When Calculating Their SIP Goal

    Mistake 1: Not Accounting for Inflation

    ₹1 crore sounds like a lot today. But at 6% annual inflation, its purchasing power in 20 years is equivalent to roughly ₹31 lakh today. If you are planning retirement or education 15–20 years away, always set an inflation-adjusted target — not today’s price.

    Rule of thumb Multiply your today’s cost target by 1.8 for a 10-year horizon, 2.4 for 15 years, and 3.2 for 20 years (at 6% inflation). So a ₹20 lakh engineering degree today may cost ₹64 lakh in 20 years.

    Mistake 2: Using Too Optimistic a Return Rate

    Many online SIP calculators default to 15% or even 18%. This is misleading. While some funds have delivered these returns in specific periods, using 15%+ for planning leads to a shortfall. Stick to 11–12% for equity funds over a long horizon. Be pleasantly surprised, not shocked.

    Mistake 3: Not Increasing Your SIP When Your Income Increases

    Investors who set up a ₹3,000 SIP at age 25 and never review it are leaving enormous wealth on the table. Every time your income increases, your SIP should increase too. A 10% annual step-up does this automatically.

    Mistake 4: Stopping SIP During Market Falls

    This is the most costly mistake of all. When markets fall, many investors panic and stop their SIP. But a falling market is exactly when your SIP is buying more units at lower prices — that is rupee cost averaging working in your favour. Missing just the 10 best market days in a 10-year period can reduce your returns by more than 50%.

    Mistake 5: Fund Overlap

    Investing in five different SIPs sounds like diversification, but if all five funds hold the same large-cap stocks, you have no real diversification — only five sets of expense ratios. A proper portfolio review ensures your SIPs work together, not against each other. This is one of the key services BVB Capital provides.

    Frequently Asked Questions About the SIP Calculator

    Q: What is a good return rate to use in a SIP calculator?

    For long-term equity SIP planning (10 years or more), use 11–12% per annum. This is based on the historical CAGR of well-diversified equity mutual funds in India over the past 15–20 years. For debt funds or conservative hybrid funds, use 7–8%.

    Q: Is a SIP calculator 100% accurate?

    No. The SIP calculator assumes a constant return rate every year, but actual mutual fund returns fluctuate. Think of the output as a planning estimate — a target to aim for — not a guaranteed outcome. Actual corpus may be higher or lower depending on market conditions.

    Q: What is the minimum SIP amount I can start with?

    Some mutual funds allow SIPs as low as ₹100 per month. Most financial advisors, including BVB Capital, recommend starting with at least ₹500–₹1,000 to make meaningful progress toward a goal. The key is consistency, not the amount.

    Q: Can I do a SIP for just 1 year?

    Yes, technically you can. But equity SIPs are designed for a minimum 3-year horizon to benefit from market cycles and compounding. A 1-year equity SIP carries significant short-term market risk. For goals under 2 years, liquid funds or short-term debt funds are more appropriate.

    Q: What happens if I miss a SIP instalment?

    Missing one instalment is not a disaster. Most fund houses will simply skip that month and resume the next. However, consistently missing instalments defeats the purpose of disciplined investing and significantly impacts your final corpus.

    Q: How do I start a SIP in Kerala?

    The easiest way is to contact BVB Capital. We are based in Kerala and handle everything — KYC completion, fund selection, SIP setup, and annual portfolio review. Just WhatsApp ‘SIP Start’ to get started. There is no cost to you for our guidance.

    Start Your SIP Today — Your Goal Is Closer Than You Think

    Now you have the numbers. You know how much you need to invest, why starting early makes such an enormous difference, and what mistakes to avoid. The only thing left is to begin.

    Every month you wait is compounding you are not getting. If you are 30 and delay starting by just 2 years, you will need to invest ₹3,000 more per month for the rest of your investment horizon to reach the same corpus. That is the real cost of waiting.

    Start your SIP with BVB Capital — free consultation WhatsApp ‘SIP Start’ to begin. We will help you choose the right fund, set up your KYC, and build a SIP plan matched to your specific goal. BVB Capital | AMFI Registered Distributor | ARN 348338 | Kerala | SEBI Investor Awareness Certified

    Explore More Guides from BVB Capital

    Disclaimer

    Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance is not indicative of future results. The calculations and return rates in this article are for illustration purposes only and do not constitute investment advice. BVB Capital is an AMFI Registered Mutual Fund Distributor (ARN 348338) and is not a SEBI Registered Investment Advisor. Please consult a qualified financial advisor before making investment decisions.
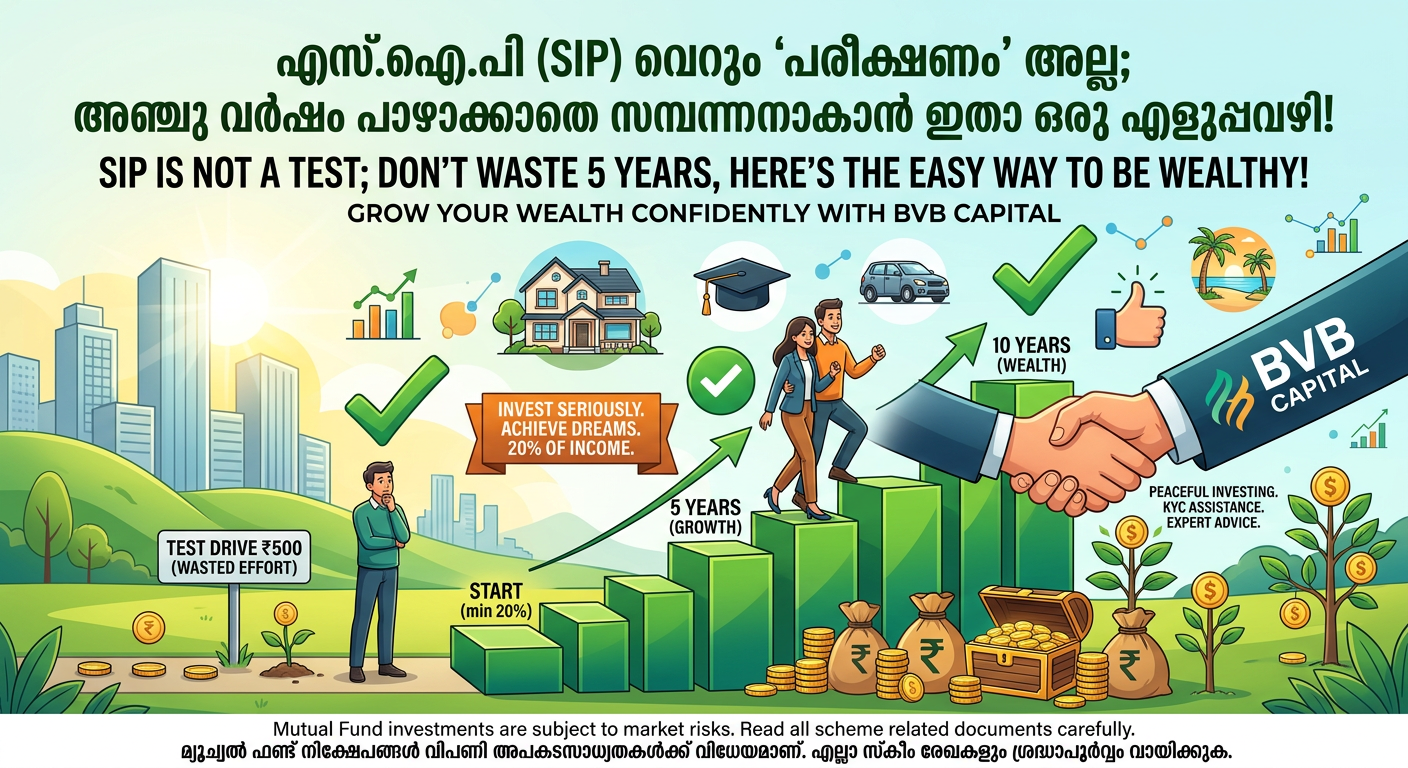
  • എസ്‌.ഐ.പി (SIP) വെറും ‘പരീക്ഷണം’ അല്ല; അഞ്ചു വർഷം പാഴാക്കാതെ സമ്പന്നനാകാൻ ഇതാ ഒരു എളുപ്പവഴി!

    എസ്‌.ഐ.പി (SIP) വെറും ‘പരീക്ഷണം’ അല്ല; അഞ്ചു വർഷം പാഴാക്കാതെ സമ്പന്നനാകാൻ ഇതാ ഒരു എളുപ്പവഴി!

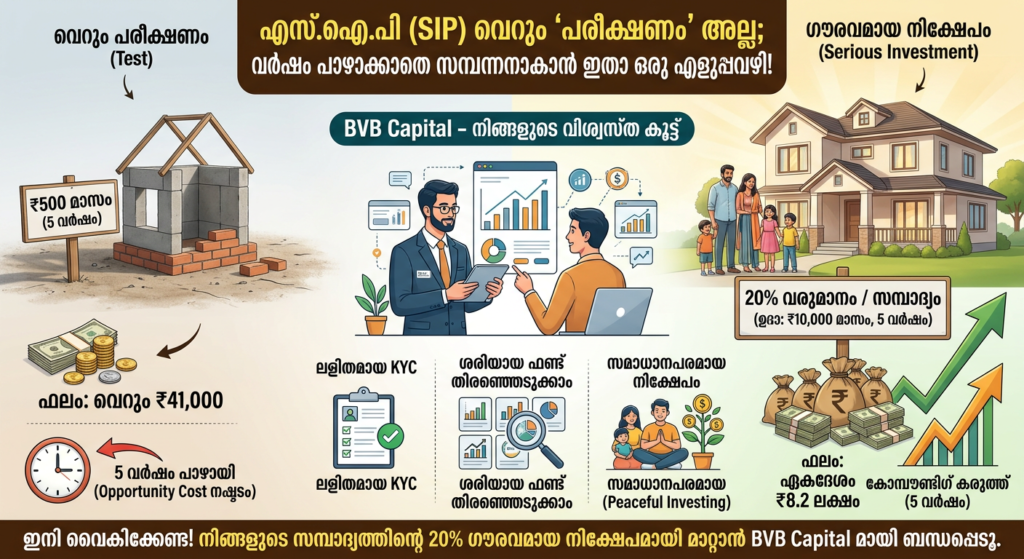
    എന്റെ പ്രിയപ്പെട്ടവരേ, ഒരു കാര്യം ചോദിച്ചോട്ടെ? നമ്മൾ ഒരു പുതിയ വീട് വെക്കാൻ തീരുമാനിച്ചാൽ ആദ്യം അതിന്റെ പ്ലാൻ വരയ്ക്കുകയും തറക്കല്ലിടുകയും ചെയ്യും. അല്ലാതെ, “നമുക്ക് ഈ മാസം ഒരു രണ്ട് കല്ല് വെച്ച് നോക്കാം, എങ്ങനെയുണ്ടാകുമെന്ന് കണ്ടിട്ട് ബാക്കി പണിയാം” എന്ന് ആരെങ്കിലും പറയുമോ? ഇല്ലല്ലോ. കാരണം അങ്ങനെ ചെയ്താൽ ആ വീട് ഒരിക്കലും പണി തീരില്ല എന്ന് നമുക്കറിയാം.

    എന്നാൽ നിക്ഷേപത്തിന്റെ കാര്യത്തിൽ മലയാളി പലപ്പോഴും ചെയ്യുന്നത് ഈ ‘രണ്ട് കല്ല് വെച്ച് നോക്കുന്ന’ പണിയാണ്. പലരും പറയും, “ചേട്ടാ, നമുക്ക് ഒരു 500 രൂപയുടെ എസ്‌.ഐ.പി (SIP) തുടങ്ങാം, ഒരു അഞ്ചു വർഷം ഒന്ന് ടെസ്റ്റ് ചെയ്ത് നോക്കട്ടെ. ലാഭമുണ്ടെങ്കിൽ തുക കൂട്ടാം.” സത്യം പറയട്ടെ, വലിയ തുക നിക്ഷേപിക്കാൻ ശേഷിയുണ്ടായിട്ടും വെറും 500 രൂപയിൽ ഈ അഞ്ചു വർഷം ഒതുങ്ങിനിൽക്കുന്നത് നിങ്ങളുടെ ജീവിതത്തിലെ ഏറ്റവും വിലപ്പെട്ട അഞ്ചു വർഷങ്ങൾ പാഴാക്കുന്നതിന് തുല്യമാണ്.

    ഇന്ന് നമ്മൾ സംസാരിക്കുന്നത് എങ്ങനെ ആത്മവിശ്വാസത്തോടെ നിക്ഷേപം തുടങ്ങാം എന്നും, ഈ യാത്രയിൽ BVB Capital എങ്ങനെ നിങ്ങളുടെ വിശ്വസ്ത പങ്കാളിയാകുന്നു എന്നതിനെ കുറിച്ചുമാണ്.

    500 രൂപയുടെ പരീക്ഷണം: നിങ്ങൾ അറിയാതെ പോകുന്ന നഷ്ടം

    മ്യൂച്വൽ ഫണ്ട് എങ്ങനെയാണ് പ്രവർത്തിക്കുന്നത് എന്ന് മനസ്സിലാക്കാൻ 500 രൂപയുടെ നിക്ഷേപം നല്ലതാണ്. പക്ഷേ, ഒരു കാർ വാങ്ങാനോ, മക്കളുടെ ഉന്നത പഠനത്തിനോ, സമാധാനപരമായ ഒരു റിട്ടയർമെന്റ് കാലത്തിനോ ആണ് നിങ്ങൾ ലക്ഷ്യമിടുന്നതെങ്കിൽ ഈ 500 രൂപയുടെ പരീക്ഷണം നിങ്ങളെ സഹായിക്കില്ല.

    നിക്ഷേപത്തിൽ ഏറ്റവും പ്രധാനം ‘സമയം’ ആണ്. ഒരിക്കൽ പോയാൽ തിരിച്ചു കിട്ടാത്ത ഒന്നാണത്. 500 രൂപ വെച്ച് 5 വർഷം പരീക്ഷണം നടത്തിക്കഴിയുമ്പോൾ നിങ്ങൾക്ക് കാര്യം മനസ്സിലാകും, പക്ഷേ അപ്പോഴേക്കും നിങ്ങളുടെ പ്രായം അഞ്ചു വർഷം കൂടിയിട്ടുണ്ടാകും. ആ അഞ്ചു വർഷം നിങ്ങൾ വലിയൊരു തുക നിക്ഷേപിച്ചിരുന്നെങ്കിൽ ഇന്ന് കിട്ടുന്ന ലാഭത്തിന്റെ പത്തിരട്ടി നിങ്ങൾക്ക് കിട്ടുമായിരുന്നു. ഇതിനെയാണ് സാമ്പത്തിക വിദഗ്ധർ ‘ഓപ്പർച്യുണിറ്റി കോസ്റ്റ്’ എന്ന് വിളിക്കുന്നത്.

    ഒരു കഥ കേൾക്കൂ: സുരേഷും രമേശും

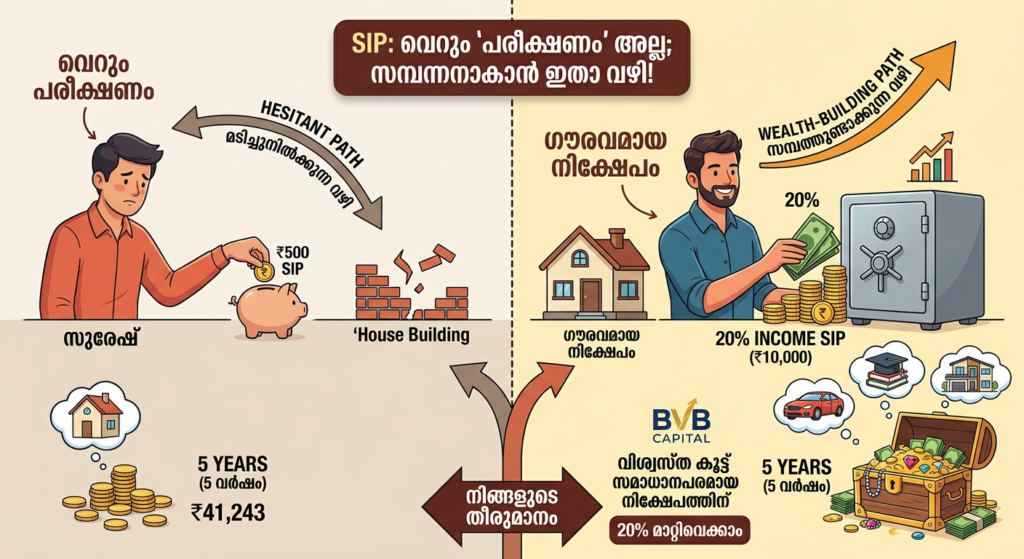
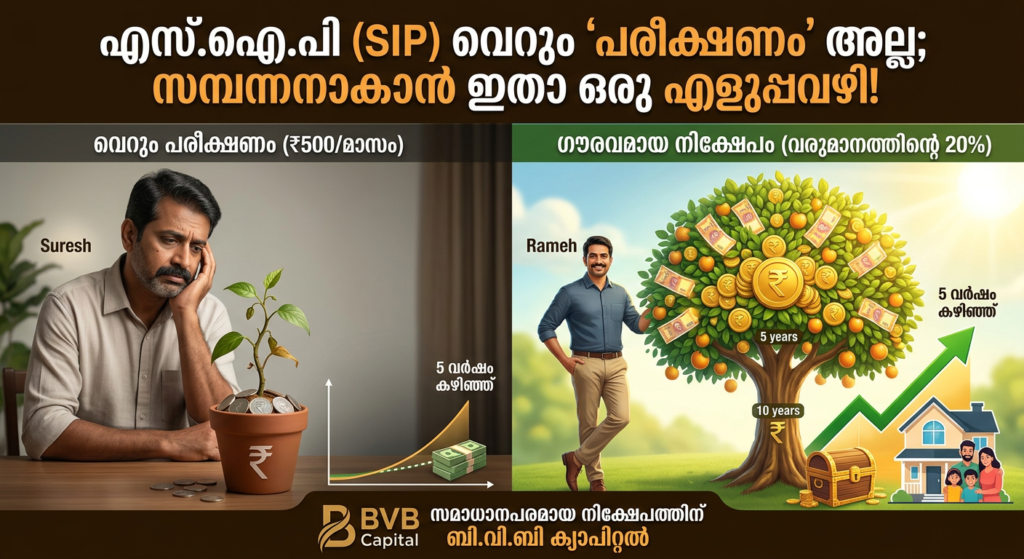
    നമുക്ക് എറണാകുളത്ത് ജോലി ചെയ്യുന്ന സുരേഷിന്റെ കാര്യമെടുക്കാം. സുരേഷിന് മാസം 50,000 രൂപ ശമ്പളമുണ്ട്. വീട്ടുചിലവുകൾ കഴിഞ്ഞ് 15,000 രൂപയോളം സുരേഷിന് ലാഭിക്കാം. പക്ഷേ, സുരേഷ് കരുതിയത് “നമുക്ക് പതുക്കെ തുടങ്ങാം, ആദ്യം ഒരു 500 രൂപയിട്ട് 5 വർഷം നോക്കാം” എന്നാണ്.

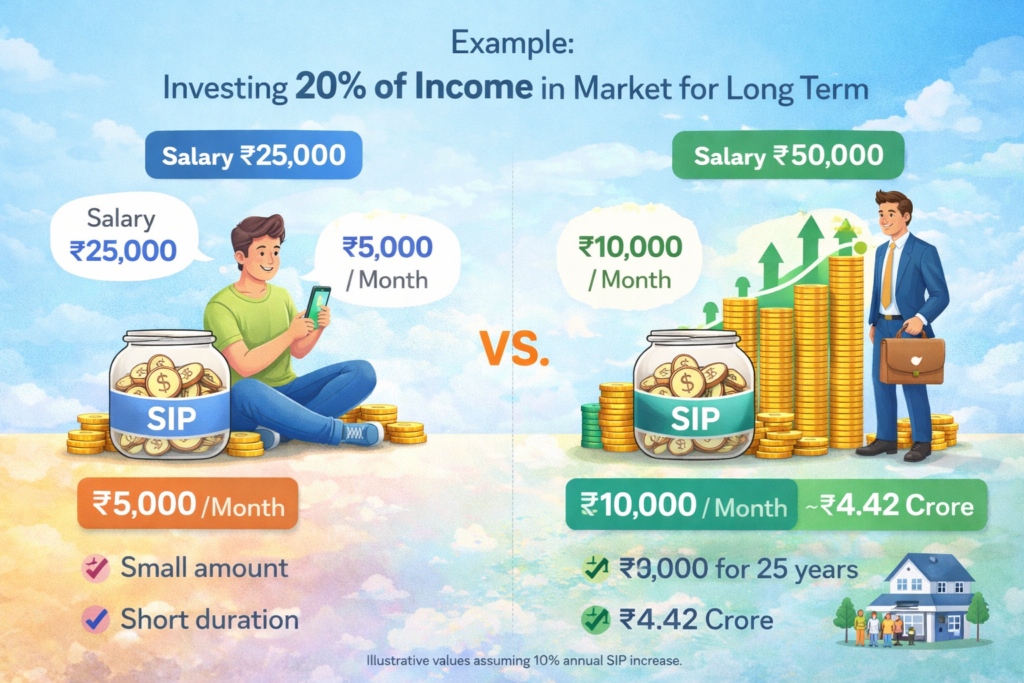
    അഞ്ചു വർഷം കഴിഞ്ഞു. സുരേഷിന്റെ കയ്യിൽ ലാഭം ഉൾപ്പെടെ ഏകദേശം 41,000 രൂപയുണ്ട്. എന്നാൽ സുരേഷിന്റെ സുഹൃത്ത് രമേശ് ചെയ്തത് മറ്റൊന്നാണ്. രമേശും അതേ ശമ്പളക്കാരനാണ്. പക്ഷേ അദ്ദേഹം തന്റെ വരുമാനത്തിന്റെ 20% (അതായത് 10,000 രൂപ) ഗൗരവമായ ഒരു നിക്ഷേപമായി മാറ്റി.

    അഞ്ചു വർഷം കഴിഞ്ഞപ്പോൾ രമേശിന്റെ കയ്യിലുള്ളത് ഏകദേശം 8.2 ലക്ഷം രൂപയാണ്! സുരേഷ് ഇപ്പോഴും ‘പരീക്ഷിച്ചു’ കൊണ്ടിരിക്കുന്നു, എന്നാൽ രമേശ് തന്റെ അടുത്ത ലക്ഷ്യത്തിലേക്ക് (ഒരു പുതിയ വീട്) എത്തിക്കഴിഞ്ഞു. സുരേഷിന് നഷ്ടപ്പെട്ടത് ആ 5 വർഷത്തെ ‘കോമ്പൗണ്ടിംഗ്’ കരുത്താണ്.


    20% of your income should be in SIP

    എന്തുകൊണ്ട് നിങ്ങളുടെ വരുമാനത്തിന്റെ 20% നിക്ഷേപിക്കണം?

    നിങ്ങൾ ഗൗരവമായി പണം സമ്പാദിക്കാൻ ആഗ്രഹിക്കുന്നുണ്ടെങ്കിൽ, നിങ്ങളുടെ ആകെ വരുമാനത്തിന്റെ അല്ലെങ്കിൽ സമ്പാദ്യത്തിന്റെ കുറഞ്ഞത് 20 ശതമാനമെങ്കിലും നിക്ഷേപത്തിലേക്ക് മാറ്റിവെക്കണം.

    നമുക്കൊന്ന് താരതമ്യം ചെയ്തു നോക്കാം (12% വാർഷിക വളർച്ച കണക്കാക്കിയാൽ):

    നിക്ഷേപ രീതിമാസ നിക്ഷേപം5 വർഷം കഴിഞ്ഞുള്ള തുക10 വർഷം കഴിഞ്ഞുള്ള തുക
    വെറും പരീക്ഷണം (Test)₹500₹41,243₹1,16,169
    ഗൗരവമായ നിക്ഷേപം (20%)₹5,000₹4,12,432₹11,61,695
    വലിയ നിക്ഷേപം₹10,000₹8,24,864₹23,23,391

    നോക്കൂ, 500 രൂപയുടെ പരീക്ഷണം കൊണ്ട് നിങ്ങൾക്ക് 10 വർഷം കഴിഞ്ഞാലും വലിയൊരു തുകയിലെത്താൻ കഴിയില്ല. എന്നാൽ 20% സമ്പാദ്യമെങ്കിലും നിക്ഷേപിക്കാൻ നിങ്ങൾ കാണിക്കുന്ന ധൈര്യം നിങ്ങളെ ഒരു കോടീശ്വരനാക്കി മാറ്റാൻ കെൽപ്പുള്ളതാണ്.

    DO NOT TEST SIP AND WASTE TIME

    എവിടെ തുടങ്ങണം? എങ്ങനെയുള്ള ആശയക്കുഴപ്പങ്ങൾ മാറ്റാം?

    പലരും നിക്ഷേപം തുടങ്ങാൻ മടിക്കുന്നത് പണം ഇല്ലാത്തതുകൊണ്ടല്ല, മറിച്ച് ഇതിന്റെ പുറകിലുള്ള നൂലാമാലകൾ പേടിച്ചാണ്.

    • “ഏത് ഫണ്ട് തിരഞ്ഞെടുക്കണം?”
    • “കെ.വൈ.സി (KYC) എങ്ങനെ ചെയ്യും?”
    • “വിപണി താഴേക്ക് പോയാൽ എന്ത് ചെയ്യും?” ഈ സംശയങ്ങൾ കാരണം പലരും നിക്ഷേപം മാറ്റിവെക്കുന്നു. ഇവിടെയാണ് BVB Capital നിങ്ങളുടെ സഹായത്തിനെത്തുന്നത്.

    BVB Capital: സമാധാനപരമായ നിക്ഷേപത്തിന് ഒരു വിശ്വസ്ത കൂട്ട്

    നിക്ഷേപം എന്നത് വെറും കണക്കുകൂട്ടലുകൾ മാത്രമല്ല, അതൊരു ദീർഘകാല ബന്ധമാണ്. BVB Capital ലൂടെ നിക്ഷേപം ആരംഭിക്കുമ്പോൾ നിങ്ങൾക്ക് ലഭിക്കുന്ന ഗുണങ്ങൾ ഇവയാണ്:

    1. സങ്കീർണ്ണമായ KYC നടപടികൾ ഞങ്ങൾ ഏറ്റെടുക്കുന്നു: പേപ്പർ വർക്കുകളെക്കുറിച്ചോ ഓൺലൈൻ അപ്‌ഡേഷനുകളെക്കുറിച്ചോ നിങ്ങൾ ആകുലപ്പെടേണ്ടതില്ല. നിങ്ങളുടെ കെ.വൈ.സി നടപടികൾ ലളിതമായി പൂർത്തിയാക്കാൻ ബി.വി.ബി ക്യാപിറ്റൽ നിങ്ങളെ സഹായിക്കുന്നു.
    2. ശരിയായ ഫണ്ട് തിരഞ്ഞെടുക്കാം: ആയിരക്കണക്കിന് മ്യൂച്വൽ ഫണ്ട് സ്കീമുകളിൽ നിന്ന് നിങ്ങളുടെ സാമ്പത്തിക ലക്ഷ്യങ്ങൾക്കും വരുമാനത്തിനും അനുയോജ്യമായവ തിരഞ്ഞെടുക്കാൻ ഞങ്ങളുടെ വിദഗ്ധ സംഘം നിങ്ങളെ സഹായിക്കുന്നു.
    3. ദീർഘകാല ബന്ധം: നിക്ഷേപം തുടങ്ങുന്നതിലല്ല, അത് കൃത്യമായി കൊണ്ടുപോകുന്നതിലാണ് കാര്യം. വിപണിയിലെ കയറ്റിറക്കങ്ങളിൽ പേടിക്കാതെ, സമാധാനത്തോടെ നിക്ഷേപം തുടരാൻ ഒരു കൈത്താങ്ങായി ബി.വി.ബി ക്യാപിറ്റൽ എപ്പോഴും കൂടെയുണ്ടാകും.
    4. സമാധാനപരമായ നിക്ഷേപം (Peaceful Investing): വിപണിയെക്കുറിച്ചോ ഇൻഡക്സിനെക്കുറിച്ചോ ഓരോ നിമിഷവും വ്യാകുലപ്പെടേണ്ടതില്ല. പ്രൊഫഷണലായ ഗൈഡൻസ് ഉള്ളപ്പോൾ നിങ്ങൾക്ക് നിങ്ങളുടെ ജോലിയിലും കുടുംബത്തിലും ശ്രദ്ധ കേന്ദ്രീകരിക്കാം, നിങ്ങളുടെ പണം ഞങ്ങൾക്കായി പണിയെടുക്കും.

    മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപകർ ശ്രദ്ധിക്കേണ്ട കാര്യങ്ങൾ (AMFI Guidelines)

    നിക്ഷേപം തുടങ്ങുന്നതിന് മുൻപ് ഈ കാര്യങ്ങൾ മറക്കരുത്:

    1. വിപണി അപകടസാധ്യതകൾ: മ്യൂച്വൽ ഫണ്ട് നിക്ഷേപങ്ങൾ വിപണി അപകടസാധ്യതകൾക്ക് വിധേയമാണ്. വിപണിയിലെ മാറ്റങ്ങൾ നിങ്ങളുടെ നിക്ഷേപത്തെ ബാധിച്ചേക്കാം. സ്കീം സംബന്ധിച്ച എല്ലാ രേഖകളും ശ്രദ്ധാപൂർവം വായിക്കുക.
    2. ഗ്യാരണ്ടി ഇല്ല: മ്യൂച്വൽ ഫണ്ട് ഒരു ബാങ്ക് ഡെപ്പോസിറ്റ് അല്ല. മുൻകാല പ്രകടനം ഭാവിയിൽ ആവർത്തിക്കണമെന്നുമില്ല.
    3. വിദഗ്ധ ഉപദേശം: എപ്പോഴും ഒരു സെബി (SEBI) രജിസ്റ്റേർഡ് ഫിനാൻഷ്യൽ അഡ്വൈസറുടെ സഹായത്തോടെ മാത്രം നിക്ഷേപം നടത്തുക.

    ഇനി വൈകിക്കേണ്ട, ആ 20% മാറ്റിവെക്കാം

    നിങ്ങളുടെ സമ്പാദ്യത്തിന്റെ 20% ഗൗരവമായ ഒരു നിക്ഷേപമായി മാറ്റാൻ ഇതാണ് ഏറ്റവും നല്ല സമയം. 500 രൂപയുടെ ‘ടെസ്റ്റ് ഡ്രൈവ്’ നടത്തിക്കൊണ്ടിരുന്നാൽ നിങ്ങൾ ലക്ഷ്യസ്ഥാനത്ത് എത്തില്ല.

    BVB Capital മായി കൈകോർത്ത്, എല്ലാ സാങ്കേതിക ബുദ്ധിമുട്ടുകളും ഞങ്ങൾക്ക് വിട്ടുനൽകി, ആത്മവിശ്വാസത്തോടെ നിങ്ങളുടെ സാമ്പത്തിക ഭദ്രതയിലേക്കുള്ള യാത്ര തുടങ്ങൂ. സമാധാനപരമായ ഒരു നിക്ഷേപത്തിലൂടെ നിങ്ങളുടെ സ്വപ്നങ്ങൾ സാക്ഷാത്കരിക്കാൻ ഞങ്ങൾ കൂടെയുണ്ട്.

    സന്തോഷകരമായ നിക്ഷേപയാത്ര നേരുന്നു!


    Disclaimer: Mutual Fund നിക്ഷേപങ്ങൾ വിപണി അപകടസാധ്യതകൾക്ക് വിധേയമാണ്. സ്കീം സംബന്ധിച്ച എല്ലാ രേഖകളും ശ്രദ്ധാപൂർവം വായിക്കുക. മുകളിൽ നൽകിയിരിക്കുന്ന കണക്കുകൾ ഒരു ധാരണയ്ക്ക് വേണ്ടിയുള്ള ഉദാഹരണങ്ങൾ മാത്രമാണ്.

    നിങ്ങളുടെ സമ്പാദ്യത്തിന്റെ 20% എങ്ങനെ കൃത്യമായി നിക്ഷേപിക്കണം എന്ന് അറിയാൻ ബി.വി.ബി ക്യാപിറ്റലുമായി (BVB Capital) ബന്ധപ്പെടാൻ ആഗ്രഹിക്കുന്നുണ്ടോ? Contact us

  • Is ₹500 SIP for 5 Years Enough? Let’s Understand the Reality

    Is ₹500 SIP for 5 Years Enough? Let’s Understand the Reality

    Many new investors ask:

    👉 “If I invest ₹500 per month in SIP, what will I get after 5 years?”

    Let’s understand this with a simple example.
    If you are new to SIP, first understand how it works in detail.


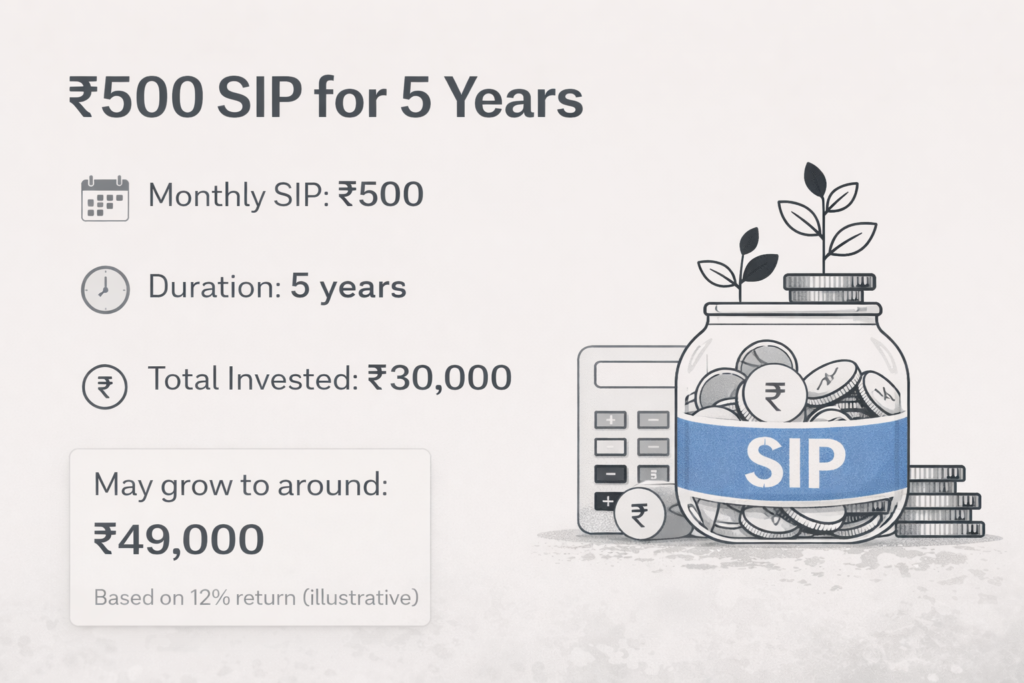
    📊 Example: ₹500 SIP for 5 Years

    • Monthly SIP: ₹500
    • Duration: 5 years
    • Total invested: ₹30,000

    👉 Based on an assumed return of 12% per annum,
    the value may grow to around ₹49,000

    👉 Gain: ~₹19,000


    ⚠️ Important Note

    This is only an illustration, not a guarantee.

    • Mutual fund returns are market-linked
    • Actual returns may be higher or lower
    • This example is used only to help understand how SIP works

    Common SIP investment mistakes for beginners

    🤔 What Does This Mean?

    A ₹500 SIP helps you:
    ✔ Start investing
    ✔ Build financial discipline

    But:

    👉 For meaningful wealth creation, both amount and time matter


    📈 The Role of Time in Investing

    Let’s see what happens when you stay invested longer:

    SIPDurationValue (Illustrative @12%)
    ₹5005 years~₹49,000
    ₹50020 years~₹9.9 Lakhs
    ₹50030 years~₹44 Lakhs

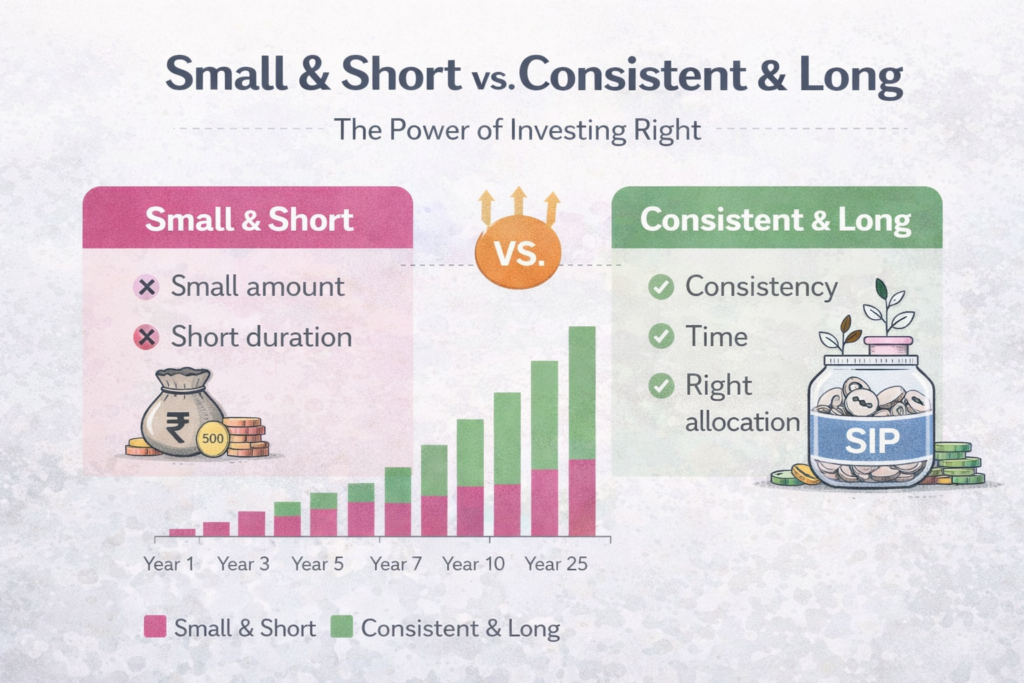
    👉 Same SIP… but longer duration shows the impact of compounding.


    Investing strategies: short-term vs long-term

    🚀 Increasing SIP Over Time (Step-Up SIP)

    In real life, income increases over time.
    So investors can consider increasing SIP annually.

    👉 In the projections shown here,
    we have assumed a 10% annual increase (top-up) in SIP amount

    This approach is called:

    👉 Step-Up SIP

    It can significantly improve long-term outcomes.


    📊 Example: ₹5,000 SIP with 10% Yearly Increase

    • ₹5,000 for 15 years → ~₹43 Lakhs
    • ₹5,000 for 25 years → ~₹2.14 Crore
    • ₹5,000 for 30 years → ~₹4.42 Crore

    (All values are illustrative, assuming 12% annual return and 10% SIP increase per year)


    💡 Key Takeaways

    ✔ Starting small is good
    ✔ Staying invested is more important
    ✔ Increasing SIP over time can improve results
    ✔ Long-term investing helps benefit from compounding


    Stock market investment illustration for growth

    🎯 How Much Should You Invest?

    A common thumb rule:

    👉 Try to invest a portion of your income regularly
    (For many investors, this may range around 10–20%, depending on their situation)

    Always invest based on:

    • Income
    • Expenses
    • Financial goals
    • Risk capacity

    ⚠️ Avoid These Common Mistakes

    ❌ Investing only based on small trial amounts
    ❌ Stopping SIPs during market fluctuations
    ❌ Selecting funds based only on past returns


    🧠 Why Proper Guidance Matters

    Mutual fund investing is not just about starting an SIP.

    It involves:

    • Understanding your risk profile
    • Selecting suitable asset allocation
    • Choosing appropriate schemes
    • Staying consistent during market ups and downs

    🤝 How BVB Capital Can Help

    At BVB Capital, we focus on:

    ✔ Risk profiling before investment
    ✔ Goal-based portfolio construction
    ✔ Suitable scheme selection (not random picking)
    ✔ Long-term investment discipline

    👉 The aim is to help investors make informed and structured decisions


    🔚 Final Thought

    SIP is a powerful tool when used correctly.

    👉 Start early
    👉 Stay consistent
    👉 Increase gradually
    👉 Think long term


    📞 Get Started

    If you want to plan your SIP based on your goals and risk profile:

    👉 Connect with BVB Capital for a structured approach to investing


    ⚖️ Mandatory Disclaimer (AMFI-Compliant)

    Mutual Fund investments are subject to market risks.
    Read all scheme related documents carefully before investing.

    The returns shown above are illustrative and are based on assumed rates of return.
    They are not guaranteed and do not indicate future performance.

  • SIP ഹലാൽ ആണോ?

    SIP ഹലാൽ ആണോ?

    നിക്ഷേപകർ അറിഞ്ഞിരിക്കേണ്ട ലളിതമായ വസ്തുതകൾ!

    പല മുസ്ലിം സഹോദരങ്ങളും ചോദിക്കാറുള്ള ഒരു പ്രധാന ചോദ്യമാണ്— “ഞാൻ മ്യൂച്വൽ ഫണ്ടിൽ SIP തുടങ്ങാൻ ആഗ്രഹിക്കുന്നു, പക്ഷേ SIP ഹലാൽ ആണോ?”

    ഇതിനെക്കുറിച്ച് പലർക്കും പലതരത്തിലുള്ള തെറ്റിദ്ധാരണകളുണ്ട്. സത്യത്തിൽ SIP എന്നത് ഹലാൽ ആണോ ഹറാം ആണോ എന്ന് തീരുമാനിക്കുന്നത് അതിലെ സാങ്കേതികതയല്ല, മറിച്ച് നിങ്ങൾ എവിടെയാണ് പണം നിക്ഷേപിക്കുന്നത് എന്നതാണ്. ബി.വി.ബി ക്യാപിറ്റലിന്റെ (BVB Capital) ഈ ബ്ലോഗിലൂടെ നമുക്ക് ഈ വിഷയം ലളിതമായി പരിശോധിക്കാം.
    ഇന്ത്യയിലെ ഹലാൽ മ്യൂച്വൽ ഫണ്ടുകൾ

    എന്താണ് SIP? (What is SIP?)

    halal sip mutual fund investment

    Systematic Investment Plan എന്നതിന്റെ ചുരുക്കപ്പേരാണ് SIP. ഇത് ഒരു നിക്ഷേപ പദ്ധതിയല്ല, മറിച്ച് നിക്ഷേപം നടത്താൻ ഉപയോഗിക്കുന്ന ഒരു മാർഗ്ഗം (Method) മാത്രമാണ്.

    ഉദാഹരണത്തിന്, നിങ്ങൾ എല്ലാ മാസവും ഒരു നിശ്ചിത തുക (ഉദാഹരണത്തിന് 2000 രൂപ) ഒരു മ്യൂച്വൽ ഫണ്ടിൽ നിക്ഷേപിക്കാൻ തീരുമാനിച്ചാൽ അതിനെ SIP എന്ന് വിളിക്കുന്നു.

    SIP ഹലാൽ ആണോ? (Is SIP Halal?)

    SIP എന്നത് ഒരു വാഹനം പോലെയാണ്. അത് നിങ്ങളെ നല്ല സ്ഥലത്തേക്കും മോശം സ്ഥലത്തേക്കും കൊണ്ടുപോകാം. അതുകൊണ്ട് തന്നെ SIP ഹലാൽ ആണോ എന്ന് തീരുമാനിക്കുന്നത് നിങ്ങൾ തിരഞ്ഞെടുക്കുന്ന മ്യൂച്വൽ ഫണ്ടാണ്.

    1. എപ്പോൾ ഹലാൽ ആകുന്നു? നിങ്ങളുടെ SIP തുക നിക്ഷേപിക്കുന്നത് ശരീഅത്ത് കംപ്ലയിന്റ് (Shariah-compliant) ആയ മ്യൂച്വൽ ഫണ്ടുകളിലാണെങ്കിൽ അത് പൂർണ്ണമായും ഹലാൽ ആണ്. ഇത്തരം ഫണ്ടുകൾ മദ്യം, പുകയില, പലിശ ലഭിക്കുന്ന ബാങ്കിംഗ് മേഖലകൾ തുടങ്ങിയവ ഒഴിവാക്കി ധാർമ്മികമായ ബിസിനസ്സുകളിൽ മാത്രമേ നിക്ഷേപം നടത്തൂ.
    2. എപ്പോൾ ഹറാം ആകുന്നു? നിങ്ങളുടെ SIP നിക്ഷേപം പലിശയുമായി ബന്ധപ്പെട്ട ബാങ്കിംഗ് മേഖലയിലോ അല്ലെങ്കിൽ ഇസ്ലാം വിലക്കിയ ബിസിനസ്സുകളിലോ പ്രവർത്തിക്കുന്ന കമ്പനികളിലാണെങ്കിൽ അത് ഹലാൽ ആയി കണക്കാക്കാൻ കഴിയില്ല.

    ചുരുക്കത്തിൽ, നിക്ഷേപിക്കുന്ന രീതിയല്ല (SIP), മറിച്ച് നിങ്ങൾ നിക്ഷേപിക്കാൻ തിരഞ്ഞെടുക്കുന്ന ഫണ്ട് ആണ് അതിന്റെ ശുദ്ധി നിശ്ചയിക്കുന്നത്.
    കേരളത്തിലെ മികച്ച ഹലാൽ നിക്ഷേപ മാർഗങ്ങൾ


    എന്തുകൊണ്ട് ഹലാൽ നിക്ഷേപകർക്ക് SIP അനുയോജ്യമാണ്?

    ഹലാൽ മൂല്യങ്ങൾ കാത്തുസൂക്ഷിക്കുന്നവർക്ക് SIP വഴി നിക്ഷേപിക്കുന്നത് പല ഗുണങ്ങൾ നൽകുന്നു:

    • അച്ചടക്കമുള്ള നിക്ഷേപം: മാസമാസം ചെറിയ തുകകൾ മാറ്റിവെക്കുന്നത് വഴി വലിയൊരു സമ്പാദ്യം കെട്ടിപ്പടുക്കാം.
    • സമ്മർദ്ദമില്ലാത്ത നിക്ഷേപം: വിപണിയിലെ കയറ്റിറക്കങ്ങളെക്കുറിച്ച് ആകുലപ്പെടാതെ ദീർഘകാലത്തേക്ക് നിക്ഷേപിക്കാം.
    • ചെറിയ തുകയിൽ തുടങ്ങാം: ബി.വി.ബി ക്യാപിറ്റലിലൂടെ നിങ്ങൾക്ക് വെറും 500 രൂപ മുതൽ ഹലാൽ SIP തുടങ്ങാവുന്നതാണ്.

    ബി.വി.ബി ക്യാപിറ്റലിലൂടെ (BVB Capital) എങ്ങനെ ഹലാൽ SIP തുടങ്ങാം?

    നിങ്ങളുടെ നിക്ഷേപം 100% ശരീഅത്ത് നിയമങ്ങൾ പാലിക്കുന്നു എന്ന് ഉറപ്പുവരുത്താൻ ബി.വി.ബി ക്യാപിറ്റൽ നിങ്ങളെ സഹായിക്കുന്നു.

    • ശരിയായ ഫണ്ട് കണ്ടെത്തൽ: ടാറ്റ എത്തിക്കൽ ഫണ്ട്, ടോറസ് എത്തിക്കൽ ഫണ്ട് തുടങ്ങിയ മികച്ച ഹലാൽ ഫണ്ടുകൾ തിരഞ്ഞെടുക്കാൻ സഹായിക്കുന്നു.
    • എളുപ്പമുള്ള പ്രോസസ്സ്: പേപ്പർ വർക്കുകളില്ലാതെ ഓൺലൈനായി നിങ്ങളുടെ SIP അക്കൗണ്ട് തുടങ്ങാം.
    • വിദഗ്ദ്ധ ഉപദേശം: നിങ്ങളുടെ സാമ്പത്തിക ലക്ഷ്യങ്ങൾക്കനുസരിച്ച് എത്ര രൂപ വീതം നിക്ഷേപിക്കണം എന്നതിൽ കൃത്യമായ മാർഗ്ഗനിർദ്ദേശം നൽകുന്നു.

    നിങ്ങളുടെ ഹലാൽ ഇൻവെസ്റ്റ്‌മെന്റ് യാത്ര ഇന്ന് തന്നെ തുടങ്ങൂ!

    ഇന്ത്യയിൽ വർദ്ധിച്ചുവരുന്ന ഹലാൽ നിക്ഷേപ സാധ്യതകളെക്കുറിച്ച് കൂടുതൽ അറിയാനും ഒരു നിക്ഷേപ അക്കൗണ്ട് തുടങ്ങാനും ബി.വി.ബി ക്യാപിറ്റലിനെ ബന്ധപ്പെടാം.

    • WhatsApp: +91 96339 40008
    • Website: bvbcap.com
    • Phone: 080 696 40046
    • Location: തൃശ്ശൂർ, കേരളം.

    ഹലാൽ മ്യൂച്വൽ ഫണ്ടുകളും സാധാരണ മ്യൂച്വൽ ഫണ്ടുകളും: വ്യത്യാസങ്ങൾ എന്തൊക്കെ?

  • Is SIP Halal? A Simple Explanation Every Investor Should Know

    Is SIP Halal? A Simple Explanation Every Investor Should Know

    A Common Question Many Investors Ask

    A few months ago, a young professional working in Kochi contacted us with a simple but important question.

    He said, “I want to start investing through SIP, but I am not sure whether SIP is halal.”

    This question is very common. Many people want to invest for their future but also want to ensure their investments follow Islamic principles.

    The answer is simple, but it requires proper understanding.

    SIP itself is not halal or haram. It depends on where you invest.


    First, Understand What SIP Actually Means

    SIP stands for Systematic Investment Plan.

    It is not an investment product.

    It is only a method of investing.

    SIP allows you to invest a fixed amount regularly, such as monthly, into a mutual fund.

    For example:

    You invest ₹5,000 every month into a mutual fund.

    This regular investment method is called SIP.

    So SIP is simply a process, not the actual investment.


    Why SIP Itself Is Neutral

    Think of SIP like a vehicle.

    A vehicle can take you to a good place or a bad place.

    The vehicle itself is neutral.

    Similarly, SIP is just a method used to invest.

    Whether it is halal or not depends on the mutual fund you choose.


    When SIP Becomes Halal

    SIP becomes halal when the mutual fund you invest in is Shariah-compliant.

    This means the mutual fund invests only in companies that follow Islamic financial guidelines.

    These companies avoid prohibited sectors like:

    • Interest-based financial institutions
    • Alcohol companies
    • Gambling businesses
    • Tobacco companies

    If your SIP is invested in halal mutual funds, then your investment is considered halal.
    Halal mutual funds in India


    When SIP Becomes Non-Halal

    If your SIP is invested in mutual funds that include companies involved in interest-based banking or prohibited industries, then it may not be considered halal.

    This is why fund selection is extremely important.

    The method is not the issue. The investment selection is the key.
    Difference between halal and normal mutual funds


    Why SIP Is Actually a Very Good Option for Halal Investors

    SIP offers several advantages that align well with halal investing principles.

    1. Disciplined wealth creation

    SIP encourages regular investing without speculation.

    2. Avoids emotional investing

    It reduces impulsive decisions and promotes consistency.

    3. Suitable for long-term financial planning

    Islam encourages responsible financial planning.

    4. Accessible for everyone

    You can start with small amounts and increase gradually.


    Real-Life Example

    Consider two investors.

    Investor A invests ₹5,000 monthly into a halal mutual fund through SIP.

    Investor B invests ₹5,000 monthly into a non-halal fund.

    Both use SIP.

    But only Investor A is investing in a halal way.

    The difference is the fund, not the SIP.


    Why Many Investors in Kerala Prefer Halal SIP

    Kerala has a large number of investors who prefer ethical and Shariah-compliant investments.

    Many professionals, business owners, and NRIs are now choosing halal SIP to build their wealth while staying true to their values.

    Halal SIP provides both financial growth and peace of mind.


    Important Point to Remember

    SIP is only a method.

    Halal compliance depends on:

    • The mutual fund you select
    • The companies included in the fund
    • The investment strategy

    Choosing the right fund ensures your investment remains halal.


    How to Start Halal SIP Safely

    Starting halal SIP is simple with proper guidance.

    Basic steps include:

    • Complete KYC process
    • Select Shariah-compliant mutual fund
    • Choose monthly investment amount
    • Start SIP

    Proper guidance ensures correct fund selection.


    Long-Term Perspective Is Important

    Like any equity investment, halal SIP works best when continued for long periods.

    Consistency and patience are key factors in wealth creation.

    Short-term market movements should not influence long-term planning.


    Conclusion: SIP Can Be Halal When Done Correctly

    SIP is simply a method of investing.

    It becomes halal when used to invest in Shariah-compliant mutual funds.

    By selecting suitable halal funds and investing regularly, investors can build wealth while following their religious principles.

    Halal SIP provides a structured and ethical way to achieve financial goals.
    Start halal SIP investment


    Call to Action

    If you would like to start halal SIP with proper guidance, BVB Capital Private Limited can assist you in selecting suitable Shariah-compliant mutual funds.

    Website: bvbcap.com
    WhatsApp: 96339 40008

  • എന്താണ് ഈ SIP-യും SWP-യും?

    എന്താണ് ഈ SIP-യും SWP-യും?

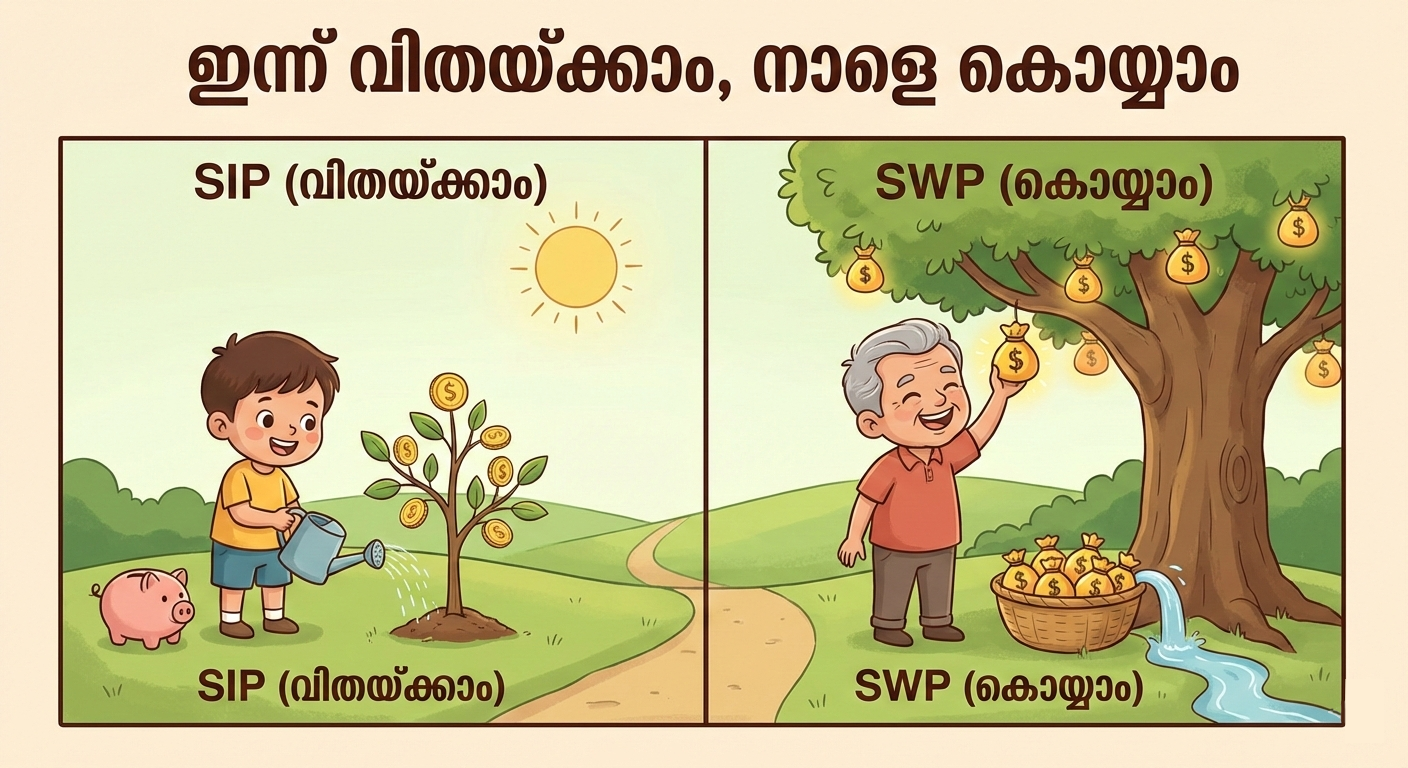
    ഇന്ന് വിതയ്ക്കാം, നാളെ കൊയ്യാം

    കൂട്ടുകാരെ, നമുക്കെല്ലാവർക്കും മിഠായി വാങ്ങാനും കളിപ്പാട്ടങ്ങൾ വാങ്ങാനും ഒക്കെ പൈസ വേണം, അല്ലേ? സാധാരണ നമ്മൾ എന്ത് ചെയ്യും? അച്ഛനോ അമ്മയോ തരുന്ന പൈസ ഒരു കുടുക്കയിൽ (Piggy bank) ഇട്ടു വെക്കും. കുറെ നാൾ കഴിയുമ്പോൾ ആ കുടുക്ക നിറയും.

    ഇതുപോലെ വലിയവർ പണം സമ്പാദിക്കുന്ന ഒരു സൂപ്പർ വഴിയെക്കുറിച്ചാണ് ഇന്ന് നമ്മൾ പറയാൻ പോകുന്നത്. അതിന്റെ പേരാണ് SIP-യും SWP-യും. കേട്ടിട്ട് പേടി തോന്നുന്നുണ്ടോ? പേടിക്കണ്ട, സംഗതി വളരെ സിമ്പിളാണ്!

    1. എന്താണ് ഈ SIP? (മരം നടുന്ന കാലം)

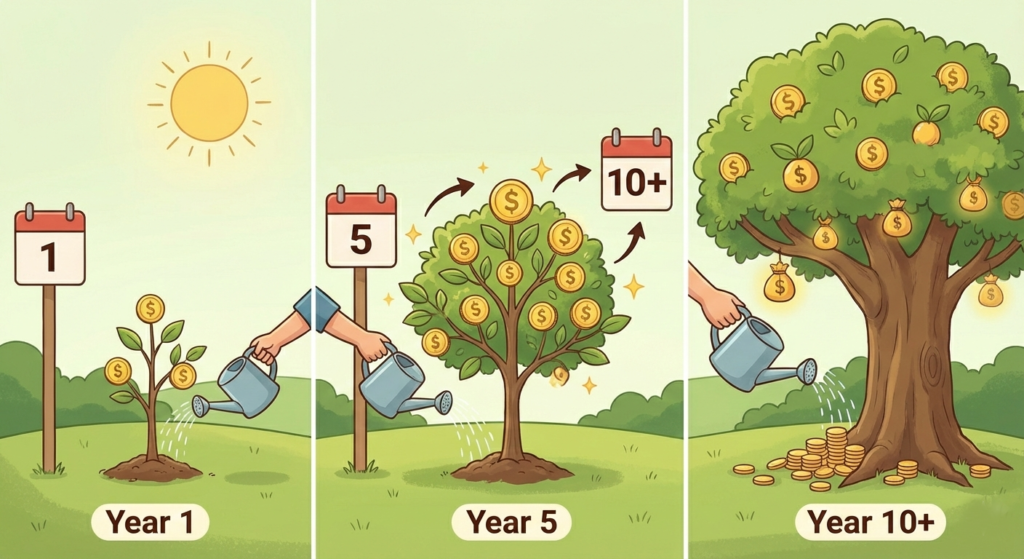
    നമ്മൾ ഒരു മാവിൻ തൈ നടുന്നു എന്ന് വിചാരിക്കുക. നമ്മൾ ദിവസവും അതിന് വെള്ളമൊഴിക്കും, ശ്രദ്ധിക്കും. പെട്ടെന്ന് ഒരു ദിവസം കൊണ്ട് അത് വലിയ മരമാകില്ല. വർഷങ്ങൾ എടുക്കും. പക്ഷേ, നമ്മൾ മടുക്കാതെ എന്നും വെള്ളമൊഴിച്ചാൽ അത് പതുക്കെ പതുക്കെ വളർന്ന് വലിയൊരു മരമാകും.

    growing your sip tree

    ഇതുപോലെ, എല്ലാ മാസവും നമ്മുടെ കയ്യിലുള്ള ചെറിയൊരു തുക (അത് 500 രൂപയോ 1000 രൂപയോ എത്രയുമാകാം) സമ്പാദിക്കുന്ന രീതിയാണ് SIP (Systematic Investment Plan).

    • ഗുണം: ചെറിയ തുകയായതുകൊണ്ട് നമുക്ക് ബുദ്ധിമുട്ടുണ്ടാകില്ല.
    • മാജിക്: വർഷങ്ങൾ കഴിയുമ്പോൾ ഈ ചെറിയ തുക ഒരു വലിയ ‘പണത്തിന്റെ മരമായി’ മാറും. ഇതിനെയാണ് ‘കോമ്പൗണ്ടിംഗ്’ (Compounding) എന്ന് വിളിക്കുന്നത്. അതായത്, പണം വളർന്ന് വളർന്ന് വലുതാകുന്ന മാജിക്!

    2. എന്താണ് ഈ SWP? (പഴം പറിക്കുന്ന കാലം)

    നമ്മൾ നട്ട മാവ് വലുതായി എന്ന് വിചാരിക്കുക. ഇനി നമുക്ക് എന്ത് ചെയ്യാം? ആ മരം മുറിച്ചു വിൽക്കാം. പക്ഷേ, അങ്ങനെ ചെയ്താൽ പിന്നെ നമുക്ക് മാമ്പഴം കിട്ടില്ലല്ലോ?

    enjoying the fruit of sip during swp

    അതിന് പകരം, മരത്തിലെ മാമ്പഴം മാത്രം ഓരോന്നായി പറിച്ചെടുത്താലോ? മരം അവിടെത്തന്നെ ഉണ്ടാകും, നമുക്ക് എല്ലാ കാലത്തും മാമ്പഴം കഴിക്കുകയും ചെയ്യാം.

    ഇതാണ് SWP (Systematic Withdrawal Plan). നമ്മൾ SIP വഴി ഉണ്ടാക്കിയ വലിയൊരു തുകയിൽ നിന്ന്, എല്ലാ മാസവും കൃത്യമായ ഒരു തുക ശമ്പളം പോലെ തിരിച്ചെടുക്കുന്ന രീതിയാണിത്.

    • ഗുണം: ജോലിയിൽ നിന്നൊക്കെ വിരമിച്ചു കഴിയുമ്പോൾ (Retirement), കയ്യിൽ പണമില്ലാതെ വിഷമിക്കണ്ട. ഈ മരത്തിൽ നിന്ന് മാമ്പഴം പറിക്കുന്നത് പോലെ എല്ലാ മാസവും പണം കിട്ടിക്കൊണ്ടിരിക്കും. ബാക്കി പണം അവിടെയിരുന്ന് വീണ്ടും വളരുകയും ചെയ്യും!

    ചുരുക്കത്തിൽ പറഞ്ഞാൽ:

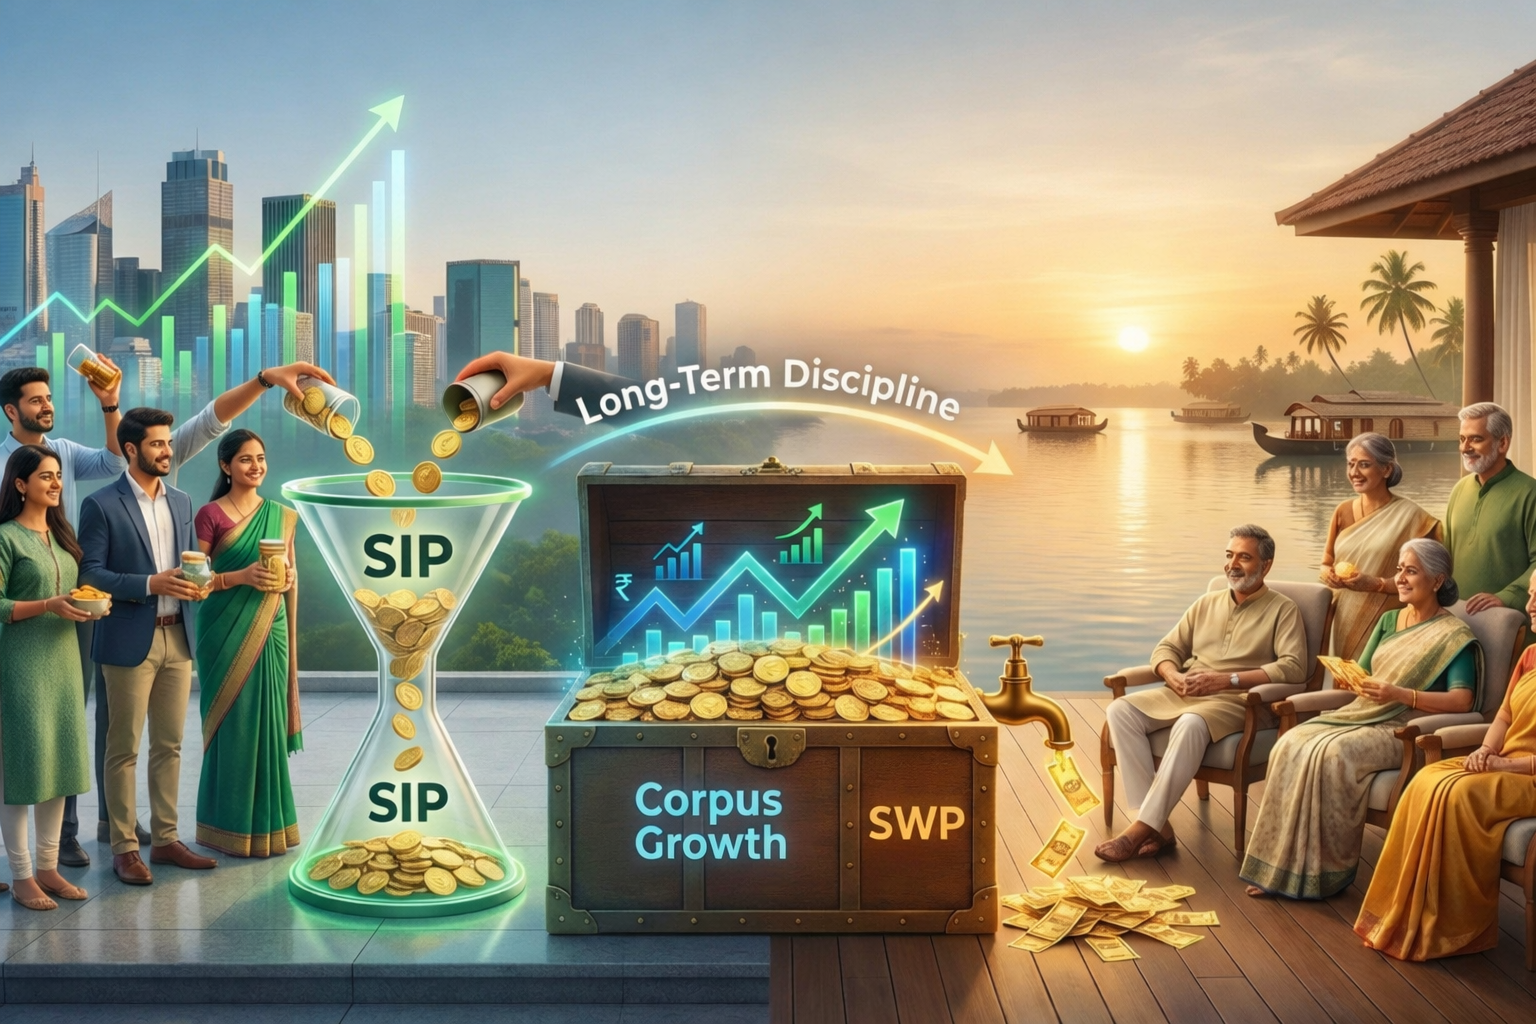
    • SIP: ഇത് പണം നിക്ഷേപിക്കുന്ന ഘട്ടമാണ്. ഒരു വലിയ സമ്പാദ്യം ഉണ്ടാക്കിയെടുക്കാൻ ഇത് സഹായിക്കുന്നു.
    • SWP: ഇത് നിക്ഷേപിച്ച പണം ഉപയോഗിക്കുന്ന ഘട്ടമാണ്. എല്ലാ മാസവും ഒരു വരുമാനം ഉറപ്പാക്കാൻ ഇത് സഹായിക്കുന്നു.

    നമ്മൾ എന്ത് ചെയ്യണം?

    ഇപ്പോൾ നിങ്ങൾ കുട്ടികളാണെങ്കിലും, ഈ കാര്യം മനസ്സിലാക്കി വെക്കുന്നത് നല്ലതാണ്. വലുതാകുമ്പോൾ ആദ്യത്തെ ശമ്പളം കിട്ടിത്തുടങ്ങുമ്പോൾ തന്നെ ഒരു ചെറിയ SIP തുടങ്ങിയാൽ, ഭാവിയിൽ നിങ്ങൾക്ക് സാമ്പത്തികമായി ഒരു ബുദ്ധിമുട്ടും ഉണ്ടാവില്ല.

    ഓർക്കുക: ഇന്ന് നാം നടുന്ന ചെറിയ തൈയാണ് നാളെ നമുക്ക് തണലും പഴങ്ങളും തരുന്നത്!


    നിങ്ങളുടെ അച്ഛനോടും അമ്മയോടും ഈ കാര്യത്തെക്കുറിച്ച് ചോദിച്ചു നോക്കൂ. അവർക്കും ഇതൊരു പുതിയ അറിവായേക്കാം!

  • SIP Today SWP Tomorrow

    SIP Today SWP Tomorrow

    Have you ever seen a mango tree? When it is small, you water it every day. You take care of it. It does not give fruits immediately. But after a few years, that same tree gives you tasty mangoes every summer!

    Saving and investing money works the same way.

    What is SIP?

    SIP means Systematic Investment Plan.

    It is like watering the tree.

    You put small amounts of money every month into an investment (like mutual funds). Slowly, this money grows over time.

    What is SWP?

    SWP means Systematic Withdrawal Plan.

    It is like taking mangoes from the tree when it grows big.

    After many years, when your money has grown, you can take out some money every month to use for your needs. You don’t have to take everything at once.


    Let’s Learn Through a Small Story

    There was a boy named Rohan who loved to eat mangoes. His father told him:

    “If you want mangoes in the future, you must plant a sapling today!”

    So Rohan planted a small mango plant in the backyard. Every day he did a few things:

    ✓ He watered it
    ✓ He protected it from goats
    ✓ He gave it sunlight and care

    This was his SIP — Small Important Practice every day.

    Years passed… the plant became a big mango tree. Now every summer, the tree gave so many mangoes that Rohan and his family enjoyed them without buying from the shop. They even shared with relatives!

    This was like SWP — Summer Wonderful Picking!

    Because Rohan took small steps earlier, he enjoyed big benefits later.


    What Does This Mean for Money?

    When we start a SIP today, we are putting money regularly (like watering the plant).

    After many years, when we need money for:

    ✓ Children’s education
    ✓ Retirement
    ✓ Monthly expenses
    ✓ Buying a house

    We can use SWP to take money out slowly and safely, without finishing everything at once (just like not cutting the mango tree!).


    Why Is This Good?

    ✔ SIP makes saving easy — small amounts every month
    ✔ Money grows over time — like a plant becoming a tree
    ✔ SWP gives regular money — like getting mangoes every season
    ✔ No pressure — you don’t need to invest a big amount at once
    ✔ Perfect for long-term goals


    In Simple Words

    🌱 SIP Today = Plant the tree
    🍃 Wait and let it grow
    🥭 SWP Tomorrow = Enjoy the fruits


    Conclusion

    Many people think that money grows only when we earn a lot. But the truth is:

    Money grows when we start early, invest regularly, and allow time to work.

    Just like Rohan’s tree, if we start a SIP today, we can enjoy a peaceful future with SWP tomorrow.

    So the magic formula is:

    👉 Start Small + Be Regular + Wait = Big Benefits Later